
Frontdoor has been on fire lately. In the past six months alone, the company’s stock price has rocketed 41.6%, reaching $73.55 per share. This was partly thanks to its solid quarterly results, and the run-up might have investors contemplating their next move.
Is there a buying opportunity in Frontdoor, or does it present a risk to your portfolio? Check out our in-depth research report to see what our analysts have to say, it’s free.
Why Do We Think Frontdoor Will Underperform?
Despite the momentum, we don’t have much confidence in Frontdoor. Here are three reasons why FTDR doesn’t excite us, plus one stock we’d rather own.
1. Long-Term Revenue Growth Disappoints
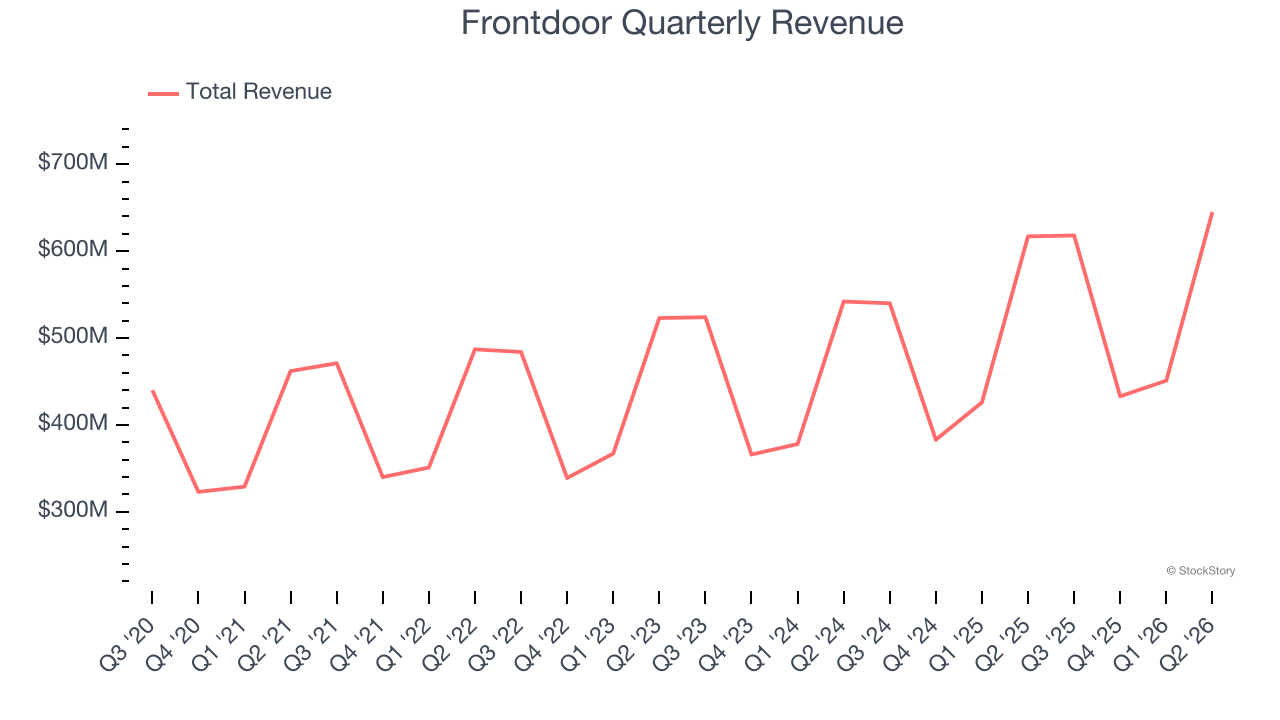
A company’s long-term performance is an indicator of its overall quality. Any business can have short-term success, but a top-tier one grows for years. Over the last five years, Frontdoor grew its sales at a weak 6.7% compounded annual growth rate. This was below our standard for the consumer discretionary sector.
2. Cash Flow Margin Set to Decline
Free cash flow isn’t a prominently featured metric in company financials and earnings releases, but we think it’s telling because it accounts for all operating and capital expenses, making it tough to manipulate. Cash is king.
Over the next year, analysts predict Frontdoor’s cash conversion will slightly fall. Their consensus estimates imply its free cash flow margin of 18% for the last 12 months will decrease to 16%.
3. New Investments Fail to Bear Fruit as ROIC Declines
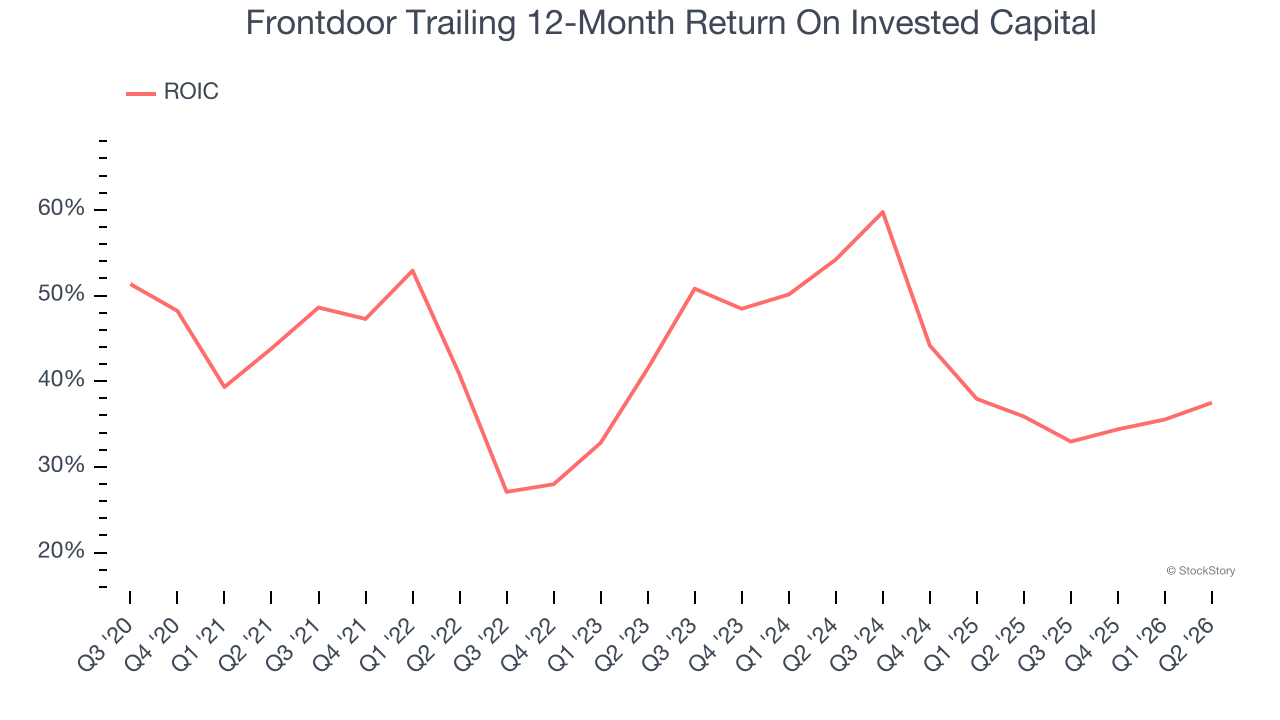
We like to invest in businesses with high returns, but the trend in a company’s ROIC can also be an early indicator of future business quality.
Unfortunately, Frontdoor’s ROIC averaged 4.4 percentage point decreases each year over the last few years. We like what management has done in the past, but its declining returns are perhaps a symptom of fewer profitable growth opportunities.
Final Judgment
Frontdoor doesn’t pass our quality test. Following the recent rally, the stock trades at 14.7× forward P/E (or $73.55 per share). This valuation is reasonable, but the company’s shaky fundamentals present too much downside risk. There are better investments elsewhere. We’d suggest looking at one of our all-time favorite software stocks.
Stocks We Like More Than Frontdoor
ONE MORE THING: Top 6 Stocks for This Week. This market is separating quality stocks from expensive ones fast. AI is taking down whole sectors with no warning. In a rotation this fast, you need more than a list of good companies.
Our AI system flagged Palantir before it ran 1,662% between October 2022 and February 2026. AppLovin before it ran 753% between February 2024 and February 2026. Nvidia before it ran 1,178% between January 2023 and February 2026. Each week it produces 6 new names that pass the same tests. Get Our Top 6 Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Tecnoglass (+1,552% between June 2020 and June 2025). Find your next big winner with StockStory today.