Mineral rights owner Black Stone Minerals (NYSE: BSM) missed Wall Street’s revenue expectations in Q3 2026, with revenue falling 24.7% year on year to $99.73 million. Its GAAP profit of $0.21 per share was 19.2% below analysts’ consensus estimates.
For more on Black Stone Minerals, read our free full research report.
Black Stone Minerals (BSM) Q3 2026 highlights:
- Revenue $99.73 million vs S&P analysts’ consensus estimates of $114.1 million (24.7% year-on-year decline, 12.6% miss)
- EPS (GAAP) $0.21 vs analysts’ consensus estimates of $0.26 (19.2% miss)
- Adjusted EBITDA $104.1 million vs analysts’ consensus estimates of $84.36 million (104% margin, 23.4% beat)
- Operating margin 56.4%, down from 71% in the same quarter last year
- Oil production down -2.1% year on year
- Market capitalization $3.16 billion
“LNG exports, power generation, and other sources of demand will require significant long-term natural gas supply, and we believe Black Stone is well positioned to help provide the drilling inventory needed to support that growth. Our strategy has been to assemble large, high-interest mineral positions in the expanded Shelby Trough, contiguous to our legacy assets, and place that acreage into structured development programs. The expanded Caturus agreement increases the acreage and long-term drilling inventory subject to structured development programs, further advancing development of Black Stone’s Shelby Trough position.”
Revenue growth
Cyclical sectors like energy often flatter weaker operators during favorable price environments, but a longer-term lens separates those from businesses that can consistently perform across market cycles. Black Stone Minerals’s 10.7% annualized revenue growth over the last five years was decent. Its growth was slightly above that of the average energy upstream and integrated energy company and shows its offerings resonate with customers.
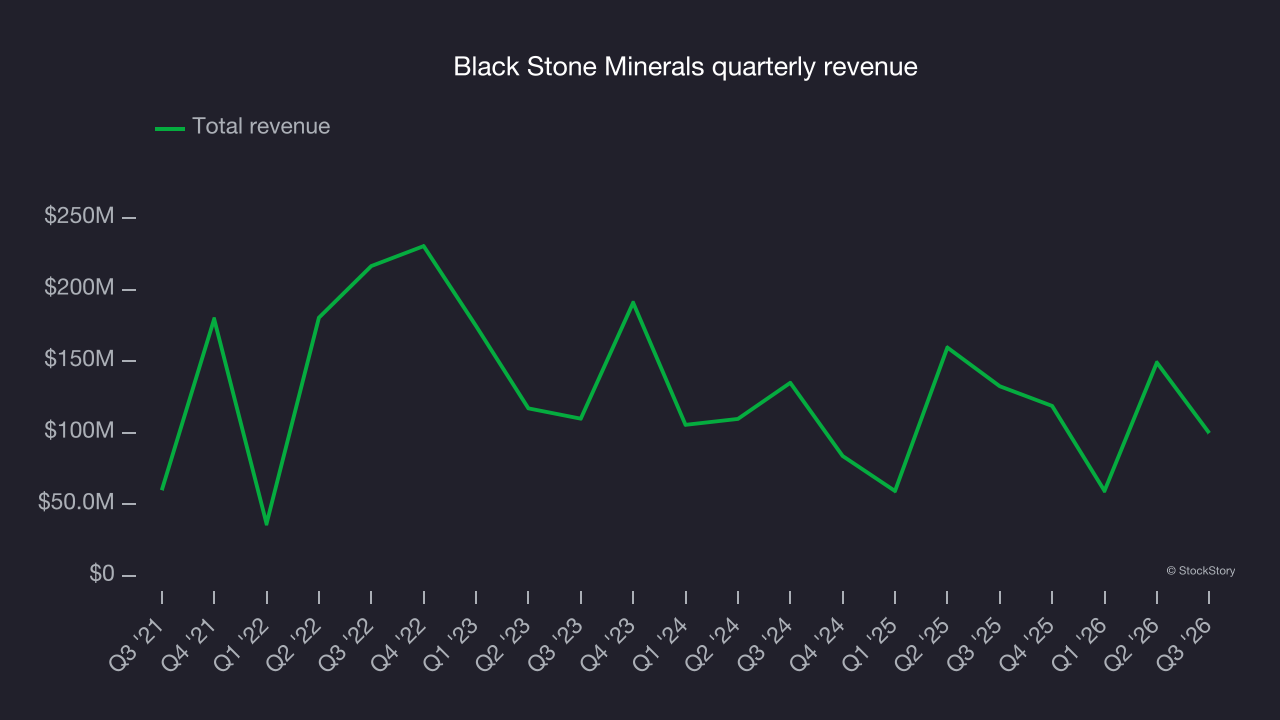
Energy cycles can be long enough that a single five-year period can still reflect one price environment, which is why an additional, decade-long view can help capture through-cycle performance. Black Stone Minerals’s annualized revenue growth of 3.4% over the last ten years is below its five-year trend, but the results were still good.
Revenue provides useful context, but it is heavily influenced by commodity prices and acquisitions. Production volumes, by contrast, reveal whether the underlying asset base is actually growing. Over the last two years, Black Stone Minerals’s oil production averaged 5.9% year-on-year declines while its natural gas production averaged 7% year-on-year declines. 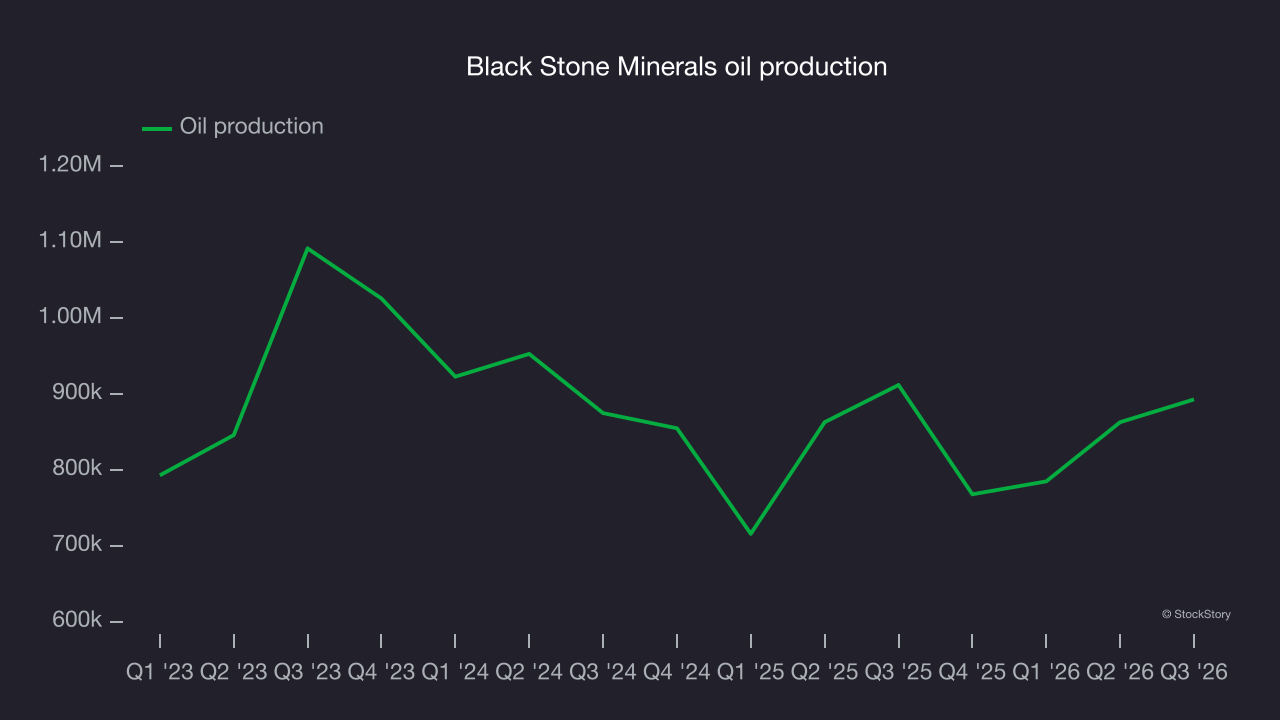
This quarter, Black Stone Minerals missed Wall Street’s consensus estimates and reported an uninspiring 24.7% year-on-year revenue decline, generating $99.73 million of revenue. Its oil production fell by 2.1% year on year.
Adjusted EBITDA margin
Adjusted EBITDA margin is an important measure of profitability for the sector and accounts for the gross margins and operating costs mentioned previously. Unlike operating margin, it is not distorted by accounting conventions around reserves, drilling costs and assumptions on commodity consumption from the well or basin. Adjusted EBITDA highlights the economic reality of how much cash the rock produces before the capital structure (debt service) and the drilling budget (capex) are considered.
Black Stone Minerals has performed well over the last five years. It demonstrated high profitability for an upstream and integrated energy business, with an average EBITDA margin of 76.2%.
Looking at the trend in its profitability, Black Stone Minerals’s EBITDA margin rose by 16.8 percentage points over the last year, as its revenue growth provided significant operating leverage.
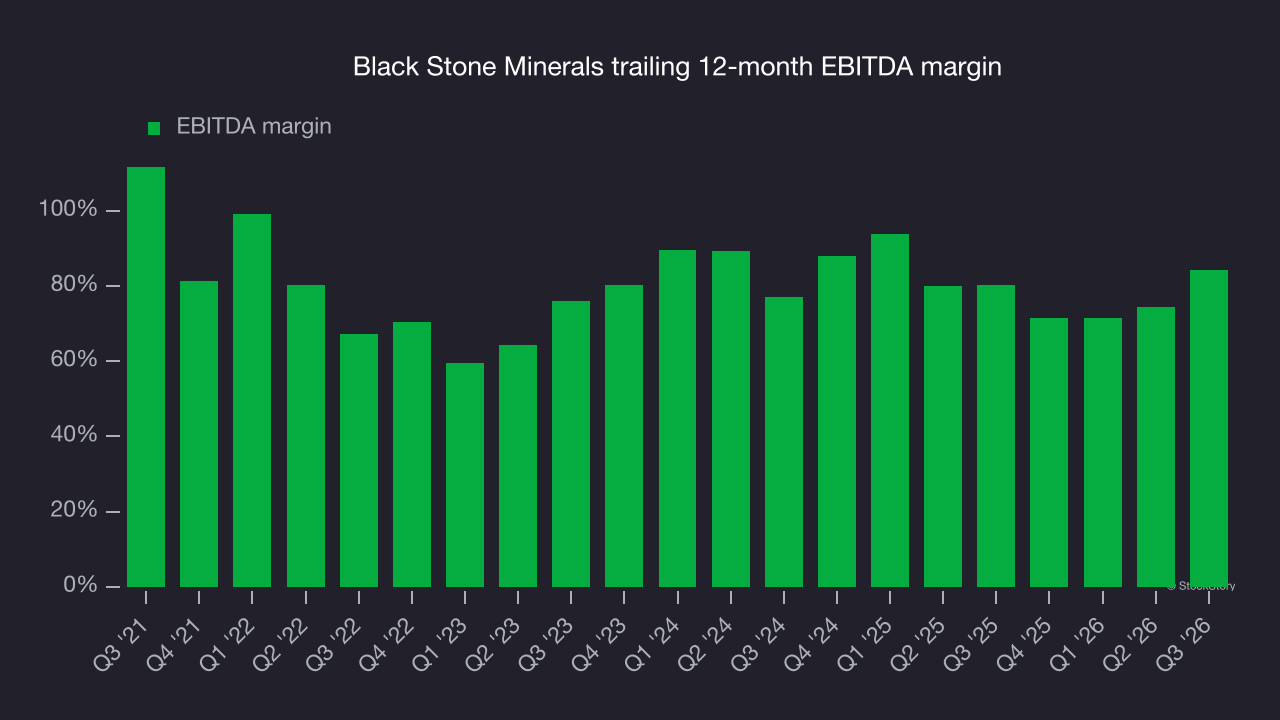
In Q3, Black Stone Minerals generated an EBITDA margin of 104%, up 39.2 percentage points year on year. This increase was a positive development, especially since its revenue fell, showing it became more efficient by reducing expenses. Adjusted EBITDA beat Wall Street’s consensus estimates by 23.4%.
Free cash flow
As mentioned above, adjusted EBITDA ignores capital structure and drilling expenditure decisions. These are two major aspects of an energy producer’s business, so an investor needs to account for them to get a comprehensive picture of business quality. In other words, adjusted EBITDA margins could be solid but free cash flow could be poor because asset decline rates are high and drilling is expensive. Free cash flow tells you not only about the economics of past production but also how much it costs to stay in business through further drilling or extraction.
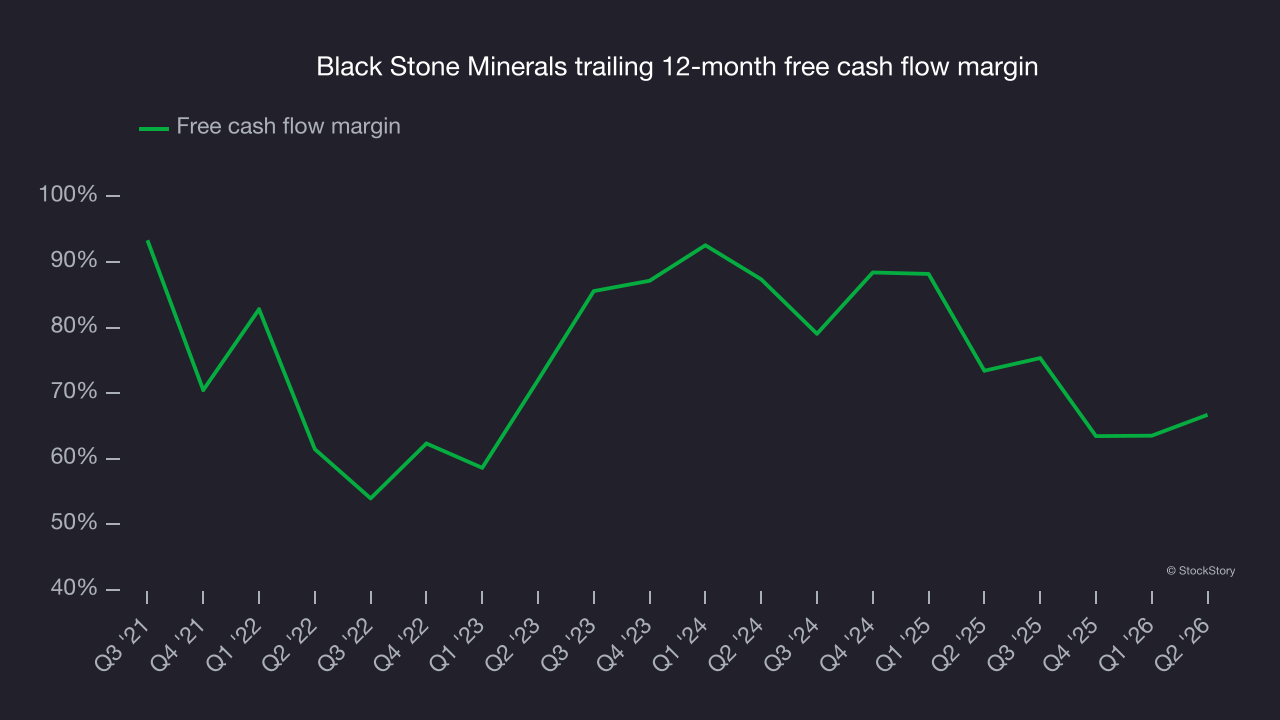
Black Stone Minerals has shown strong cash profitability, enabling it to reinvest, return capital to investors and stay ahead of the competition while maintaining an ample cushion. The company’s free cash flow margin was among the best in the energy upstream and integrated energy sector, averaging 72% over the last five years.
Absolute free cash flow margin levels matter, but so does the stability of free cash flow. All else equal, a steady 25.0% average free cash flow margin regardless of commodity prices is preferable to very high margins when times are good and negative ones when they’re tough.
Black Stone Minerals’s ratio of quarterly free cash flow volatility to volatility in West Texas Intermediate, or WTI, crude oil prices over the past five years was 2 (lower is better), indicating strong insulation from commodity swings. This stability supports superior capital access in downturns and positions Black Stone Minerals to act as a consolidator when weaker peers are forced to retrench.
Why assess stability against commodity prices at the free cash flow line rather than compare revenue or EBITDA to WTI in the case of Black Stone Minerals? What ultimately matters is not how much revenue or profit a company earns when prices are high but how much cash it can generate when prices are low. Free cash flow is the superior metric because it includes everything from hedging effectiveness to growth and maintenance capex to management behavior during good times and bad.
Key takeaways from Black Stone Minerals’s Q3 results
Black Stone Minerals’ sizable EBITDA beat was a bright spot, but revenue and EPS both missed Wall Street’s consensus estimates, leaving room for a better quarter overall. Shares remained flat at $14.77 immediately after the results.
When deciding whether to buy Black Stone Minerals, it’s important to consider its valuation, business qualities and what happened in the latest quarter. Read the full research report here (it’s free).