
Since April 2026, Helios has been in a holding pattern, posting a small return of 2.9% while floating around $69.50. The stock also fell short of the S&P 500’s 8.1% gain during that period.
Is there a buying opportunity in Helios, or does it present a risk to your portfolio? Get the full stock story straight from our expert analysts, it’s free.
Why do we think Helios will underperform?
We don’t have much confidence in Helios. Here are three reasons we avoid HLIO, plus one stock we’d rather own.
1. Slow organic growth suggests waning demand in core business
Investors interested in gas and liquid handling companies should track organic revenue in addition to reported revenue. This metric gives visibility into Helios’s core business because it excludes one-time events such as mergers, acquisitions, and divestitures along with foreign currency fluctuations - non-fundamental factors that can manipulate the income statement.
Over the last two years, Helios’s organic revenue averaged 4.5% year-on-year growth. This performance was underwhelming and suggests it may need to improve its products, pricing, or go-to-market strategy, which can add an extra layer of complexity to its operations. 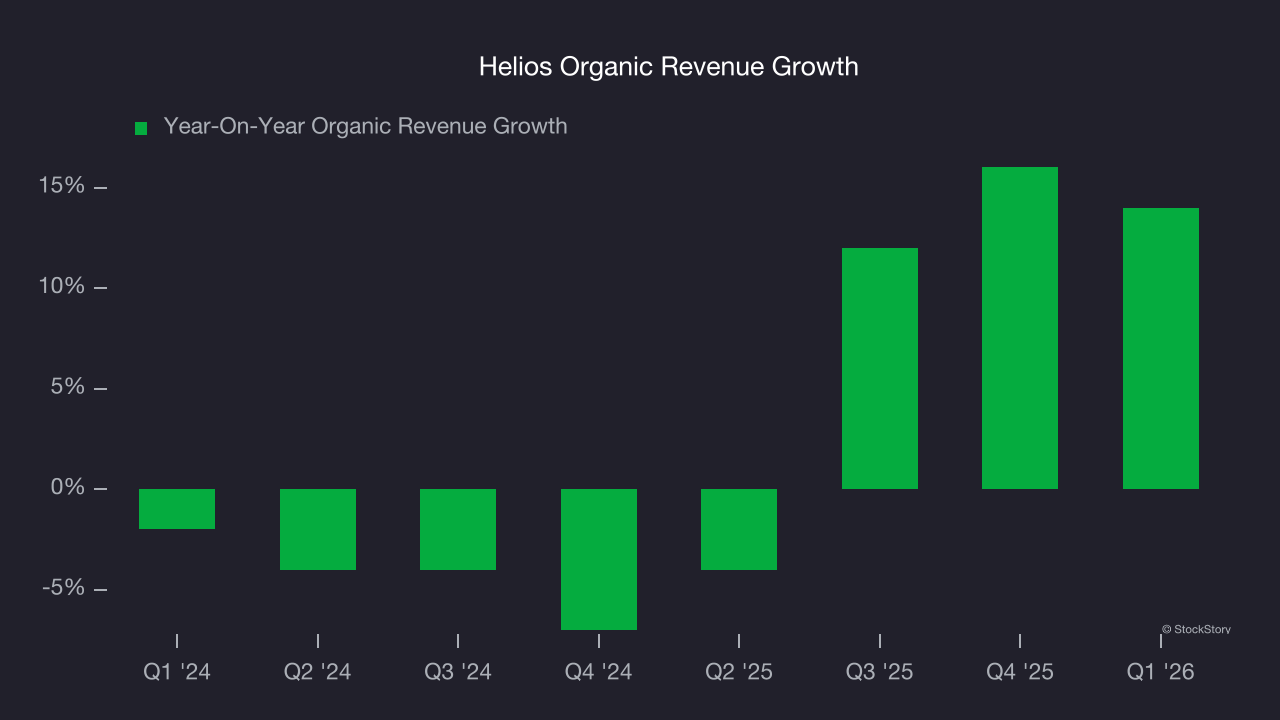
2. Shrinking operating margin
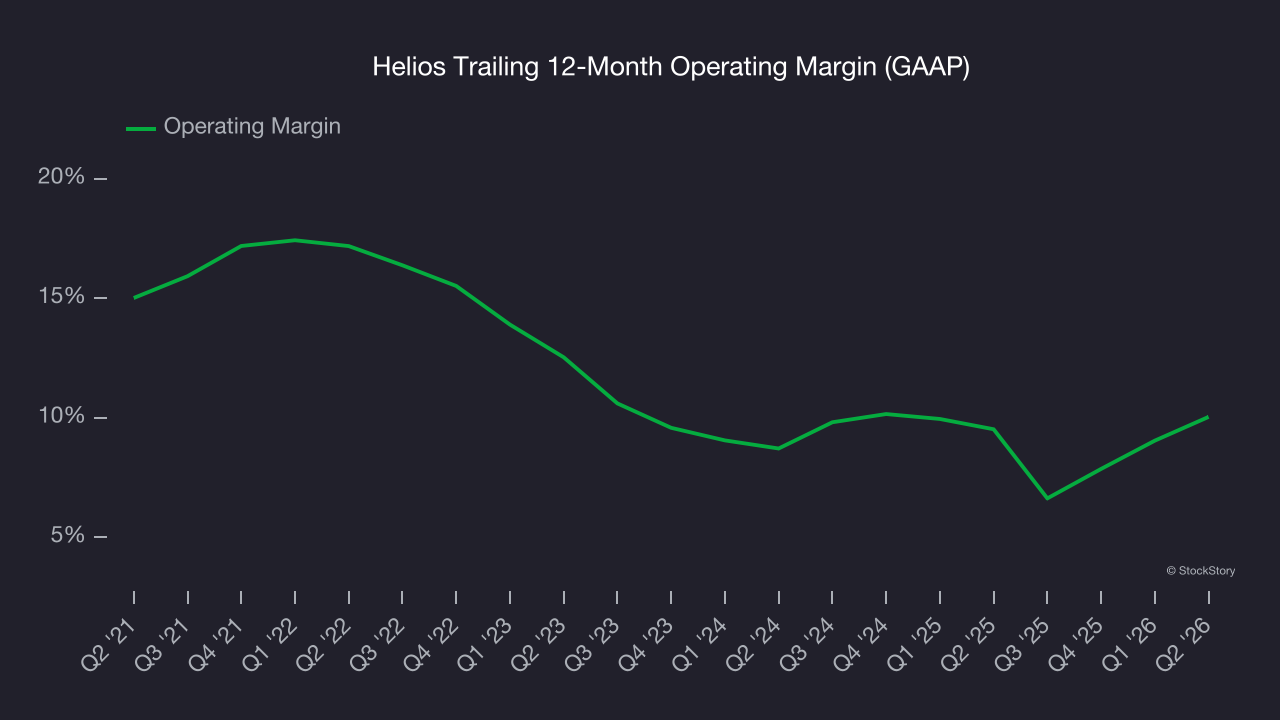
Operating margin is a key measure of profitability. Think of it as net income - the bottom line - excluding the impact of taxes and interest on debt, which are less connected to business fundamentals.
Looking at the trend in its profitability, Helios’s operating margin decreased by 7.1 percentage points over the last five years. This raises questions about the company’s expense base because its revenue growth should have given it leverage on its fixed costs, resulting in better economies of scale and profitability. Its operating margin for the trailing 12 months was 10%.
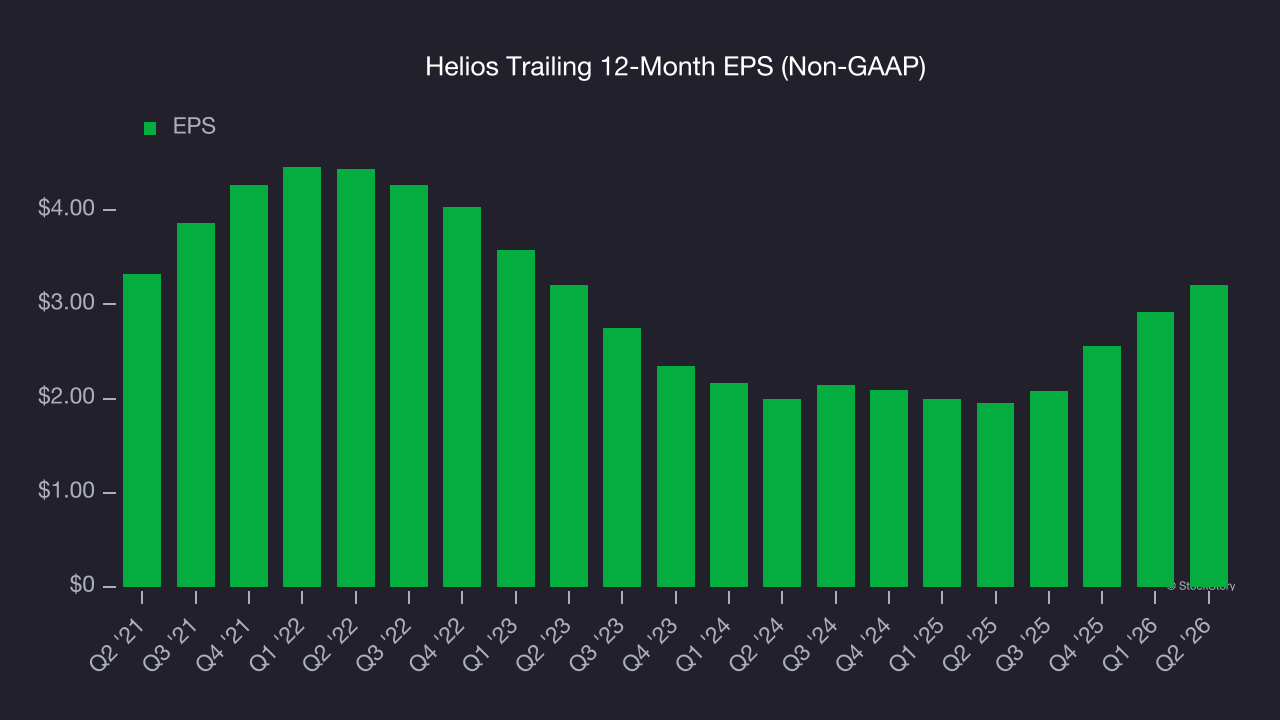
3. EPS growth has stalled
Analyzing the long-term change in earnings per share (EPS) shows whether a company’s incremental sales were profitable — for example, revenue could be inflated through excessive spending on advertising and promotions.
Helios’s flat EPS over the last five years was below its 4.9% annualized revenue growth. This tells us the company became less profitable on a per-share basis as it expanded.
Final judgment
We see the value of companies helping their customers, but in the case of Helios, we’re out. With its shares lagging the market recently, the stock trades at 20.5× forward P/E (or $69.50 per share). This multiple tells us a lot of good news is priced in - we think other companies feature superior fundamentals at the moment. We’d recommend looking at an all-weather company that owns household favorite Taco Bell.
High-quality stocks for all market conditions
WHILE YOU’RE HERE: Top 9 Market-Beating Stocks. The best stocks don’t just beat the market once. They do it again. And again. Robust revenue growth, rising free cash flow, returns on capital that leave their competition in the dust. The market has already rewarded these businesses.
But our AI platform says the party isn’t over. Find out which 9 stocks made the cut this week — FREE. Get Our Top 9 Market-Beating Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Kadant (+214% between June 2020 and June 2025). Find your next big winner with StockStory today.