Oil and gas producer California Resources (NYSE: CRC) fell short of the market’s revenue expectations in Q3 2026, with revenue falling 52.2% year on year to $421 million. Its non-GAAP profit of $1.17 per share was 21.1% above analysts’ consensus estimates.
For more on California Resources, read our full research report for free.
California Resources (CRC) Q3 2026 highlights:
- Revenue $421 million vs S&P analysts’ consensus estimates of $966.9 million (52.2% year-on-year decline, 56.5% miss)
- Adjusted EPS $1.17 vs S&P analysts’ consensus estimates of $0.97 (21.1% beat)
- Operating margin -96.7%, down from 11.2% in the same quarter last year
- Free cash flow margin 34.9%, up from 21.3% in the same quarter last year
- Oil production per day rose 13.1% year on year
- Market capitalization $4.93 billion
"Our team continues to execute exceptionally well through strong operational performance, synergy realization from our strategic initiatives and impressive free cash flow,” said Francisco Leon, CRC’s President and Chief Executive Officer. “Through continued capital discipline and the ongoing focus on sustainable efficiency gains, we are improving free cash flow and our liquidity profile. In addition, we remain committed to our shareholder capital return program with share repurchases and dividends, the latter demonstrated by the 4% dividend per share increase we announced today. We have also made significant progress on strategic priorities, including the Crimson pipeline acquisition, along with the Uinta Basin asset sale and Bloom Energy partnership. These initiatives broaden and strengthen our commitment to the Golden State while continuing to deliver value to all CRC constituents including our shareholders and California communities.”
Revenue growth
Cyclical sectors like energy often flatter weaker operators during favorable price environments, but a longer-term lens separates those from businesses that can consistently perform across market cycles. California Resources’s revenue grew at a decent 11.4% compounded annual growth rate over the last five years. Its growth was slightly above the average energy upstream and integrated energy company and shows its offerings resonate with customers.
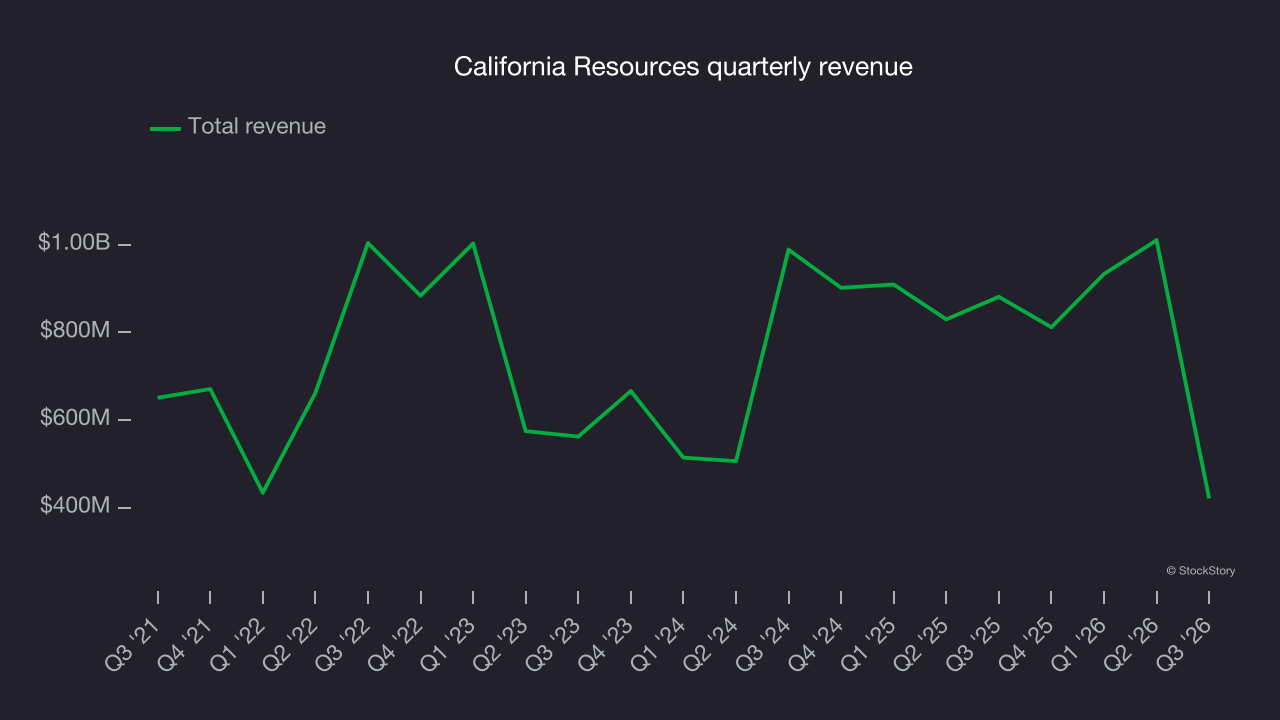
Within energy, a single time frame, even a long one, only sheds light on how well a company rode the last commodity cycle. To better assess whether a company compounds through cycles, a longer, ten-year view provides a check. California Resources’s annualized revenue growth of 6.7% over the last ten years is below its five-year trend, but the results were still good.
Revenue provides useful context, but it is heavily influenced by commodity prices and acquisitions. Production volumes, by contrast, reveal whether the underlying asset base is actually growing. Over the last two years, California Resources’s oil production per day averaged 51.8% year-on-year growth while its natural gas production per day remained flat.
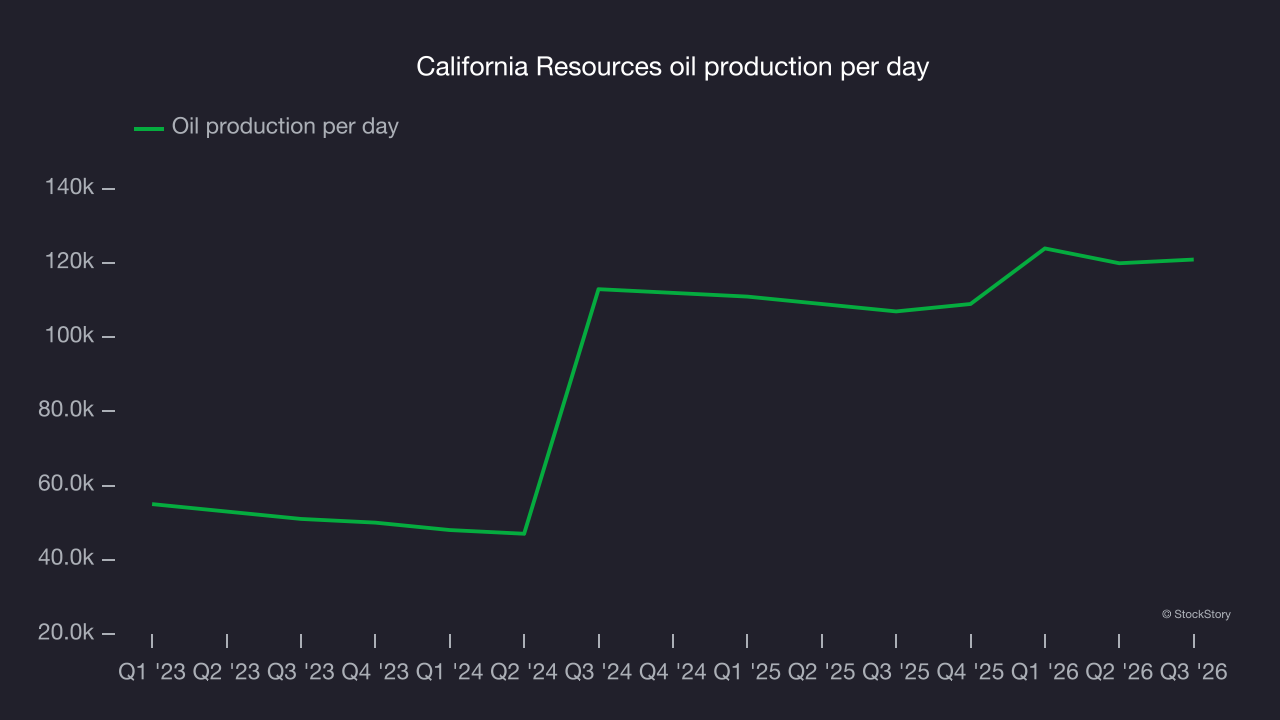
This quarter, California Resources missed Wall Street’s consensus estimates and reported an uninspiring 52.2% year-on-year revenue decline, generating $421 million of revenue. Its oil production per day grew 13.1% year on year.
Adjusted EBITDA margin
California Resources was profitable over the last five years but held back by its large cost base. Its average EBITDA margin of 32% was weak for an upstream and integrated energy business.
California Resources’s EBITDA margin decreased by 20.2 percentage points over the last year. This raises questions about the company’s expense base because its revenue growth should have given it leverage on its fixed costs, resulting in better economies of scale and profitability. California Resources’s poor performance shows that costs were rising and it couldn’t pass them on to its customers.
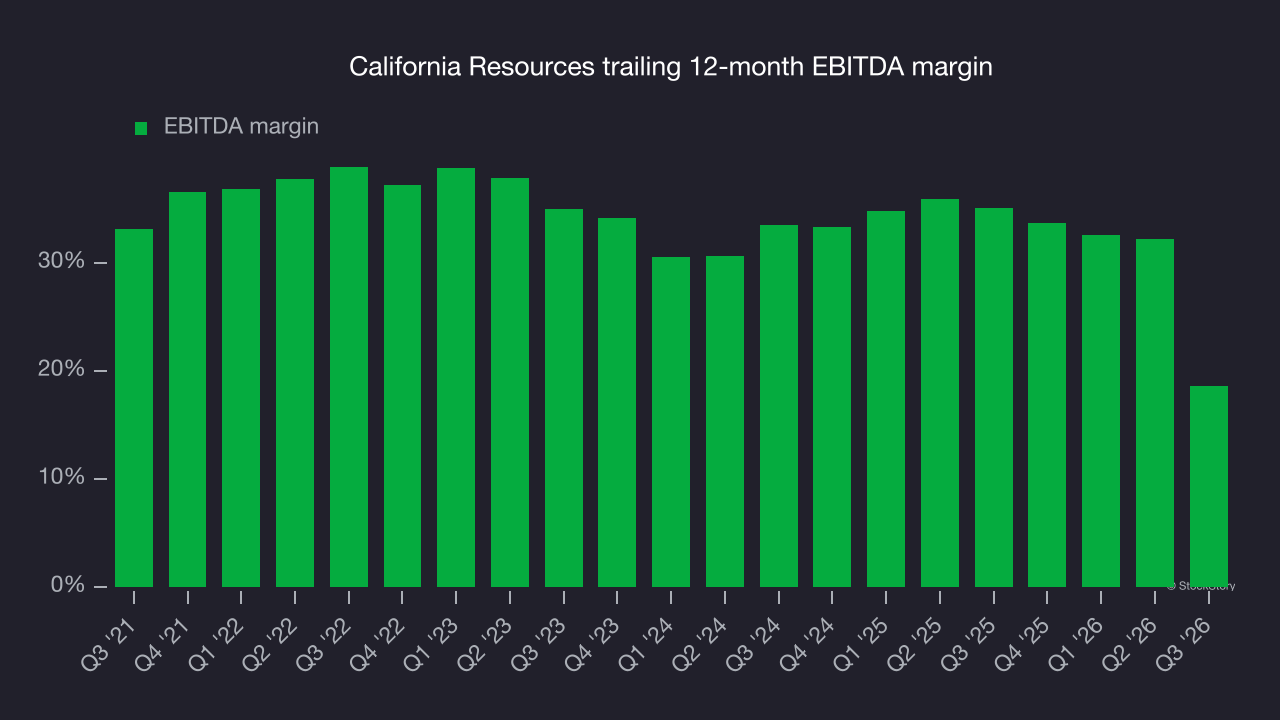
In Q3, California Resources generated an EBITDA margin of negative 64.1%, down 99.1 percentage points year on year. This contraction shows it was less efficient because its expenses increased relative to its revenue. This adjusted EBITDA fell short of Wall Street’s consensus estimates.
Free cash flow
Adjusted EBITDA shows how profitable a company’s existing wells are before financing and reinvestment decisions, but free cash flow shows how much value remains after paying the cost of replacing those wells. In upstream energy, production naturally declines over time, so companies must continuously reinvest just to stand still. A producer can report strong EBITDA margins yet generate little or no free cash flow if its wells decline quickly or if new drilling is expensive. Free cash flow therefore captures not only how efficiently a company produces hydrocarbons today, but also how costly it is to sustain that production into the future.
California Resources has shown strong cash profitability, driven by its attractive business model that enables it to reinvest or return capital to investors. The company’s free cash flow margin averaged 13.5% over the last five years, a notable result for an upstream and integrated energy business.
While the level of free cash flow margins is important, their consistency matters just as much.
California Resources’s ratio of quarterly free cash flow volatility to West Texas Intermediate, or WTI, crude price volatility over the past five years was 4.1 (lower is better), indicating strong insulation from commodity swings. This stability supports superior capital access in downturns and positions California Resources to act as a consolidator when weaker peers are forced to retrench.
Why assess stability against commodity prices at the free cash flow line rather than compare revenue or EBITDA with WTI for California Resources? Because what ultimately matters is not how much revenue or profit a company earns when prices are high but how much cash it can generate when prices are low. Free cash flow is the superior metric because it includes everything from hedging effectiveness to growth and maintenance capex to management behavior during good times and bad.
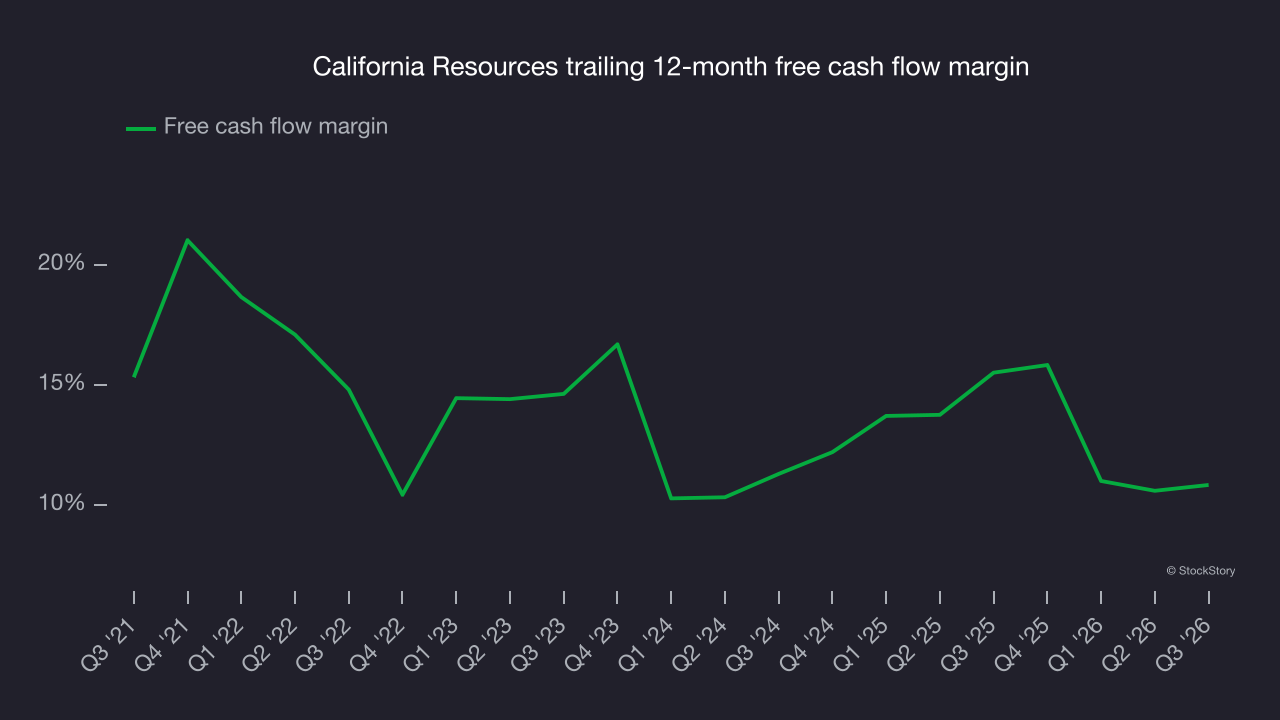
California Resources’s free cash flow totaled $147 million in Q3, equivalent to a 34.9% margin. This was a good result, as its margin was 13.6 percentage points higher than in the same quarter last year. Its cash profitability was also above its five-year level.
Key takeaways from California Resources’s Q3 results
California Resources’ Q3 results had some key positives, led by EPS that beat analysts’ consensus estimates. Revenue, however, missed expectations due to loses from commodity sales derivatives. Shares edged higher 1.9% to $53.47 immediately after the results.
When deciding whether to invest in California Resources, consider the bigger picture of valuation and business quality, as well as the latest earnings. Read the full research report here (it’s free).