Infrastructure construction company MasTec (NYSE: MTZ) beat Wall Street’s revenue expectations in Q3 2026, with revenue up 29.9% year on year to $5.15 billion. The company’s full-year revenue guidance of $18.3 billion at the midpoint came in 0.6% above analysts’ consensus estimates. Its non-GAAP profit of $2.96 per share was in line with analysts’ consensus estimates.
For more on MasTec, read our full research report, available free.
MasTec (MTZ) Q3 2026 highlights:
- Revenue $5.15 billion vs S&P analysts’ consensus estimates of $4.94 billion (29.9% year-on-year growth, 4.3% beat)
- Adjusted EPS $2.96 vs S&P analysts’ consensus estimates of $2.96 (in line)
- Adjusted EBITDA $486.4 million vs analysts’ consensus estimates of $478.3 million (9.4% margin, 1.7% beat)
- Adjusted EPS guidance Management lowered its full-year adjusted EPS guidance to $9.11 at the midpoint, a 2% decrease
- EBITDA guidance $1.58 billion at the midpoint for the full year, below analysts’ consensus estimates of $1.60 billion
- Operating margin 5.3%, down from 6.4% in the same quarter last year
- Free cash flow margin 4%, up from 0.5% in the same quarter last year
- Backlog $24.55 billion at quarter end, up 46.3% year on year
- Market capitalization $14.35 billion
“As we noted throughout the third quarter, permitting related access delays on certain Pipeline projects impacted margins, as crews and equipment were underutilized. Construction has now commenced, and we are ramping production. Given the substantial number of pipelines expected to enter service over the next few years, we believe retaining our experienced crews is critical to capitalize on the significant level of industry investment ahead. We’re seeing this demand set play out, with Pipeline Infrastructure backlog growing ~26% sequentially in the quarter.”
Revenue growth
Examining a company’s long-term performance can provide clues about its quality. Any business can put up a good quarter or two, but the best consistently grow over the long haul. MasTec’s 17.3% annualized revenue growth over the last five years was strong. Its growth surpassed the average industrials company and shows its offerings resonate with customers.
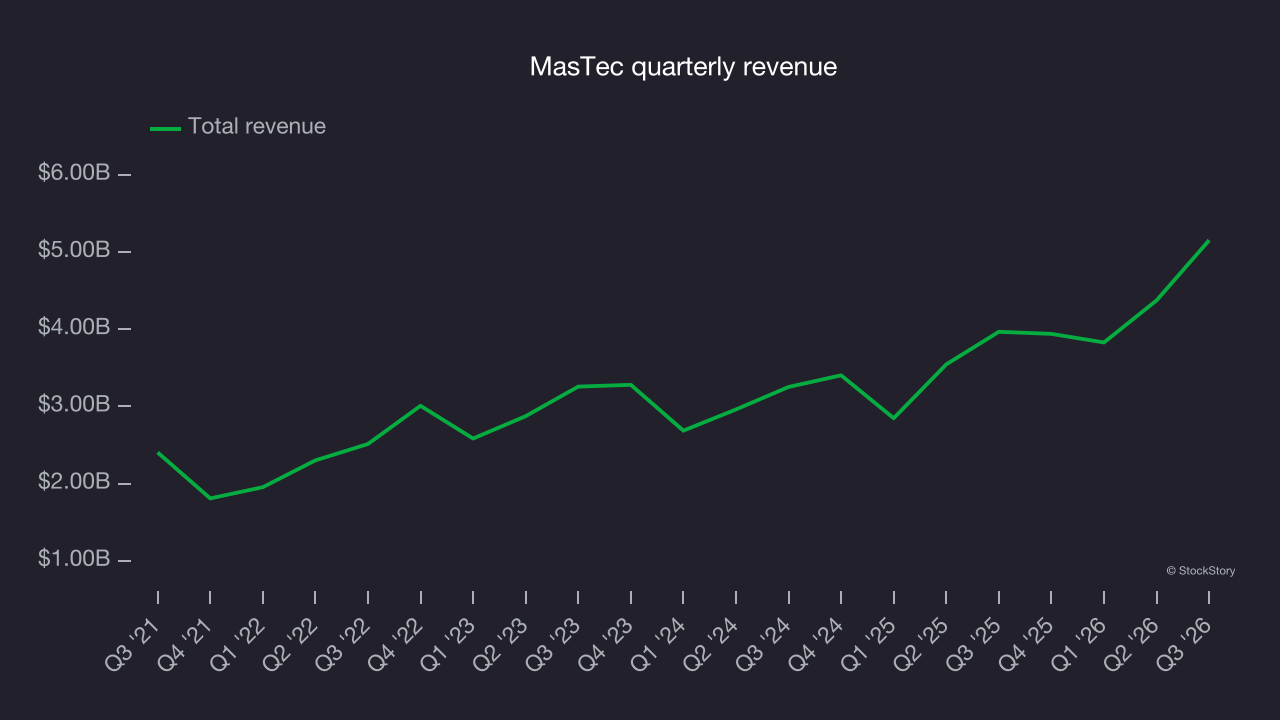
Long-term growth is the most important, but within industrials, a half-decade historical view may miss new industry trends or demand cycles. MasTec’s annualized revenue growth of 19.2% over the last two years is above its five-year trend, suggesting its demand was strong and recently accelerated. 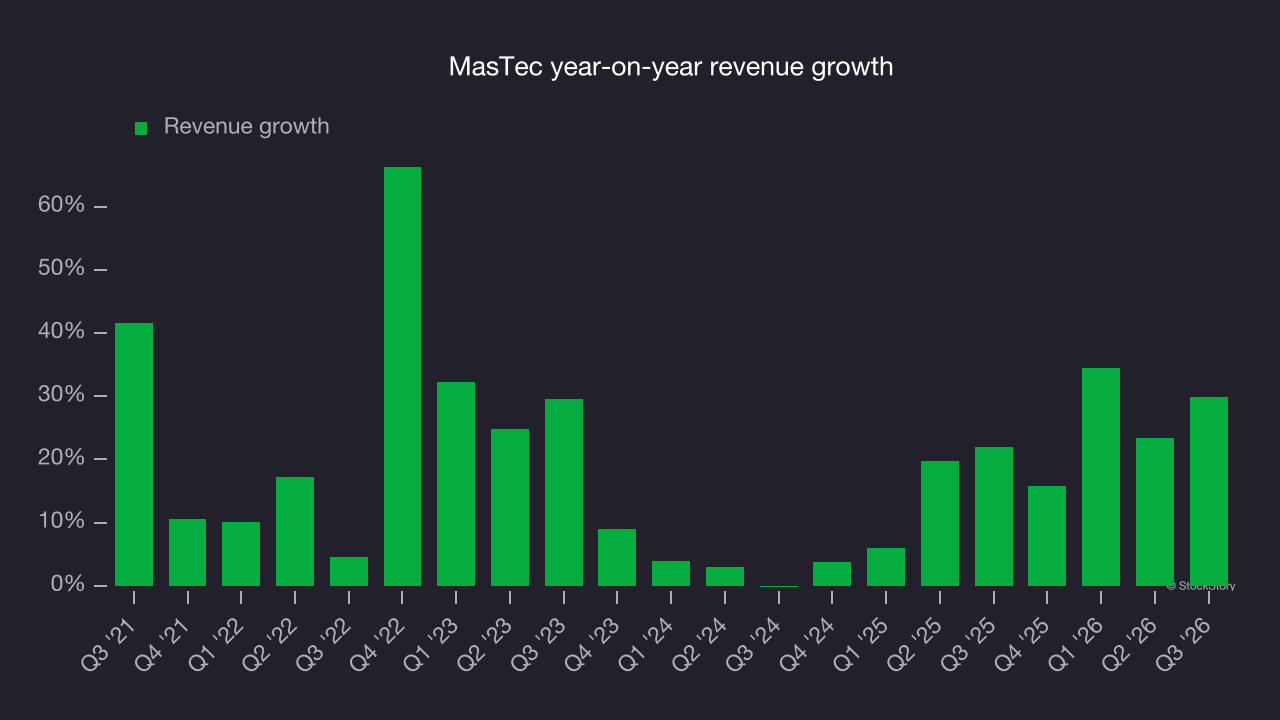
MasTec also reports its backlog, or the value of its outstanding orders that have not yet been executed or delivered. MasTec’s backlog reached $24.55 billion in the latest quarter and averaged 27.6% year-on-year growth over the last two years. Backlog growth outpaced revenue growth, indicating the company accumulated more orders than it could fulfill and deferred revenue to the future. This could imply elevated demand for MasTec’s products and services but raises concerns about capacity constraints. 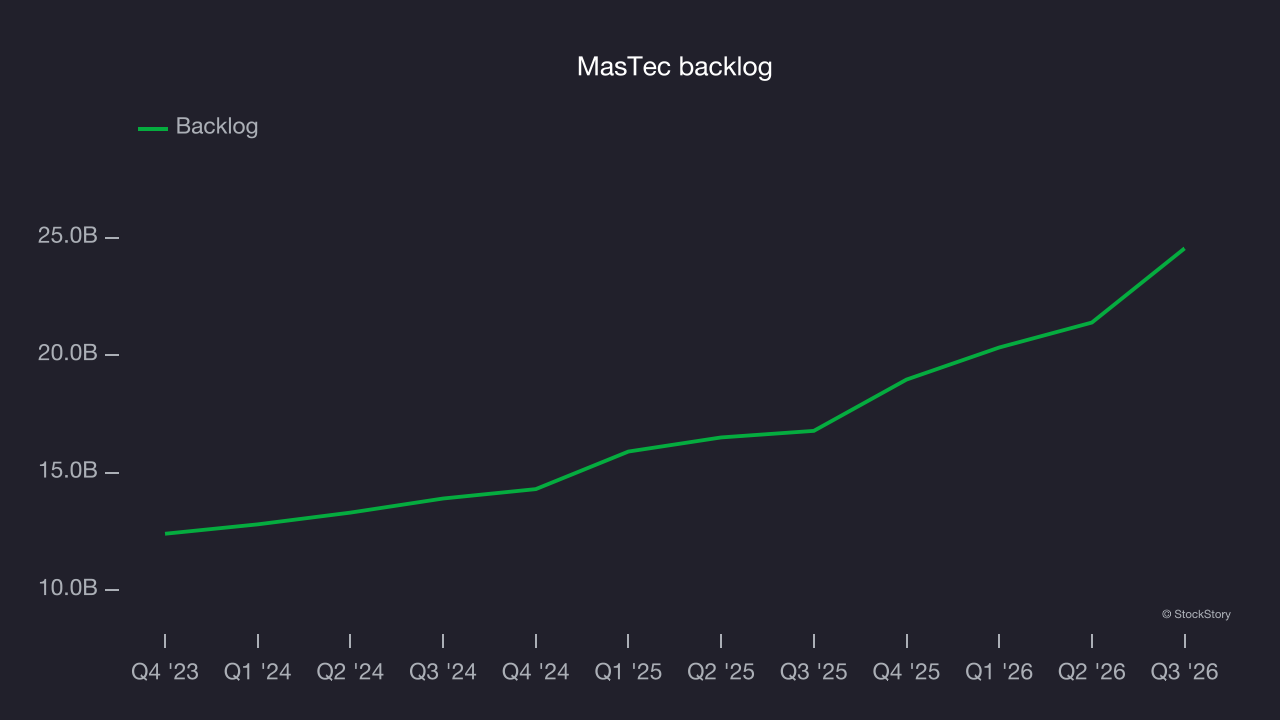
This quarter, MasTec reported strong year-on-year revenue growth of 29.9%, and its $5.15 billion of revenue topped Wall Street’s consensus estimates by 4.3%.
Looking ahead, sell-side analysts expect revenue to grow 20.8% over the next 12 months, according to S&P, an improvement versus the last two years. This projection is strong for a company of its scale and indicates its newer products and services will spur better top-line performance.
Operating margin
Operating margin is an important measure of profitability as it shows the portion of revenue left after accounting for all core expenses, from the cost of goods sold to advertising and wages. It’s also useful for comparing profitability across companies with different levels of debt and tax rates because it excludes interest and taxes.
MasTec was profitable over the last five years but held back by its large cost base. Its average operating margin of 3.2% was weak for an industrials business. That outcome is unsurprising given its low gross margin baseline.
On the positive side, MasTec’s operating margin rose by 3.2 percentage points over the last five years, as its revenue growth provided operating leverage.
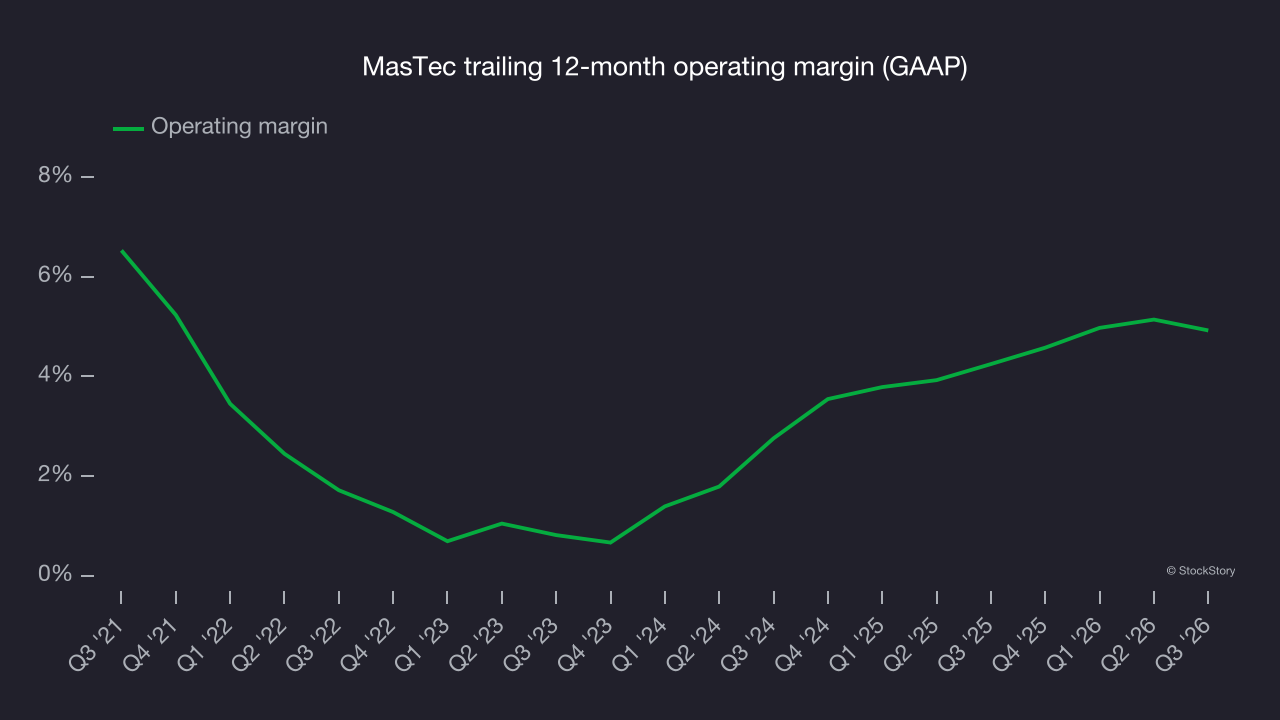
This quarter, MasTec generated an operating margin of 5.3%, down 1 percentage point year on year. Its operating margin decreased more than its gross margin, suggesting it was less efficient because expenses such as marketing, R&D and administrative overhead increased.
Earnings per share
Revenue trends explain a company’s historical growth, but the long-term change in earnings per share (EPS) points to the profitability of that growth. For example, a company could inflate its revenue through excessive spending on advertising and promotions.
MasTec’s EPS grew at an unimpressive 7.7% compounded annual growth rate over the last five years, lower than its 17.3% annualized revenue growth. However, its operating margin improved during this time, indicating that non-fundamental factors such as interest expenses and taxes affected its ultimate earnings.
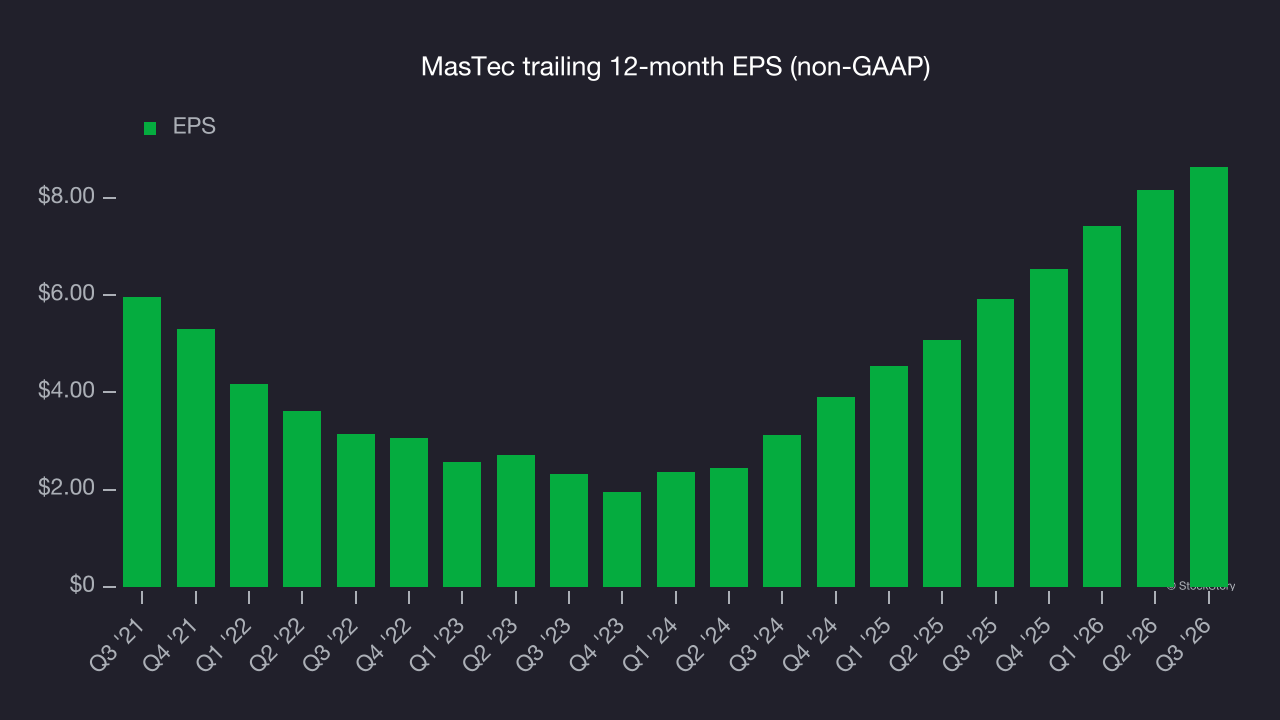
A closer look at MasTec’s earnings helps explain its performance. A five-year view shows MasTec has diluted its shareholders, growing its share count by 7.9%. This dilution overshadowed its increased operational efficiency and has led to lower per share earnings. Taxes and interest expenses can also affect EPS but don’t tell us as much about a company’s fundamentals. 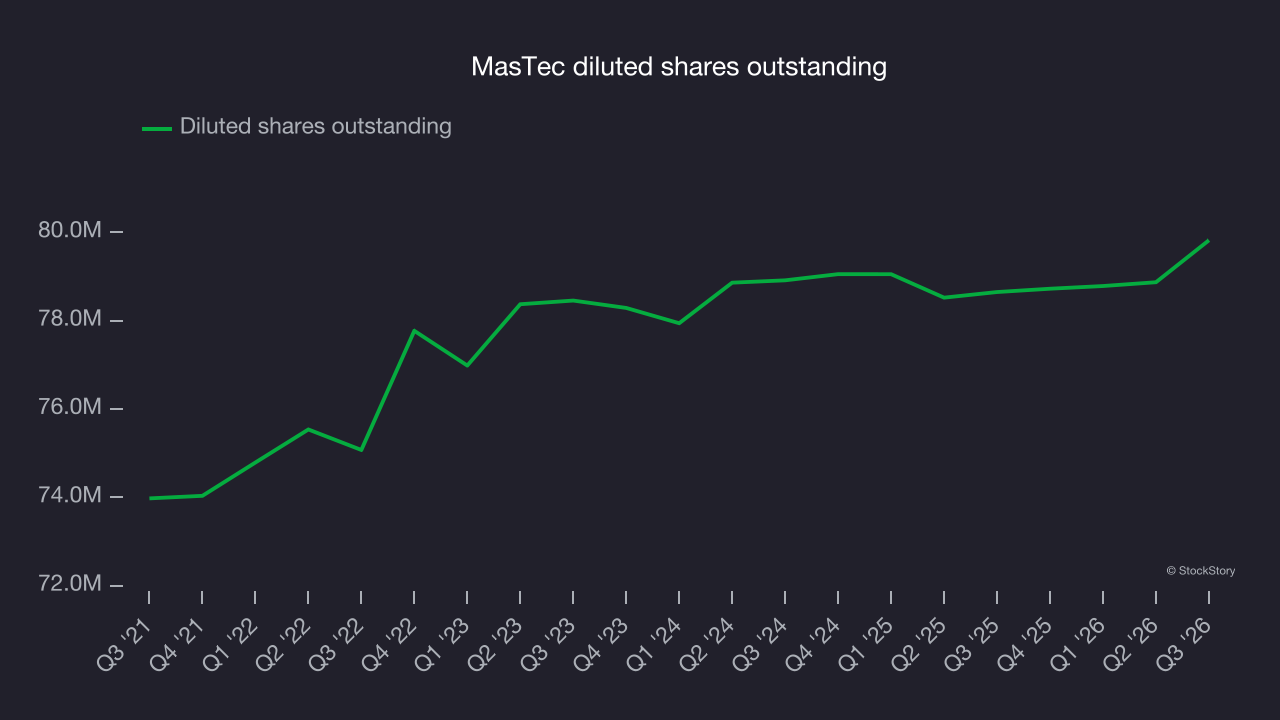
As with revenue, a more recent view of EPS can provide insight into an emerging theme or development for the business.
For MasTec, its two-year annual EPS growth of 66.4% was higher than its five-year trend. This acceleration made it one of the faster-growing industrials companies in recent history.
In Q3, MasTec reported adjusted EPS of $2.96, up from $2.48 in the same quarter last year. This result was close to analysts’ consensus estimates. Over the next 12 months, Wall Street expects MasTec’s full-year EPS to grow 35.6% from $8.64 to $11.71, according to S&P.
Key takeaways from MasTec’s Q3 results
MasTec’s quarter had some key positives: Revenue came in well above analysts’ consensus estimates, and EBITDA also topped Wall Street’s estimates. However, full-year EBITDA guidance fell slightly short of expectations. The market seemed to be hoping for more, with shares edging lower 1.1% to $172.88 immediately after the release.
Considering MasTec at its current price? If you’re making that decision, you should consider the bigger picture of valuation, business quality and the latest earnings. Read our full research report for more on these factors (it’s free).