Over the past six months, Shift4’s stock price fell to $38.75. Shareholders have lost 14.1% of their capital, which is disappointing considering the S&P 500 has climbed by 8.2%. This was partly due to its softer quarterly results and might have investors contemplating their next move.
Given the weaker price action, is now the time to buy FOUR? Find out in our full research report, it’s free.
Why are we positive on Shift4?
Starting as a payment gateway provider in 1999 and now processing over $200 billion in annual payment volume, Shift4 Payments (NYSE: FOUR) provides integrated payment processing solutions and software that help businesses accept and manage transactions across in-store, online, and mobile channels.
1. Skyrocketing revenue shows strong momentum
A company’s long-term performance is an indicator of its overall quality. Any business can put up a good quarter or two, but the best consistently grow over the long haul.
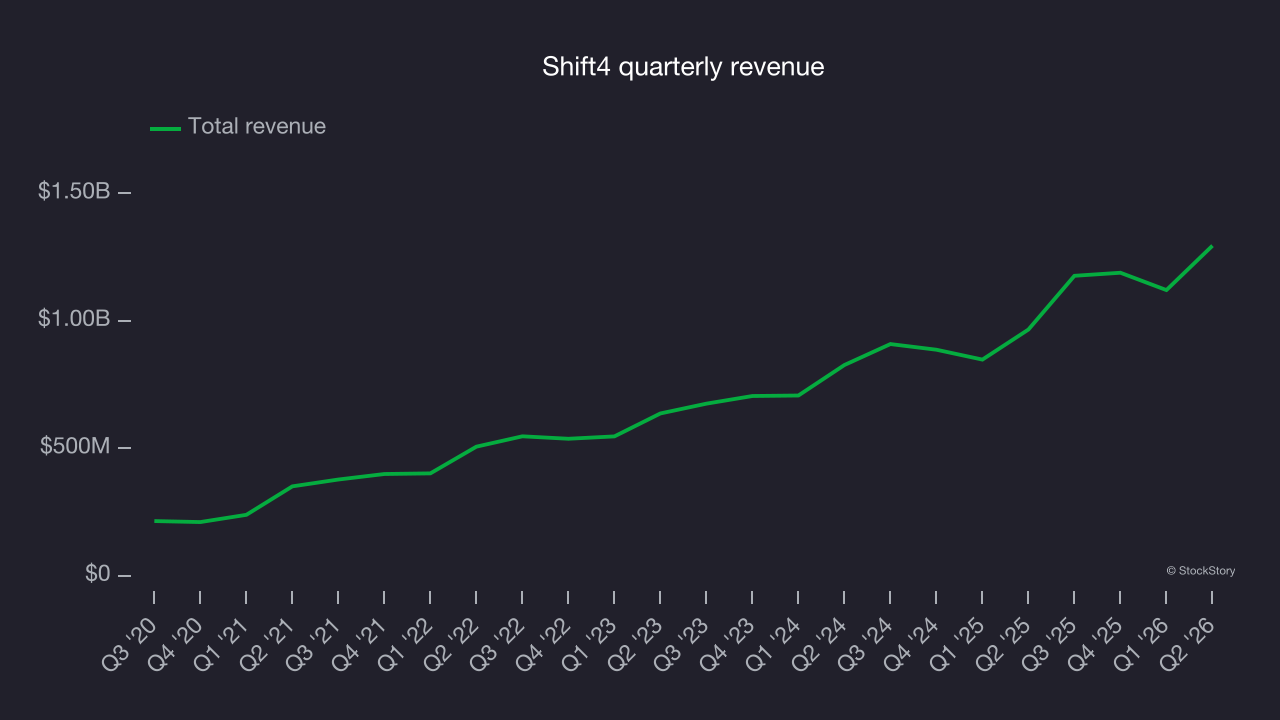
Over the last five years, Shift4 grew its revenue at an incredible 36.3% compounded annual growth rate. Its growth beat the average financials company and shows its offerings resonate with customers.
2. Outstanding long-term EPS growth
Analyzing the long-term change in earnings per share (EPS) shows whether a company’s incremental sales were profitable — for example, revenue could be inflated through excessive spending on advertising and promotions.
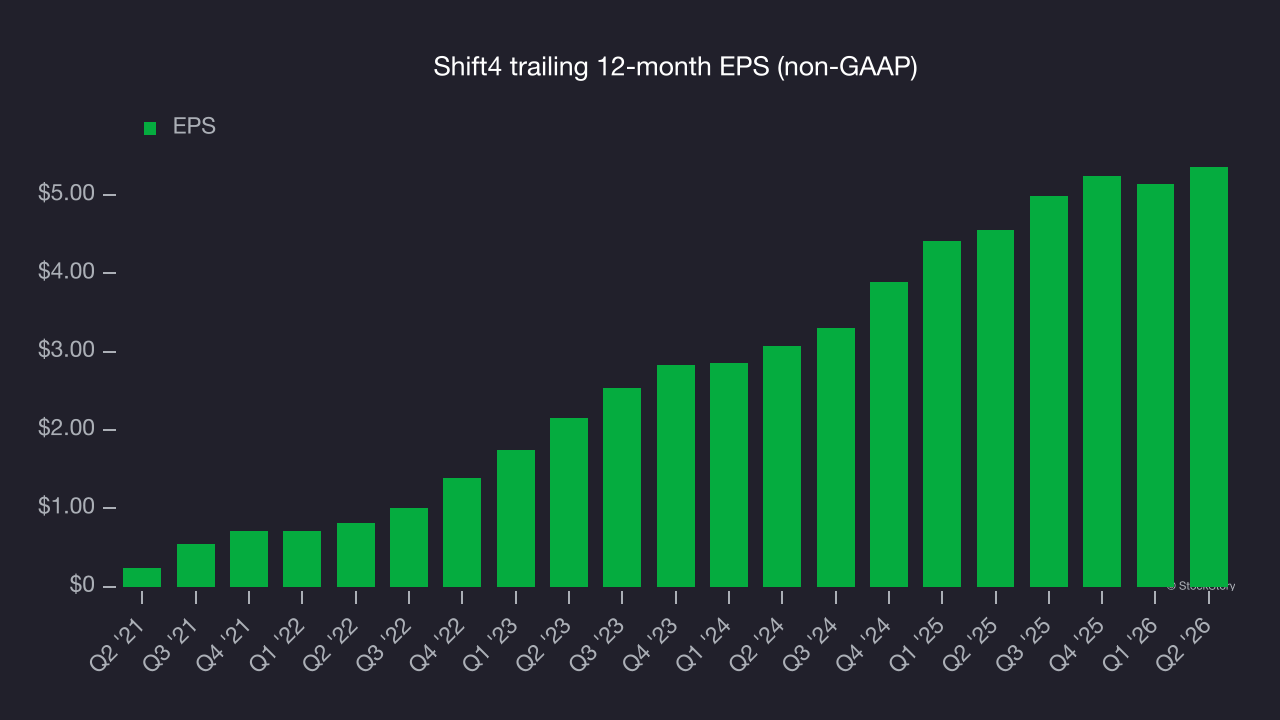
Shift4’s EPS grew at 87.1% compounded annual growth rate over the last five years, higher than its 36.3% annualized revenue growth. This tells us the company became more profitable on a per-share basis as it expanded.
3. Stellar ROE showcases lucrative growth opportunities
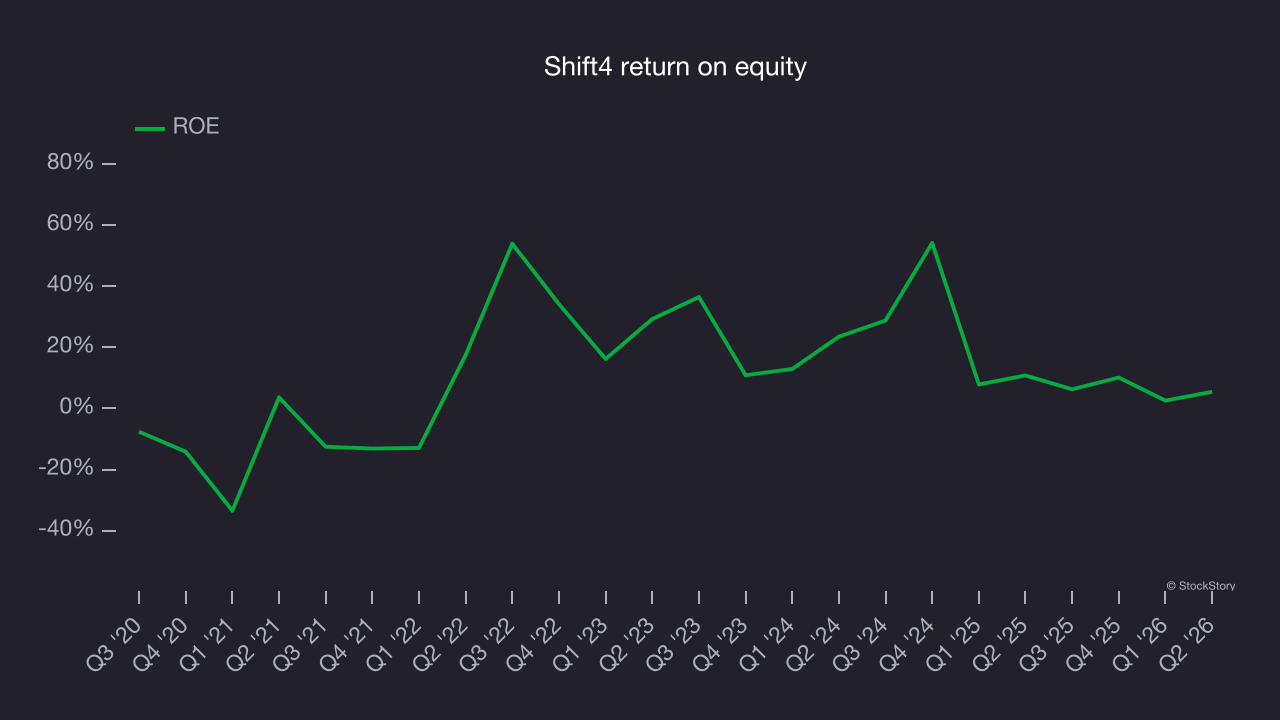
Return on equity (ROE) reveals the profit generated per dollar of shareholder equity, which represents a key source of financial firm funding. Financial firms maintaining elevated ROE levels tend to accelerate wealth creation for shareholders via earnings retention, buybacks, and distributions.
Over the last five years, Shift4 has averaged an ROE of 16.1%, impressive for a company operating in a sector where the average shakes out around 10% and those putting up 25%+ are greatly admired. This shows Shift4 has a strong competitive moat.
Final judgment
These are just a few reasons why Shift4 is one of the best financials companies out there. With the recent decline, the stock trades at 6.9× forward P/E (or $38.75 per share). Is now the right time to buy? See for yourself in our full research report, it’s free.
High-quality stocks for all market conditions
ONE MORE THING: Top 5 Growth Stocks. The biggest stock winners almost always had one thing in common before they ran. Revenue growing like crazy. Meta. CrowdStrike. Broadcom. Our AI flagged all three. They returned 315%, 314%, and 455%, respectively.
Find out which 5 stocks it’s flagging this month — FREE. Get Our Top 5 Growth Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Exlservice (+271% between June 2020 and June 2025). Find your next big winner with StockStory today.