
Financial technology company Enova International (NYSE: ENVA) reported Q3 2026 results topping the market’s revenue expectations, with sales up 25.7% year on year to $1.01 billion. Its non-GAAP profit of $4.48 per share was 1.8% above analysts’ consensus estimates.
Is now the time to buy Enova? Find out by accessing our full research report, it’s free.
Enova (ENVA) Q3 2026 highlights:
- Revenue: $1.01 billion vs analyst estimates of $1.00 billion (25.7% year-on-year growth, 0.7% beat)
- Pre-tax Profit: $142.8 million (14.2% margin)
- Adjusted EPS: $4.48 vs analyst estimates of $4.40 (1.8% beat)
- Market Capitalization: $4.48 billion
"We're pleased to deliver another quarter of strong financial results, driven by healthy demand and stable credit, as consolidated originations, receivables, revenue and adjusted EPS all grew 25% or more year-over-year," said Steve Cunningham, Enova's CEO. "We've built a high growth, highly profitable and resilient business at Enova serving large, fragmented markets with diversified products powered by our online-only business model, world-class technology and risk management, talented team and competitive funding capabilities. Our future is bright, and our focused growth strategy has us well positioned to continue delivering on our commitment to driving long-term shareholder value while meeting our mission of helping hardworking people get access to fast, trustworthy credit."
Company overview
Pioneering online lending since 2004 with a massive database of over 65 terabytes of customer behavior data, Enova International (NYSE: ENVA) provides online financial services including installment loans and lines of credit to non-prime consumers and small businesses in the United States and Brazil.
Revenue growth
Reviewing a company’s long-term sales performance reveals insights into its quality. Any business can experience short-term success, but top-performing ones enjoy sustained growth for years. Over the last five years, Enova grew its revenue at an incredible 26.9% compounded annual growth rate. Its growth beat the average financials company and shows its offerings resonate with customers.
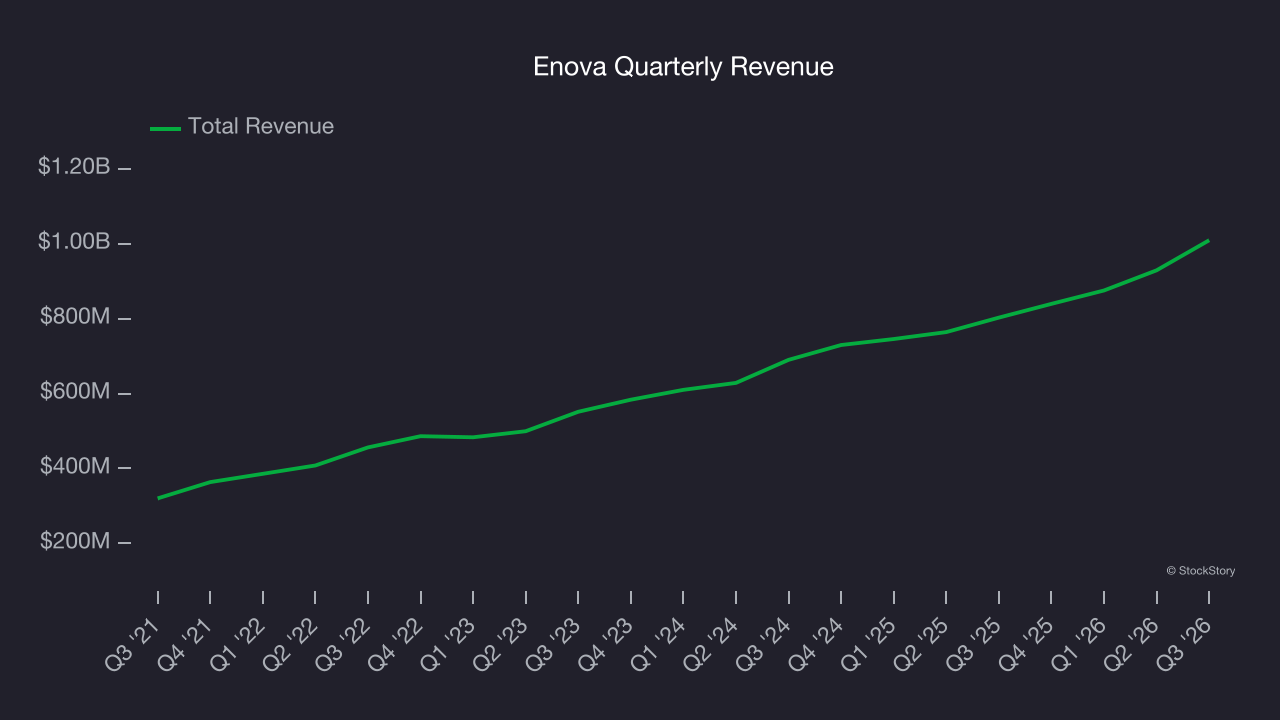
Long-term growth is the most important, but within financials, a half-decade historical view may miss recent interest rate changes and market returns. Enova’s annualized revenue growth of 20.6% over the last two years is below its five-year trend, but we still think the results suggest healthy demand. 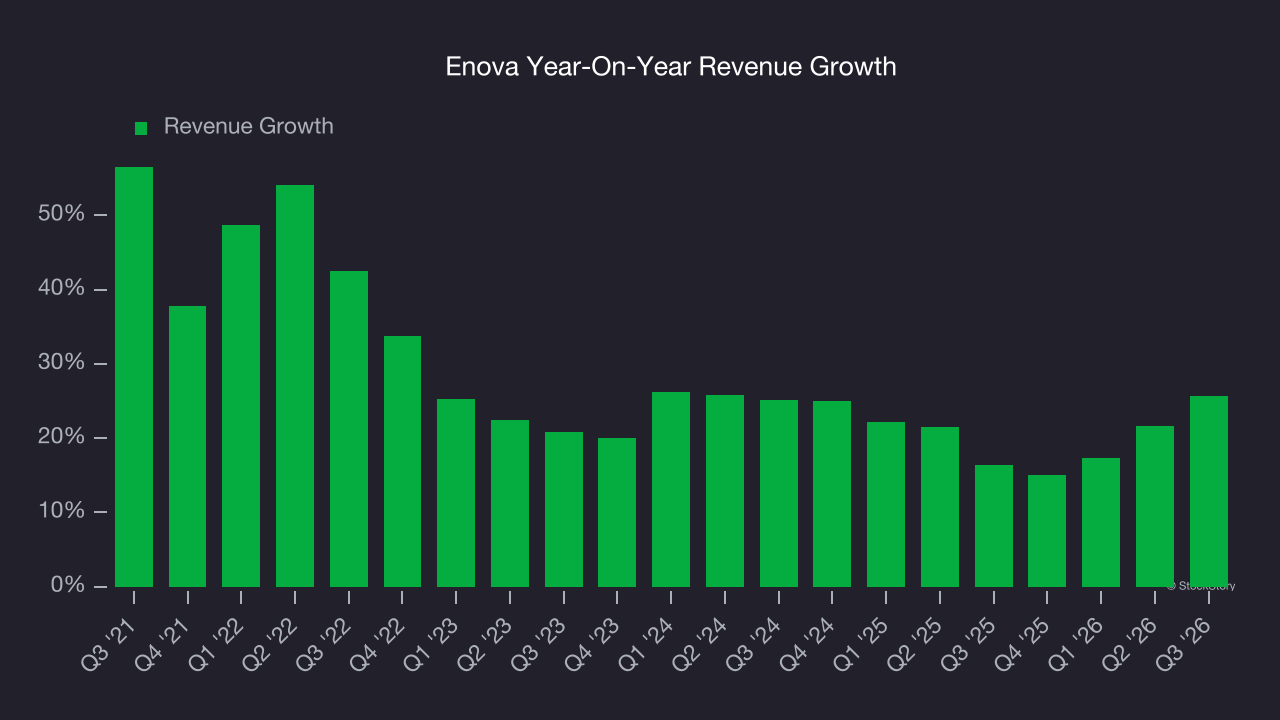
This quarter, Enova reported robust year-on-year revenue growth of 25.7%, and its $1.01 billion of revenue topped Wall Street estimates by 0.7%.
ALSO WORTH WATCHING: Nvidia’s Quiet Partner. Nvidia’s chips cost a hundred grand. The connectors that make them work cost even more. One company makes them all.
Every AI server needs specialized infrastructure the chip companies don’t make. High-speed cables. Power connectors. Thermal sensors. This 90-year-old company built a monopoly on it. The AI boom just started. This stock is still flying under the radar. Claim The Stock Ticker Here for FREE.
Key takeaways from Enova’s Q3 results
It was encouraging to see Enova beat analysts’ EBITDA expectations this quarter. Zooming out, we think this was a decent quarter. The stock remained flat at $177.03 immediately after reporting.
So should you invest in Enova right now? When making that decision, it’s important to consider its valuation, business qualities, as well as what has happened in the latest quarter. We cover that in our actionable full research report which you can read here (it’s free).