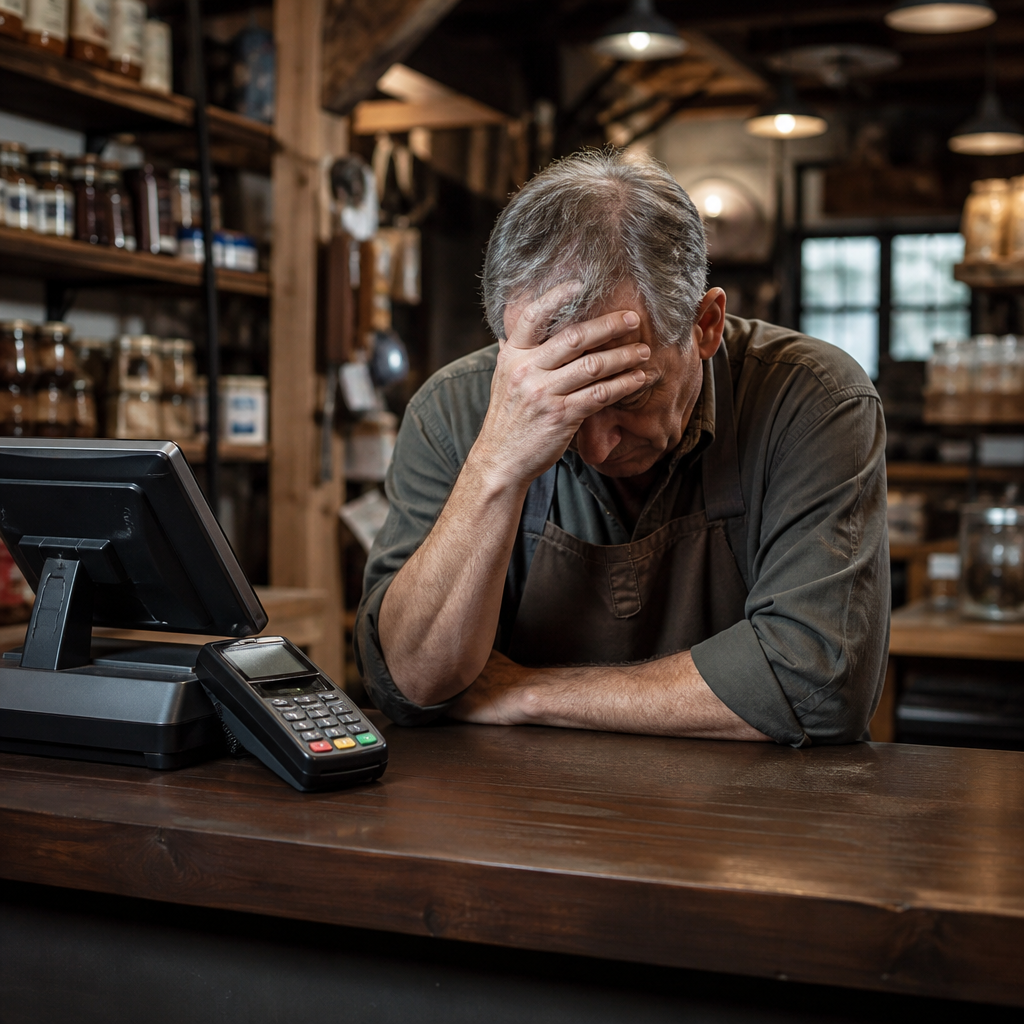
A gun shop in a small Texas town can run clean books for eleven years, never miss a deposit, and still wake up on a Tuesday to an email saying its payment account has been closed. No fraud. No chargeback spike. Just a line in a terms-of-service document that says the processor does not support that category of business. For the owner, it means the card reader at the counter stops working before the morning coffee is finished.
This happens constantly to the kinds of businesses that anchor main streets across the Hill Country and rural Central Texas: firearms dealers, ammunition sellers, gunsmiths, CBD shops, sweepstakes and promotional operators, nutraceutical sellers, and a long tail of trades that mainstream platforms have decided are more trouble than they are worth. Understanding why it happens, and what a durable setup looks like, is worth more to these owners than any marketing advice.
“High-risk” is a banking label, not a judgment about you
The phrase gets taken personally, and it should not be. When an acquiring bank calls a merchant category high-risk, it is making a narrow underwriting statement: this type of business carries above-average exposure to chargebacks, regulatory change, reputational scrutiny, or future liability that outlives the transaction. A firearms retailer may have a near-perfect dispute history and still fall into that bucket because of interstate shipping rules and the political weather around the product. A CBD retailer lands there because the legal status of hemp-derived products has shifted repeatedly and varies by state. A sweepstakes operator lands there because prize-based promotions sit close to categories banks treat with extreme caution.
None of that is about whether the owner is honest. It is about where a bank’s risk committee is willing to sit. University treasury guidance on how merchant accounts and credit card acceptance actually work lays out the same underlying mechanics any small business is subject to: a merchant account is a line of credit extended against future sales, and the party extending it decides what exposure it will tolerate. Once you see it as credit rather than a utility, the sudden shutdowns make more sense.
Why aggregators are the wrong tool for these categories
Stripe, Square, and PayPal are extraordinary products for a coffee shop or a freelance designer. They work because they skip traditional underwriting: you sign up in four minutes and start taking cards under a shared merchant identification number alongside millions of other sellers. That speed is the whole trade-off. Because thousands of businesses share one risk pool, the platform protects the pool by writing broad prohibitions into its policies and enforcing them automatically.
The practical consequences for a specialty retailer are brutal:
- Termination arrives without a hearing. The decision is a policy match, not a dispute you can argue.
- Funds can be held. Reserves of 90 to 180 days on settled transactions are common in platform terms, which is devastating for a business carrying inventory.
- Reinstatement is rare. Once a category flag is on the account, the same flag follows new applications tied to the same owner and tax ID.
- There is no underwriter to call. The relationship was built to avoid human review, so there is nobody to explain your FFL compliance record to.
Owners frequently try to work around this by describing the business vaguely at signup: a gun shop files as “sporting goods,” a CBD retailer as “wellness.” That is the worst available option. Miscoding a merchant category is a terms violation that turns an ordinary closure into a listing on the MATCH file, the card networks’ shared database of terminated merchants. A MATCH listing typically sits there for five years and makes legitimate underwriting far harder.
What a stable setup actually looks like
The alternative is a dedicated merchant account: your own MID, underwritten by an acquiring bank that knowingly accepts your category. It takes longer to open, usually days rather than minutes, and it asks for more paperwork. In exchange you get a relationship with a bank that already knows what you sell and will not be surprised by it later.
Redundancy at the processing layer
Established high-risk merchants rarely run on a single account. Load balancing across multiple MIDs spreads volume so that no single account carries a dispute ratio hot enough to trigger a monitoring program, and so that a problem with one bank does not take the register offline. It is the same logic as a second internet circuit or a generator behind the shop: you build the redundancy before you need it, not during the outage.
Chargeback discipline
Card networks watch dispute ratios closely, and the thresholds that trigger remediation programs are low, measured in fractions of a percent of monthly transactions. Keeping ratios down is mostly operational: clear descriptors on statements so customers recognize the charge, saved delivery confirmation, written records of the identity and compliance checks a dealer already performs, and representment filed quickly with that documentation attached. Processors who specialize in these verticals treat dispute defense as part of the service rather than a self-service web form.
Pricing you can read
High-risk accounts cost more than flat-rate aggregators, and the honest framing is that the premium buys stability. What matters is being able to see the components: interchange, assessments, the processor’s margin, gateway fees, and any reserve terms. Ask for the reserve structure in writing before signing, because a rolling reserve is the single line item most likely to strain cash flow.
Where a specialist processor fits
Because the obstacle is underwriting appetite rather than paperwork, the useful providers are the ones that approached these categories deliberately. Specialists such as 2accept build merchant accounts for exactly the businesses mainstream platforms reject or terminate, with dedicated programs for FFL firearms dealers, CBD retailers, and sweepstakes operators, plus gateway integration, chargeback defense, and multi-MID load balancing for merchants that want redundancy from day one. The value of that kind of arrangement is unglamorous and entirely practical: the bank knows what you sell before it says yes, so your category stops being a surprise waiting to surface in a compliance review two years from now.
Practical steps for an owner reviewing their setup
1. Read the acceptable use policy of your current processor and find your product in it. If you cannot find clear permission, assume you are exposed.
2. Check that your merchant category code matches what you actually sell. Correct it proactively rather than waiting for a review.
3. Pull your last twelve months of dispute data. Know your ratio before an underwriter calls it out.
4. Assemble an underwriting file: licenses, processing statements, bank statements, product documentation, and your refund and shipping policies.
5. Open a second account before you need it. A dormant backup MID is cheap insurance against a frozen deposit cycle.
6. Keep an offline fallback, such as a terminal that can run on a cellular connection, so a network problem does not become a closed-for-the-day sign.
The wider local stake
These shops are not abstractions. A gunsmith, a feed-and-outdoor store, a small CBD retailer, and a promotions company running a county fair sweepstakes all employ neighbors and pay local taxes. When one of them loses card acceptance for a month, the loss shows up in payroll and inventory, not in a quarterly report somewhere else. That is part of why community investment work, including the kind supported through the GVTC Foundation’s grants to local organizations, matters alongside the infrastructure itself: durable connectivity and durable banking access are both prerequisites for a rural business to compete with online sellers.
The owners who come through a termination intact are the ones who treated payments as infrastructure rather than a settled question. They knew their dispute ratio, kept their documentation current, held a second account in reserve, and worked with an underwriter who had already said yes to their category with full knowledge of it. That preparation takes a few hours a quarter. The alternative is finding out on a Tuesday morning that the card reader has stopped working and nobody is picking up the phone.