Uniform and facility services provider Cintas (NASDAQ: CTAS) announced better-than-expected revenue in Q3 CY2026, with sales up 10.9% year on year to $3.01 billion. The company expects the full year’s revenue to be around $12.21 billion, close to analysts’ estimates. Its GAAP profit of $1.36 per share was in line with analysts’ consensus estimates.
Is now the time to buy Cintas? Find out by accessing our full research report, it’s free.
Cintas (CTAS) Q3 CY2026 Highlights:
- Revenue: $3.01 billion vs analyst estimates of $2.98 billion (10.9% year-on-year growth, 1% beat)
- EPS (GAAP): $1.36 vs analyst estimates of $1.36 (in line)
- The company slightly lifted its revenue guidance for the full year to $12.21 billion at the midpoint from $12.18 billion
- Operating Margin: 23.6%, in line with the same quarter last year
- Free Cash Flow Margin: 15.4%, up from 11.5% in the same quarter last year
- Market Capitalization: $79.66 billion
Company Overview
Starting as a family business collecting and cleaning shop rags in Cincinnati, Cintas (NASDAQ: CTAS) provides corporate identity uniforms, facility services, and safety products to over one million businesses across North America.
Revenue Growth
A company’s long-term sales performance is one signal of its overall quality. Even a bad business can shine for one or two quarters, but a top-tier one grows for years.
With $11.56 billion in revenue over the past 12 months, Cintas is larger than most business services companies and benefits from economies of scale, enabling it to gain more leverage on its fixed costs than smaller competitors. This also gives it the flexibility to offer lower prices.
As you can see below, Cintas’s 9.7% annualized revenue growth over the last five years was impressive. This is a great starting point for our analysis because it shows Cintas’s demand was higher than many business services companies.
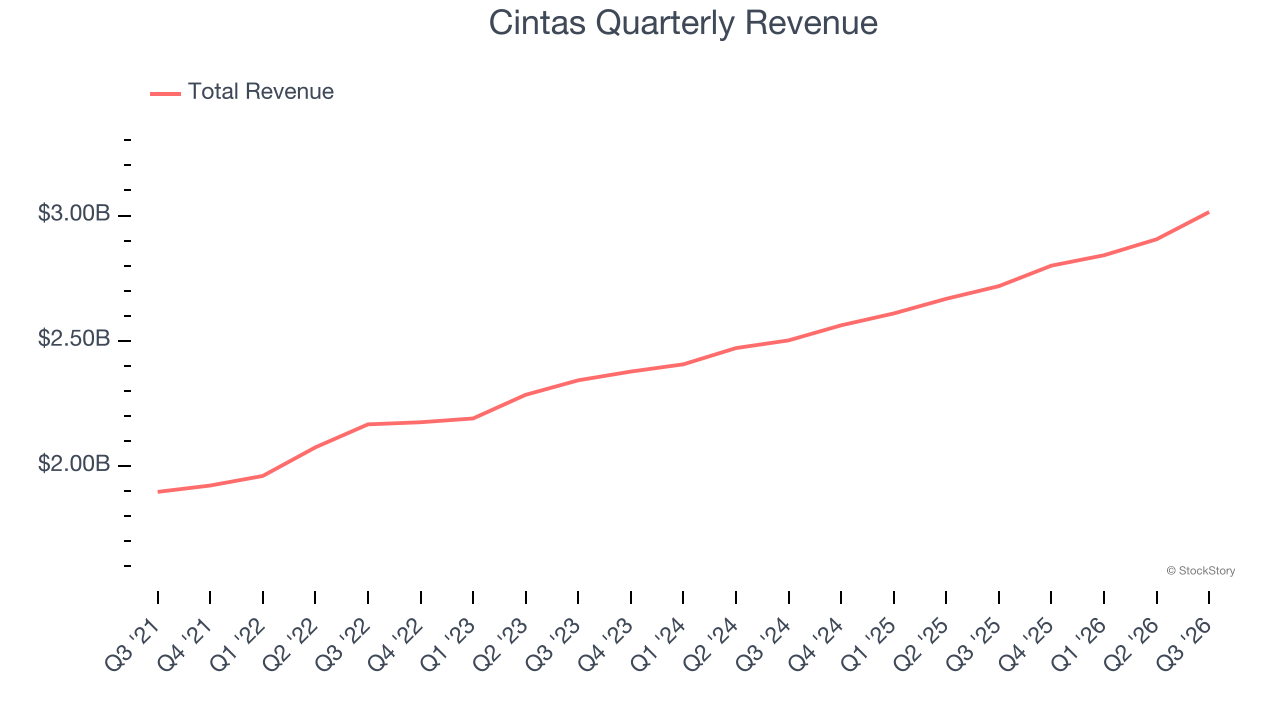
Long-term growth is the most important, but within business services, a half-decade historical view may miss new innovations or demand cycles. Cintas’s annualized revenue growth of 8.9% over the last two years aligns with its five-year trend, suggesting its demand was predictably strong. 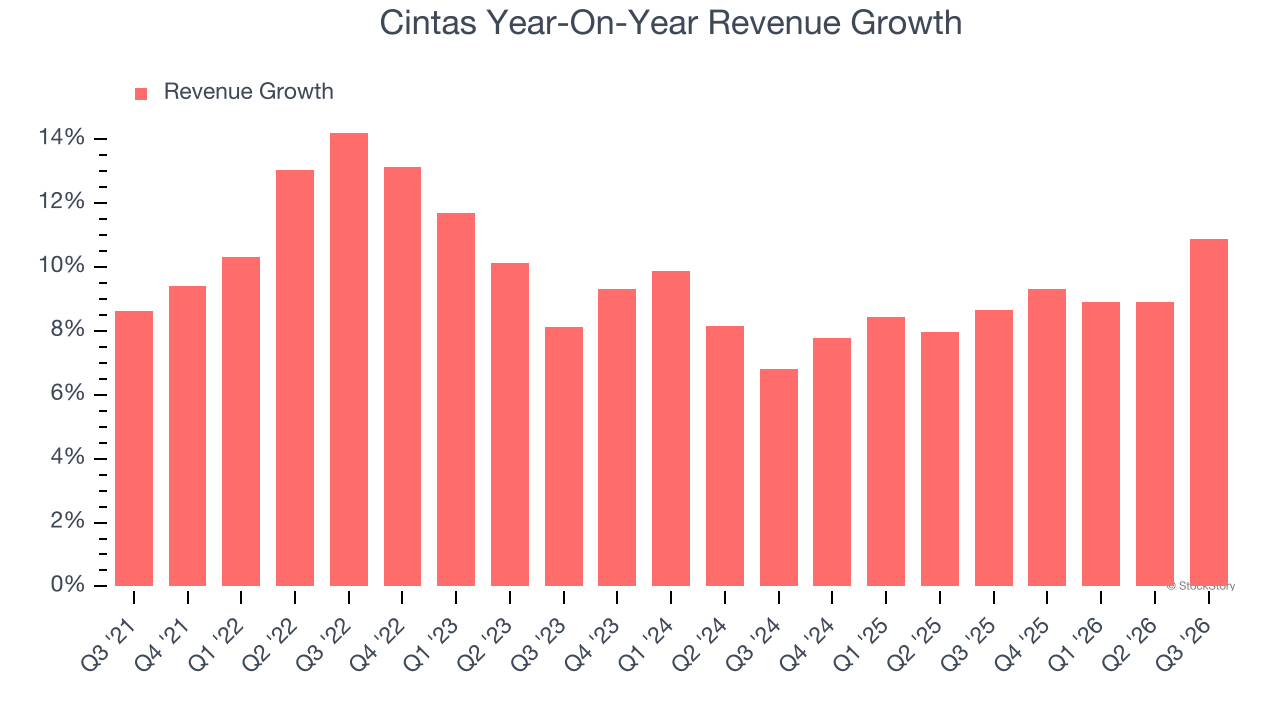
This quarter, Cintas reported year-on-year revenue growth of 10.9%, and its $3.01 billion of revenue exceeded Wall Street’s estimates by 1%.
Looking ahead, sell-side analysts expect revenue to grow 7.6% over the next 12 months, similar to its two-year rate. We still think its growth trajectory is attractive given its scale and indicates the market is baking in success for its products and services.
ONE MORE THING: 3 Hidden Platforms Growing 3X Faster than Amazon, Google, and PayPal. Amazon, Google, and Meta all followed the same playbook: Dominate an ignored market. Build an unbeatable moat. Scale until you’re unstoppable.
These three platforms are running that exact playbook right now. The early investors in Amazon made fortunes. The early investors in these could do the same. Get All 3 Stocks Here for FREE.
Adjusted Operating Margin
Adjusted operating margin is one of the best measures of profitability because it tells us how much money a company takes home after subtracting all core expenses, like marketing and R&D. It also removes various one-time costs to paint a better picture of normalized profits.
Cintas has been a well-oiled machine over the last five years. It demonstrated elite profitability for a business services business, boasting an average adjusted operating margin of 22%.
Looking at the trend in its profitability, Cintas’s adjusted operating margin rose by 4 percentage points over the last five years, as its sales growth gave it operating leverage.
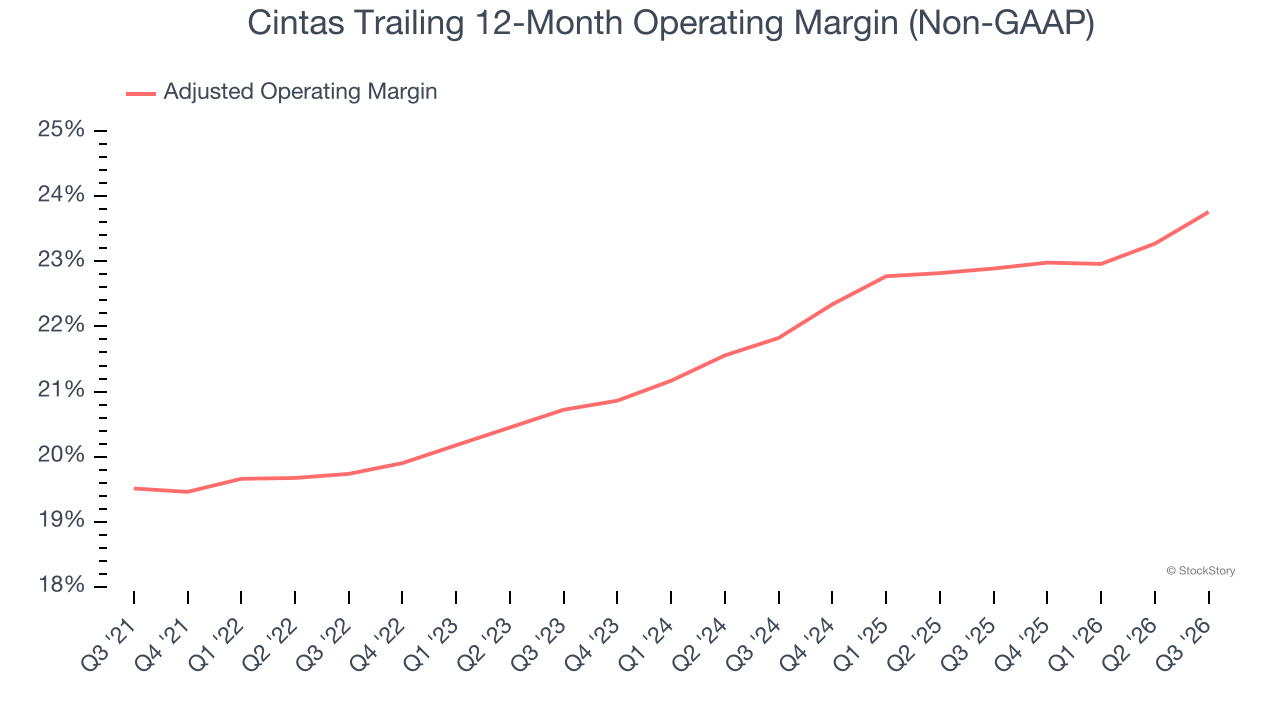
This quarter, Cintas generated an adjusted operating margin profit margin of 24.6%, up 1.9 percentage points year on year. This increase was a welcome development and shows it was more efficient.
Earnings Per Share
Revenue trends explain a company’s historical growth, but the long-term change in earnings per share (EPS) points to the profitability of that growth — for example, a company could inflate its sales through excessive spending on advertising and promotions.
Cintas’s EPS grew at 13.8% compounded annual growth rate over the last five years, higher than its 9.7% annualized revenue growth. This tells us the company became more profitable on a per-share basis as it expanded.
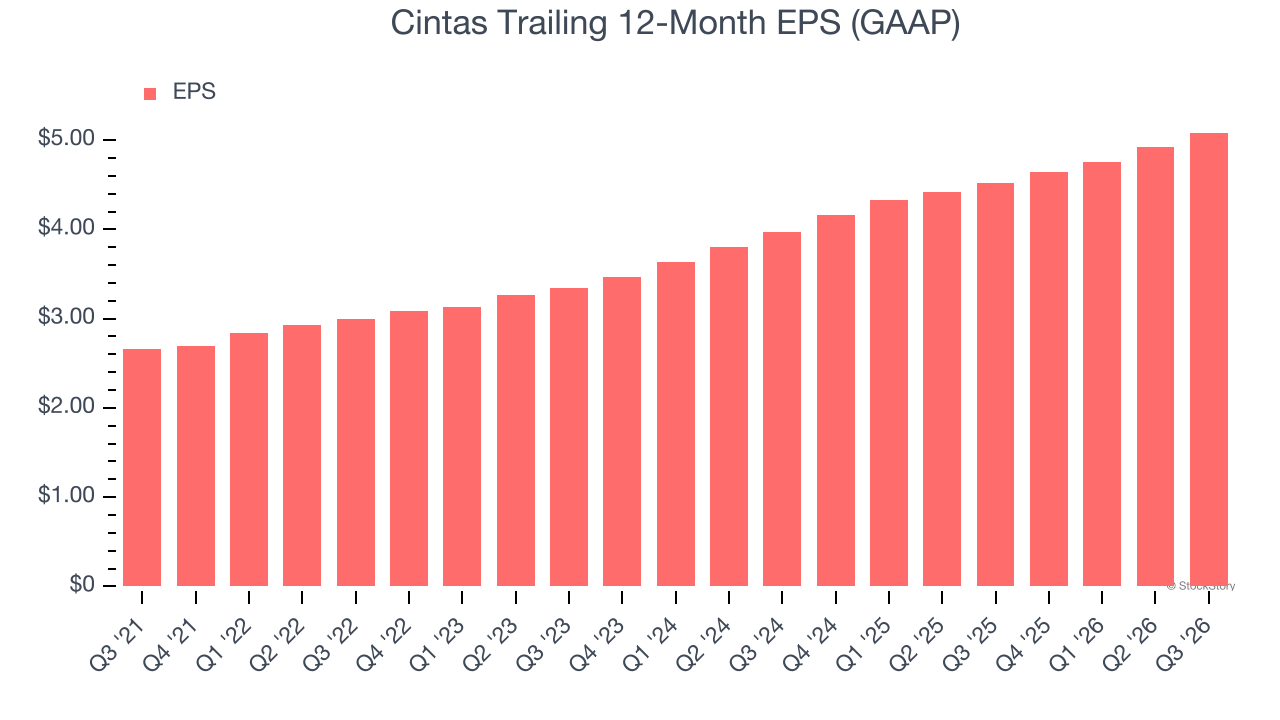
We can take a deeper look into Cintas’s earnings to better understand the drivers of its performance. As we mentioned earlier, Cintas’s adjusted operating margin expanded by 4 percentage points over the last five years. On top of that, its share count shrank by 4.6%. These are positive signs for shareholders because improving profitability and share buybacks turbocharge EPS growth relative to revenue growth. 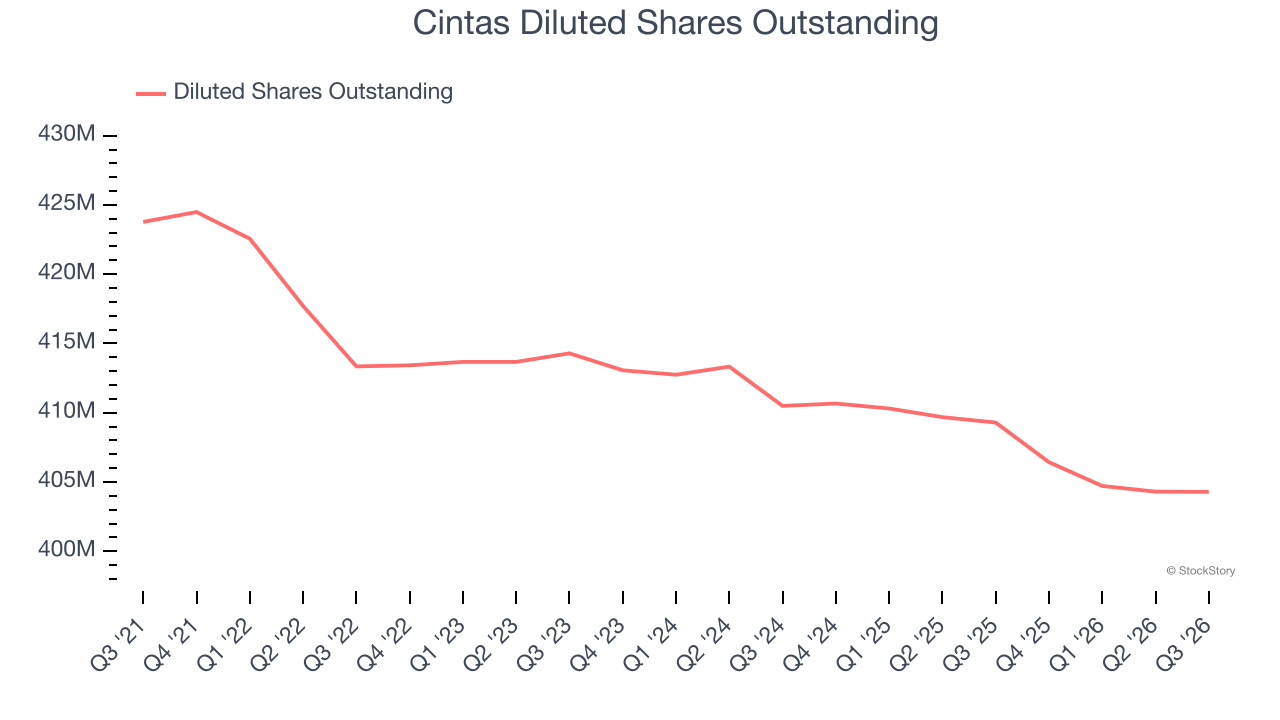
Like with revenue, we analyze EPS over a shorter period to see if we are missing a change in the business.
For Cintas, its two-year annual EPS growth of 13.1% is similar to its five-year trend, implying strong and stable earnings power.
In Q3, Cintas reported EPS of $1.36, up from $1.20 in the same quarter last year. This print was close to analysts’ estimates. Over the next 12 months, Wall Street expects Cintas’s full-year EPS to grow 11.7% from $5.08 to $5.68.
Key Takeaways from Cintas’s Q3 Results
It was good to see Cintas narrowly top analysts’ revenue expectations this quarter. Zooming out, we think this was a decent quarter. The market seemed to be hoping for more, and the stock traded down 1.4% to $196.09 immediately following the results.
Big picture, is Cintas a buy here and now? If you’re making that decision, you should consider the bigger picture of valuation, business qualities, as well as the latest earnings. We cover that in our actionable full research report which you can read here (it’s free).