
Over the last six months, BrightView’s shares have sunk to $10.66, producing a disappointing 9.3% loss - a stark contrast to the S&P 500’s 16.2% gain. This was partly due to its softer quarterly results and might have investors contemplating their next move.
Is there a buying opportunity in BrightView, or does it present a risk to your portfolio? See what our analysts have to say in our full research report, it’s free.
Why Do We Think BrightView Will Underperform?
Even though the stock has become cheaper, we’re cautious about BrightView. Here are three reasons you should be careful with BV, plus one stock we’d rather own.
1. Long-Term Revenue Growth Disappoints
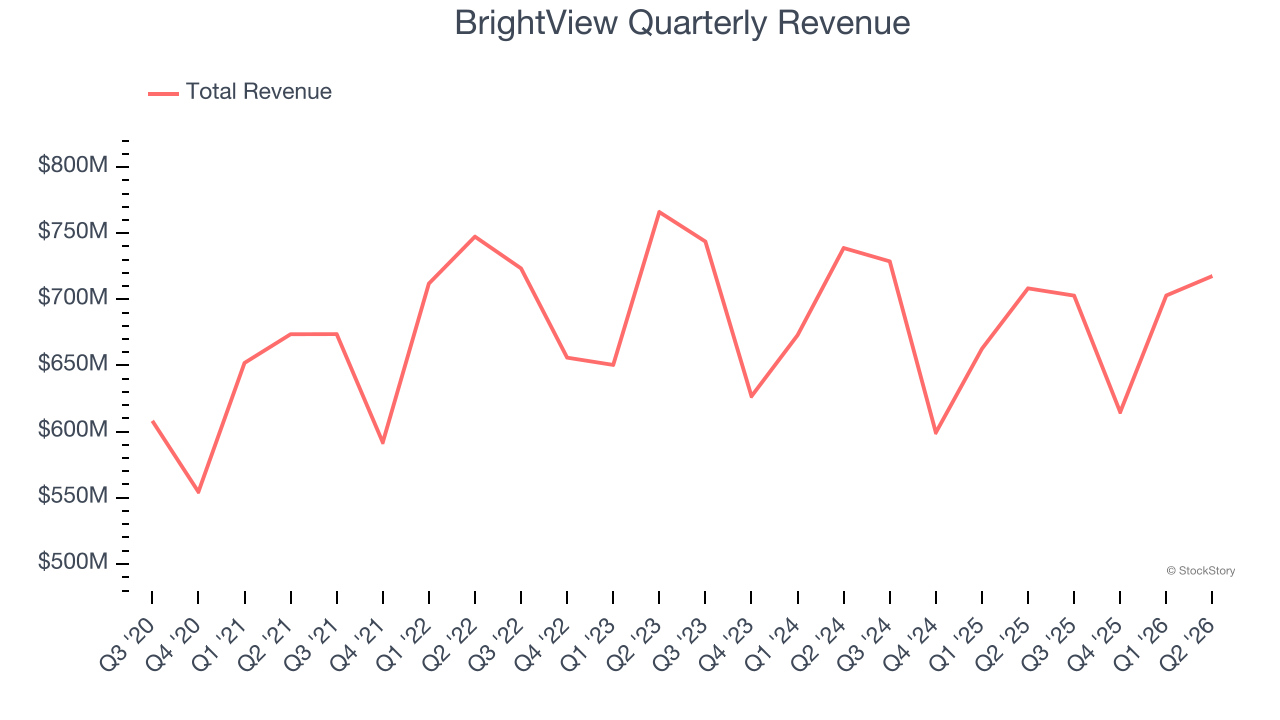
A company’s long-term sales performance is one signal of its overall quality. Any business can have short-term success, but a top-tier one grows for years. Over the last five years, BrightView grew its sales at a sluggish 1.9% compounded annual growth rate. This was below our standards.
2. EPS Trending Down
We track the long-term change in earnings per share (EPS) because it highlights whether a company’s growth is profitable.
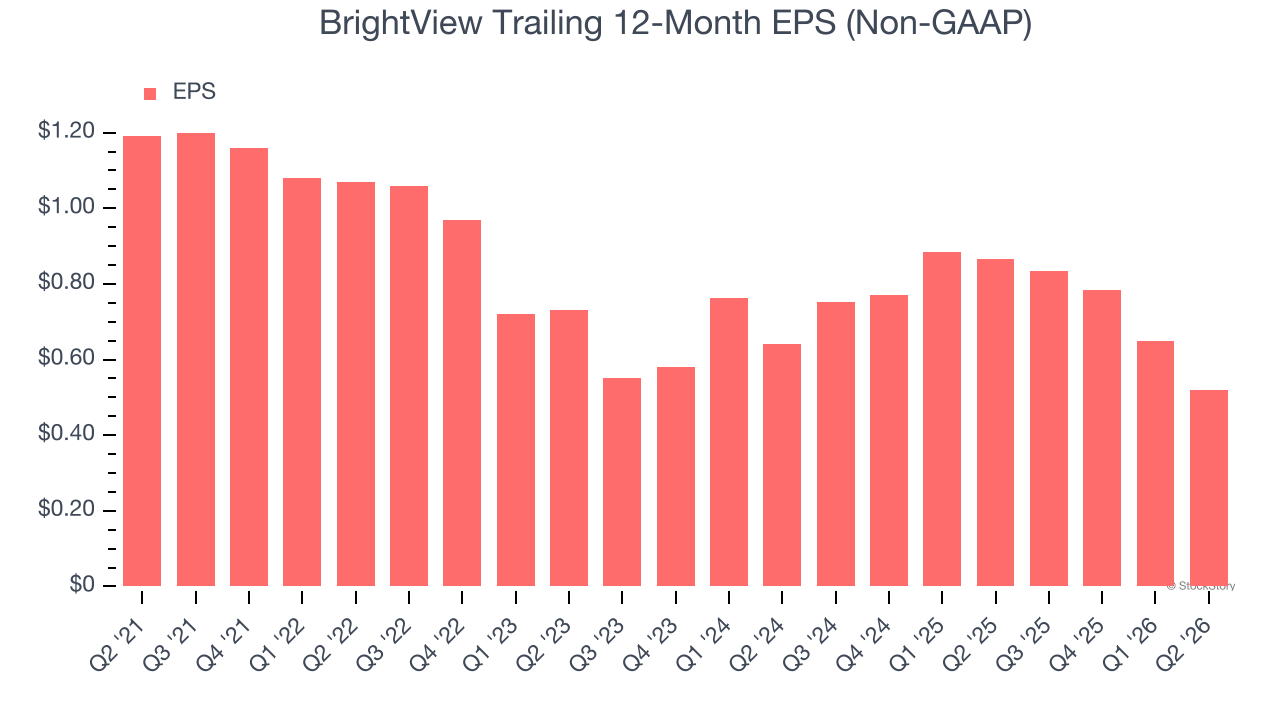
Sadly for BrightView, its EPS declined by 15.3% annually over the last five years while its revenue grew by 1.9%. This tells us the company became less profitable on a per-share basis as it expanded.
3. Previous Growth Initiatives Haven’t Impressed
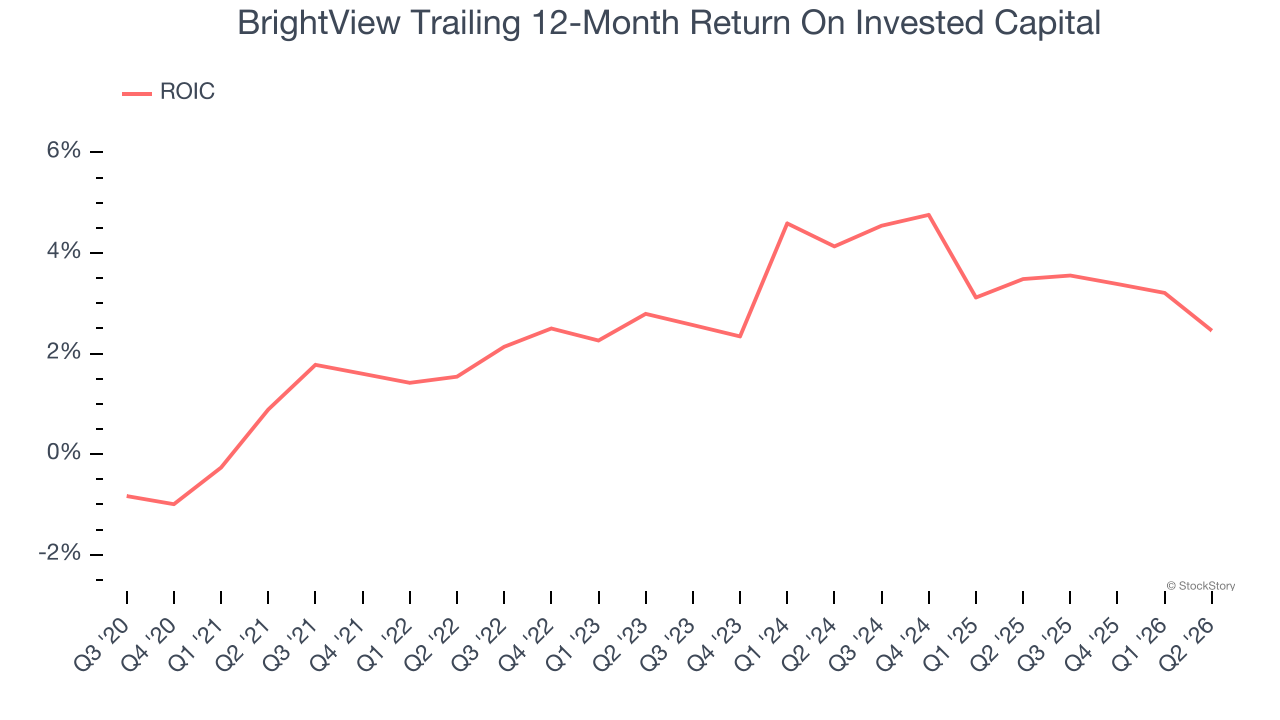
Growth gives us insight into a company’s long-term potential, but how capital-efficient was that growth? A company’s ROIC explains this by showing how much operating profit it makes compared to the money it has raised (debt and equity).
BrightView historically did a mediocre job investing in profitable growth initiatives. Its five-year average ROIC was 2.9%, lower than the typical cost of capital (how much it costs to raise money) for industrials companies.
Final Judgment
BrightView doesn’t pass our quality test. After the recent drawdown, the stock trades at 18.6× forward P/E (or $10.66 per share). This valuation tells us a lot of optimism is priced in - you can find more timely opportunities elsewhere. Let us point you toward one of our top software and edge computing picks.
High-Quality Stocks for All Market Conditions
ONE MORE THING: Top 5 Growth Stocks. The biggest stock winners almost always had one thing in common before they ran. Revenue growing like crazy. Meta. CrowdStrike. Broadcom. Our AI flagged all three. They returned 315%, 314%, and 455%, respectively.
Find out which 5 stocks it’s flagging this month — FREE. Get Our Top 5 Growth Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Tecnoglass (+1,552% between June 2020 and June 2025). Find your next big winner with StockStory today.