When Wall Street turns bearish on a stock, it’s worth paying attention. These calls stand out because analysts rarely issue grim ratings on companies for fear their firms will lose out in other business lines such as M&A advisory.
Accurately determining a company’s long-term prospects isn’t easy, especially when sentiment is weak. That’s where StockStory comes in - to help you find attractive investment candidates backed by unbiased research. Keeping that in mind, here is one stock poised to prove Wall Street wrong and two where the outlook is warranted.
Two Stocks to Sell:
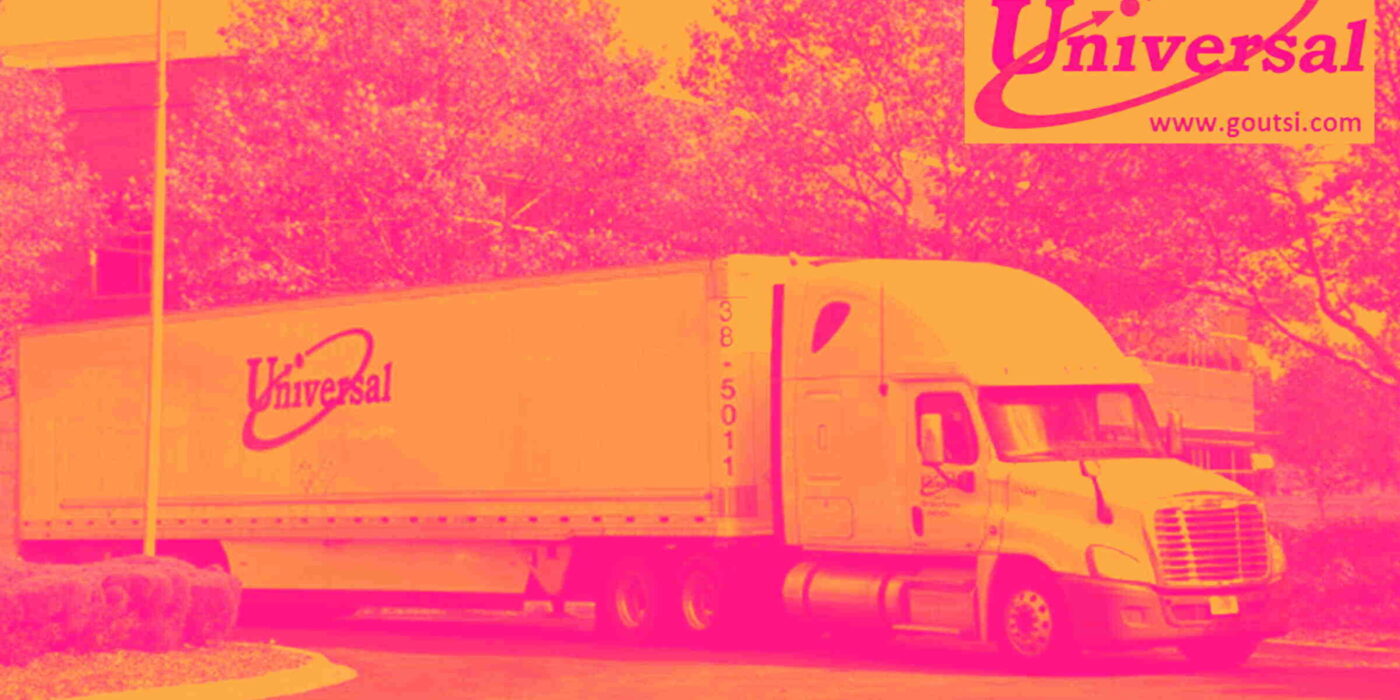
Universal Logistics (ULH)
Consensus Price Target: $16 (-9.2% implied return)
Founded in 1932, Universal Logistics (NASDAQ: ULH) is a provider of customized transportation and logistics solutions operating throughout the United States and in Mexico, Canada, and Colombia.
Why Should You Sell ULH?
- Sales were flat over the last five years, indicating it’s failed to expand this cycle
- Shrinking returns on capital suggest that increasing competition is eating into the company’s profitability
Universal Logistics is trading at $17.62 per share, or 18.6x forward P/E. To fully understand why you should be careful with ULH, check out our full research report (it’s free).
Main Street Capital (MAIN)
Consensus Price Target: $60.33 (8.9% implied return)
With a focus on building long-term partnerships rather than quick transactions, Main Street Capital (NYSE: MAIN) is a business development company that provides long-term debt and equity capital to lower middle market and middle market companies.
Why Is MAIN Not Exciting?
- 5.5% annual revenue growth over the last two years was slower than its financials peers
- Incremental sales over the last two years were much less profitable as its earnings per share fell by 2.7% annually while its revenue grew
- Muted 6.7% annual tangible book value per share growth over the last two years shows its capital generation lagged behind its financials peers
Main Street Capital’s stock price of $55.41 implies a valuation ratio of 14.5x forward P/E. Check out our free in-depth research report to learn more about why MAIN doesn’t pass our bar.
One Stock to Buy:
Natera (NTRA)
Consensus Price Target: $366.07 (-14.3% implied return)
Founded in 2003 as Gene Security Network before rebranding in 2012, Natera (NASDAQ: NTRA) develops and commercializes genetic tests for prenatal screening, cancer detection, and organ transplant monitoring using its proprietary cell-free DNA technology.
Why Is NTRA a Top Pick?
- Average unit sales growth of 19.3% over the past two years reflects steady demand for its products
- Earnings per share have massively outperformed its peers over the last five years, increasing by 18.2% annually
- Free cash flow margin is now positive, showing the company is at an important crossroads
At $427.40 per share, Natera trades at 18.7x forward price-to-sales. Is now a good time to buy? See for yourself in our full research report, it’s free.
High-Quality Stocks for All Market Conditions
ONE MORE THING: Top 5 Growth Stocks. The biggest stock winners almost always had one thing in common before they ran. Revenue growing like crazy. Meta. CrowdStrike. Broadcom. Our AI flagged all three. They returned 315%, 314%, and 455%, respectively.
Find out which 5 stocks it’s flagging this month — FREE. Get Our Top 5 Growth Stocks for Free HERE.
Stocks that made our list in 2020 include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Comfort Systems (+1,154% between June 2020 and June 2025). Find your next big winner with StockStory today.