
Leading data storage manufacturer Western Digital (NASDAQ: WDC) reported calendar Q3 2026 (fiscal Q1 2027) results topping the market’s revenue expectations, with sales up 55.5% year on year to $4.38 billion. On top of that, next quarter’s revenue guidance ($5.1 billion) was surprisingly good and 11.3% above what analysts were expecting. Its non-GAAP profit of $4.64 per share was 13.3% above analysts’ consensus estimates.
Is now the time to buy Western Digital? Find out by accessing our full research report, it’s free.
Western Digital (WDC) Q3 CY2026 highlights:
- Revenue: $4.38 billion vs analyst estimates of $4.16 billion (55.5% year-on-year growth, 5.2% beat)
- Adjusted EPS: $4.64 vs analyst estimates of $4.10 (13.3% beat)
- Adjusted Operating Income: $2.15 billion vs analyst estimates of $1.92 billion (49.1% margin, 12.3% beat)
- Revenue Guidance for Q4 CY2026 is $5.1 billion, above analyst estimates of $4.58 billion
- Adjusted EPS guidance for Q4 CY2026 is $5.80, above analyst estimates of $4.82
- Operating Margin: 46.7%, up from 28.1% in the same quarter last year
- Free Cash Flow Margin: 31.4%, up from 21.3% in the same quarter last year
- Inventory Days Outstanding: 88, up from 80 in the previous quarter
- Market Capitalization: $141.7 billion
“Fiscal 2027 is off to a strong start, with results exceeding expectations, driven by robust customer demand and disciplined execution. In our fiscal first quarter, revenue grew 55% year over year, non-GAAP gross and operating margins expanded to 58.1% and 49.1%, respectively, resulting in a 161% year-over-year increase in non-GAAP EPS. Reflecting our confidence in the business and our commitment to return capital to shareholders, we are raising our quarterly cash dividend by 17% to $0.175 per share,” said Irving Tan, CEO of WD. “We are executing well through our technology transitions to meet the growing demand for storage. As we deepen our customer relationships, broaden the customer base to new areas of the market, and extend our visibility into future demand, we are building an increasingly durable foundation for long-term value creation.”
Company overview
Founded in 1970 by a Motorola employee, Western Digital (NASDAQ: WDC) is a leading producer of hard disk drives, SSDs and flash memory.
Revenue growth
A company’s long-term sales performance is one signal of its overall quality. Any business can have short-term success, but a top-tier one grows for years. Western Digital’s demand was weak over the last five years as its sales fell at a 4.3% annual rate. This wasn’t a great result, but there are still things to like about Western Digital. Semiconductors are a cyclical industry, and long-term investors should be prepared for periods of high growth followed by periods of revenue contractions.
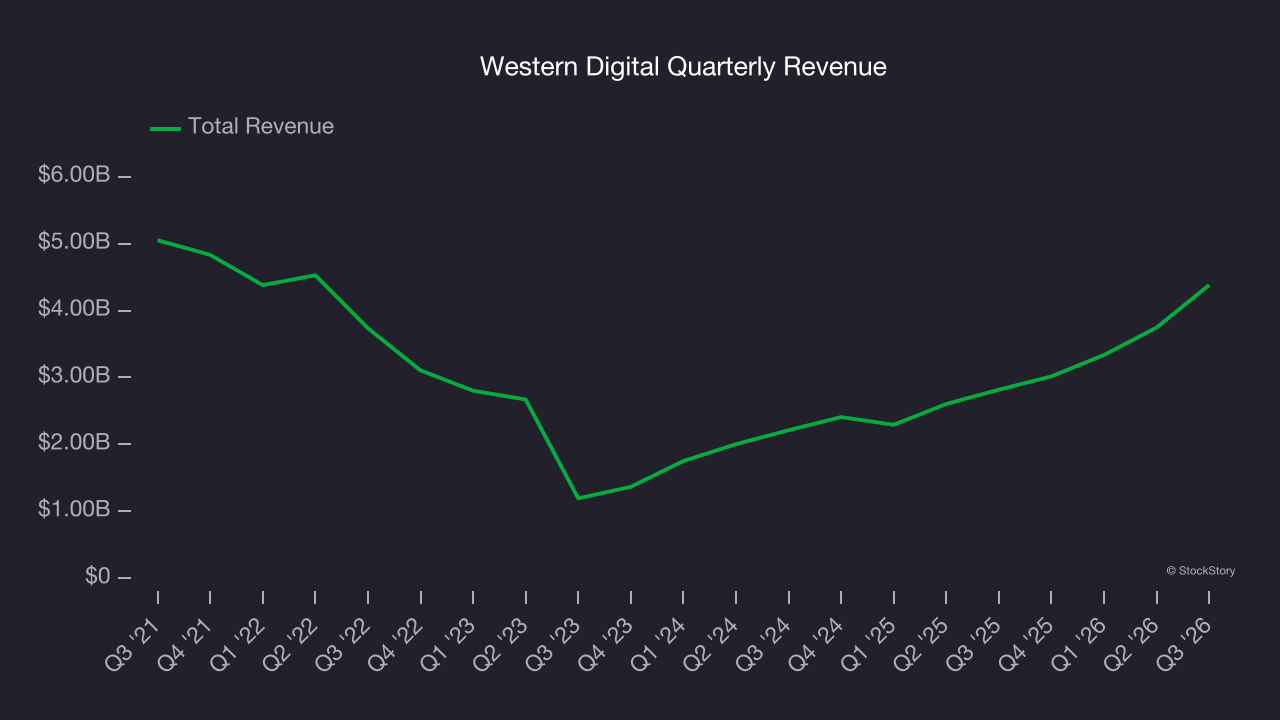
We at StockStory place the most emphasis on long-term growth, but within semiconductors, a half-decade historical view may miss new demand cycles or industry trends like AI. Western Digital’s annualized revenue growth of 40.5% over the last two years is above its five-year trend, suggesting its demand recently accelerated. 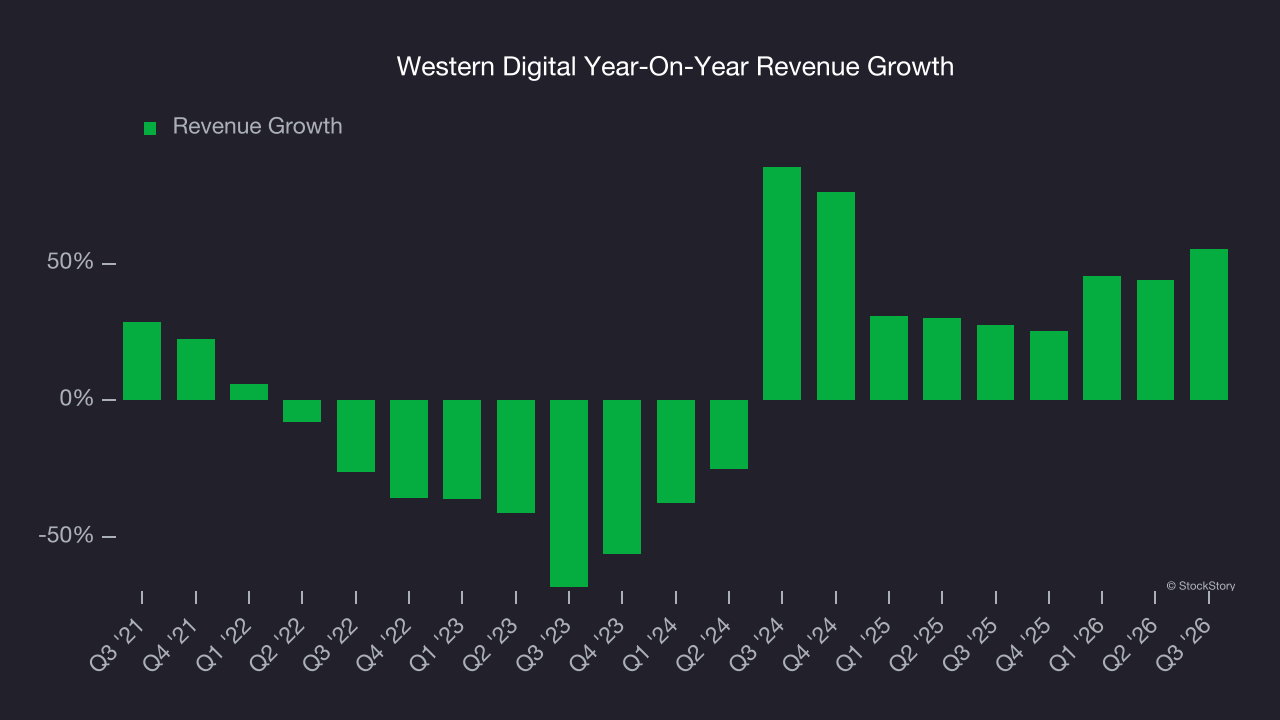
This quarter, Western Digital reported magnificent year-on-year revenue growth of 55.5%, and its $4.38 billion of revenue beat Wall Street’s estimates by 5.2%. Beyond the beat, this marks 9 straight quarters of growth, showing that the current upcycle has had a good run - a typical upcycle usually lasts 8-10 quarters. Company management is currently guiding for a 69% year-on-year increase in sales next quarter.
Looking further ahead, sell-side analysts expect revenue to grow 46.8% over the next 12 months, an improvement versus the last two years. This projection is particularly noteworthy for a company of its scale and suggests its newer products and services will fuel better top-line performance.
WHILE YOU’RE HERE: The Next Palantir? One satellite company captures images of every point on Earth. Every single day. The Pentagon wants it. Hedge funds are using it to beat earnings. You’ve probably never heard of it.
This is what the early days of Palantir looked like before it became a giant. Same playbook. Different technology. If you missed Palantir, you need to see this. Claim The Stock Ticker for Free HERE.
Product demand & outstanding inventory
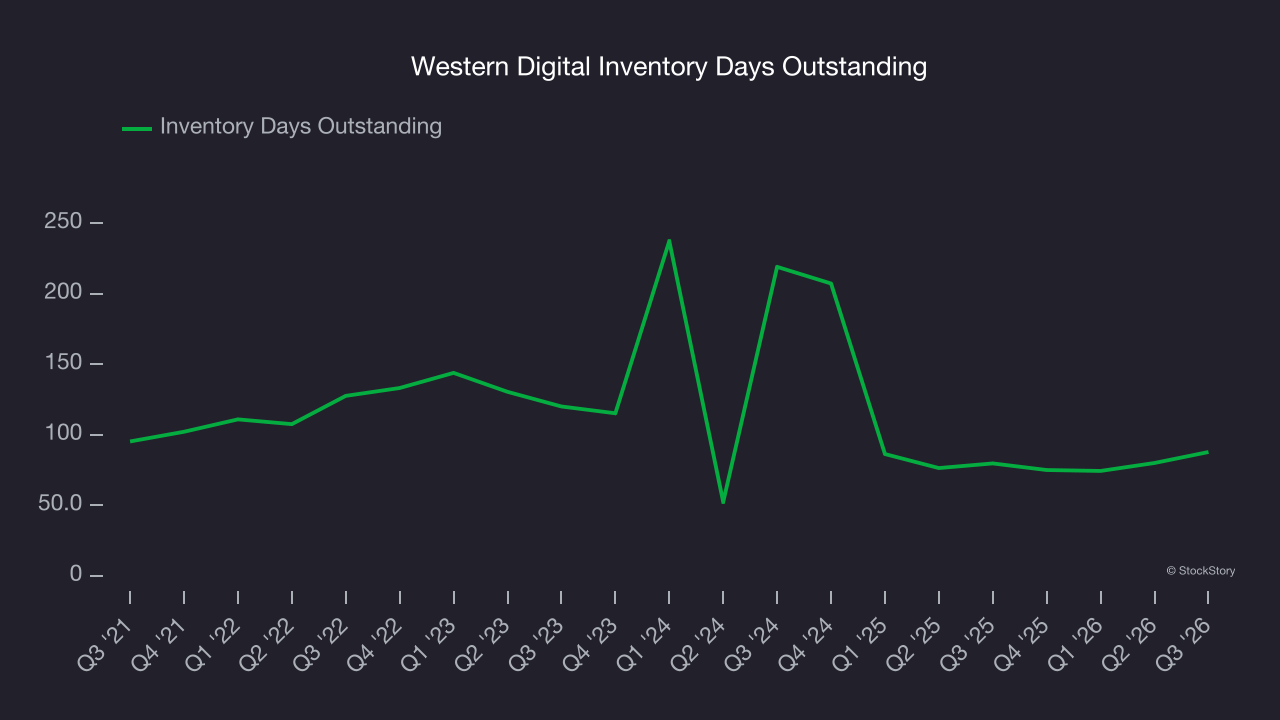
Days Inventory Outstanding (DIO) is an important metric for chipmakers, as it reflects a business’s capital intensity and the cyclical nature of semiconductor supply and demand. In a tight supply environment, inventories tend to be stable, allowing chipmakers to exert pricing power. Steadily increasing DIO can be a warning sign that demand is weak, and if inventories continue to rise, the company may have to downsize production.
This quarter, Western Digital’s DIO came in at 88, which is 31 days below its five-year average. These numbers show that despite the recent increase, there’s no indication of an excessive inventory buildup.
Key takeaways from Western Digital’s Q3 results
It was good to see Western Digital beat analysts’ EPS expectations this quarter. We were also excited its operating income outperformed Wall Street’s estimates by a wide margin. On the other hand, its inventory levels materially increased. Zooming out, we think this was a good print with some key areas of upside. The stock traded up 1.9% to $362.59 immediately after reporting.
Sure, Western Digital had a solid quarter, but if we look at the bigger picture, is this stock a buy? When making that decision, it’s important to consider its valuation, business qualities, as well as what has happened in the latest quarter. We cover that in our actionable full research report which you can read here (it’s free).