Household products company Kimberly-Clark (NASDAQ: KMB) met Wall Street’s revenue expectations in Q3 2026, but revenue was flat year on year at $4.13 billion. Its non-GAAP profit of $1.70 per share was 3% above analysts’ consensus estimates.
For more on Kimberly-Clark, read our free full research report.
Kimberly-Clark (KMB) Q3 2026 highlights:
- Revenue $4.13 billion vs S&P analysts’ consensus estimates of $4.14 billion (flat year on year, in line)
- Adjusted EPS $1.70 vs S&P analysts’ consensus estimates of $1.65 (3% beat)
- Operating margin 12.5%, down from 15% in the same quarter last year
- Free cash flow margin 11.9%, up from 8.9% in the same quarter last year
- Organic revenue fell 1.3% year on year (miss)
- Market capitalization $66.76 billion
Revenue growth
Examining a company’s long-term performance can provide clues about its quality. Any business can have short-term success, but a top-tier one grows for years.
With $16.57 billion in revenue over the past 12 months, Kimberly-Clark is one of the larger consumer staples companies and benefits from a well-known brand that influences purchasing decisions. However, its scale is a double-edged sword because there are only a finite number of major retail partners, placing a ceiling on its growth. For Kimberly-Clark to boost its revenue, it likely needs to adjust its prices, launch new offerings or expand in foreign markets.
Kimberly-Clark struggled to generate demand over the last three years. Its revenue fell by 6.7% annually.
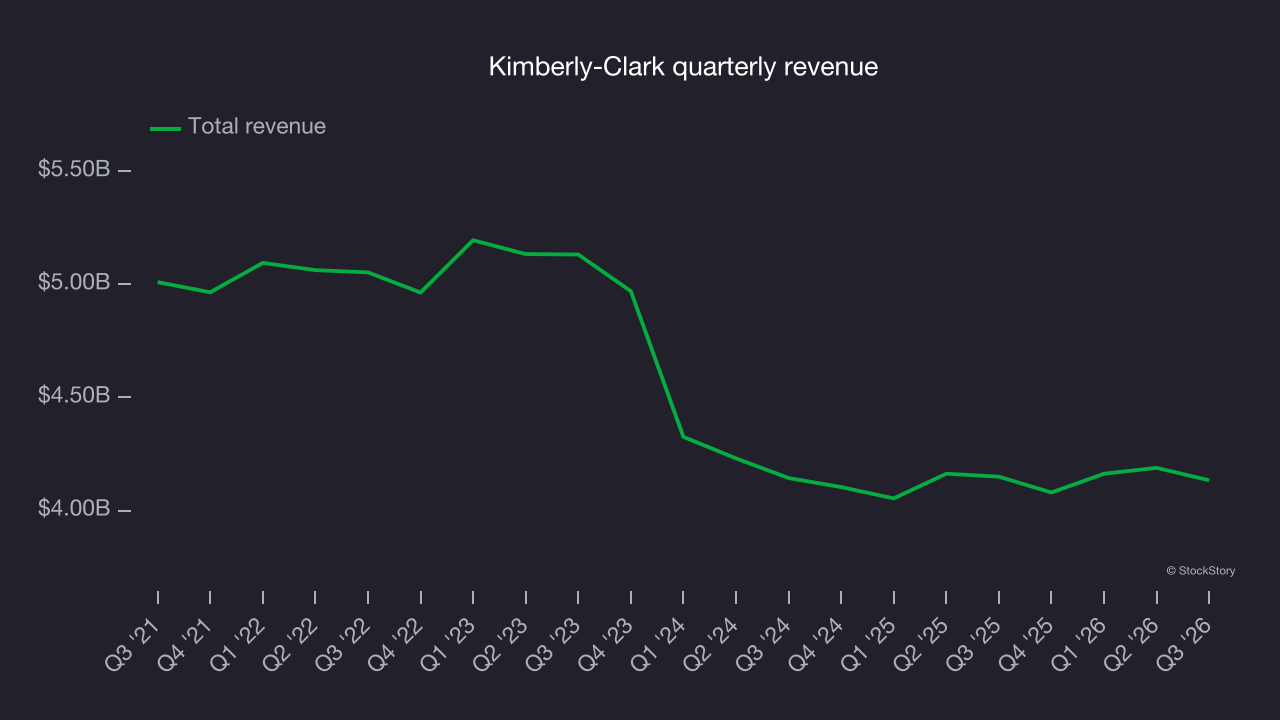
This quarter, Kimberly-Clark’s $4.13 billion in revenue was flat year on year and in line with Wall Street’s consensus estimates.
Looking ahead, sell-side analysts expect revenue to grow 2% over the next 12 months, according to S&P. While this projection indicates its newer products will improve revenue performance, it is still below the sector average.
Organic revenue growth
When analyzing revenue growth, the most important measure is organic revenue growth. This metric captures a business’s performance excluding one-time events such as mergers, acquisitions and divestitures as well as foreign currency fluctuations.
The demand for Kimberly-Clark’s products has been stable over the last eight quarters but fell behind the broader sector. On average, the company has posted feeble year-on-year organic revenue growth of 1.3%.
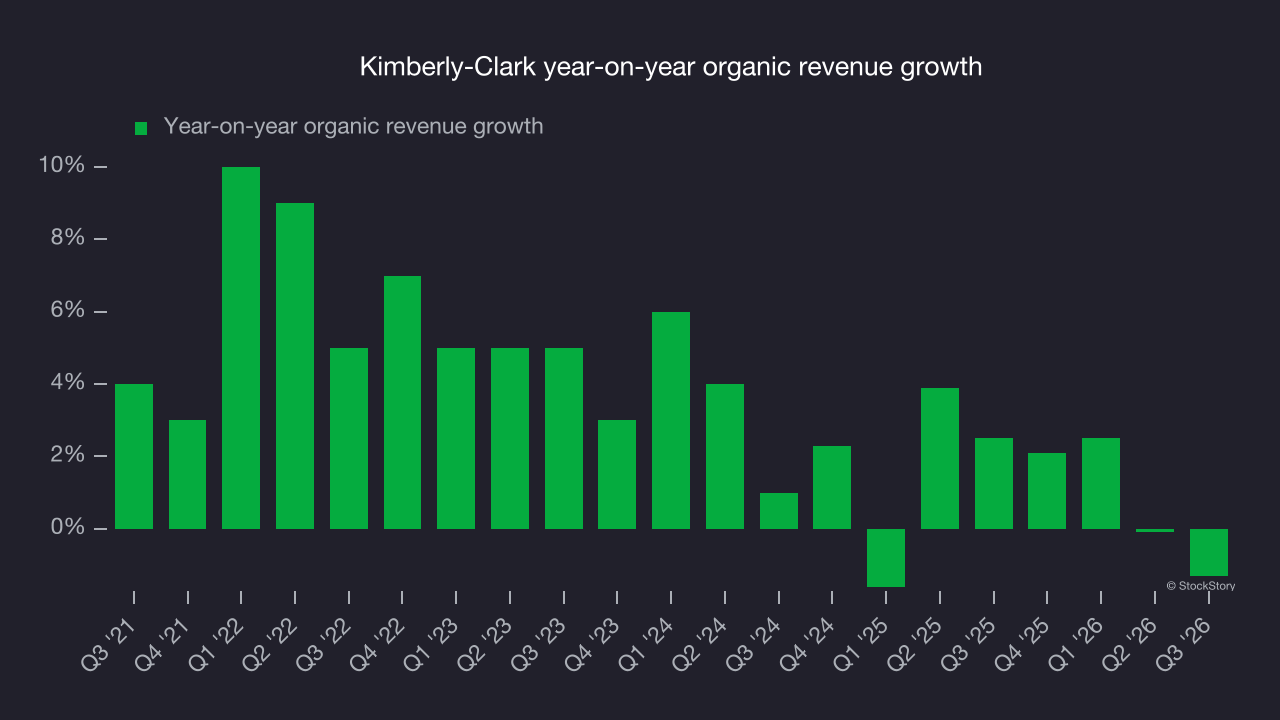
In the latest quarter, Kimberly-Clark’s organic revenue fell by 1.3% year on year. This decline was a reversal from its historical levels. Whether this becomes a longer-term trend bears watching.
Key takeaways from Kimberly-Clark’s Q3 results
Although gross margin missed expectations, and organic revenue fell slightly short of Wall Street’s consensus estimates, adjusted EPS beat expectations. Overall, it was a mixed quarter. Shares nonetheless edged higher 1.7% to $110.64 immediately after the results.
Kimberly-Clark’s latest quarter is only one part of assessing its longer-term business quality. Quality, combined with valuation, can help determine whether the stock is a buy. For more on Kimberly-Clark, read the full research report here (it’s free).