Industrial materials and tools company Kennametal (NYSE: KMT) missed Wall Street’s revenue expectations in calendar Q3 2026 (fiscal Q1 2027), but revenue rose 54.3% year on year to $768.2 million. Next quarter’s revenue guidance of $800 million underwhelmed, coming in 4.9% below analysts’ consensus estimates. Its GAAP profit of $3.48 per share was 31.7% above analysts’ consensus estimates.
For more on Kennametal, read our free full research report.
Kennametal (KMT) Q3 CY2026 highlights:
- Revenue $768.2 million vs S&P analysts’ consensus estimates of $775.3 million (54.3% year-on-year growth, 0.9% miss)
- EPS (GAAP) $3.48 vs analysts’ consensus estimates of $2.64 (31.7% beat)
- Revenue guidance The company reconfirmed its revenue guidance for the full year of $3.39 billion at the midpoint
- Operating margin 49.4%, up from 7.5% in the same quarter last year
- Free cash flow -$212.1 million compared to -$5.48 million in the same quarter last year
- Organic revenue rose 54% year on year (miss)
- Market capitalization $2.33 billion
"This performance reinforces our confidence in the fiscal 2027 sales Outlook and higher full year EPS expectations. Looking beyond fiscal 2027, improving markets and execution on our strategic growth initiatives position us well for continued growth. In a steady-state tungsten environment, we expect to deliver a 16 to 19 percent adjusted EBITDA margin profile while generating strong free operating cash flow and attractive returns on invested capital."
Revenue growth
Examining a company’s long-term performance can provide clues about its quality. Any business can put up a good quarter or two, but many enduring ones grow for years. Over the last five years, Kennametal grew its revenue at a mediocre 6.4% compounded annual growth rate, lagging the rest of the industrials sector. Still, there are things to like about Kennametal.
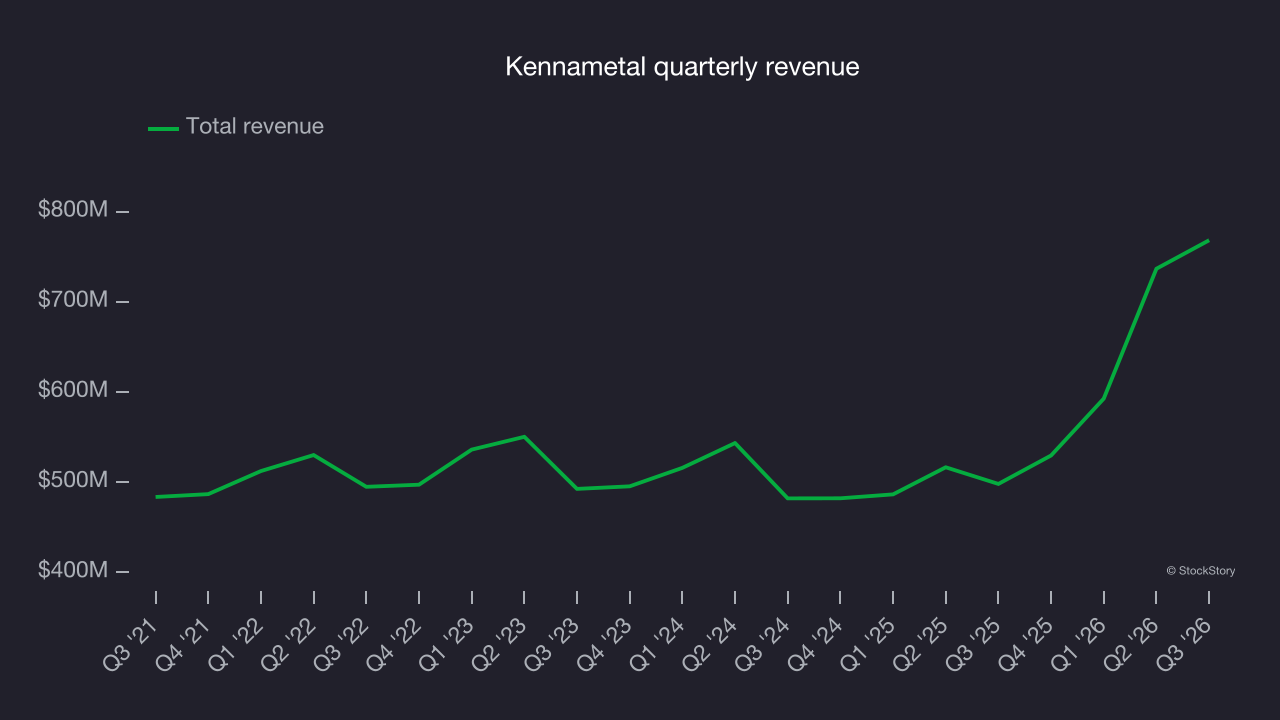
Long-term growth matters the most, but within industrials, a half-decade historical view may miss cycles, industry trends or a company capitalizing on catalysts such as a new contract win or a successful product line. Kennametal’s annualized revenue growth of 13.6% over the last two years is above its five-year trend, suggesting its demand recently accelerated. 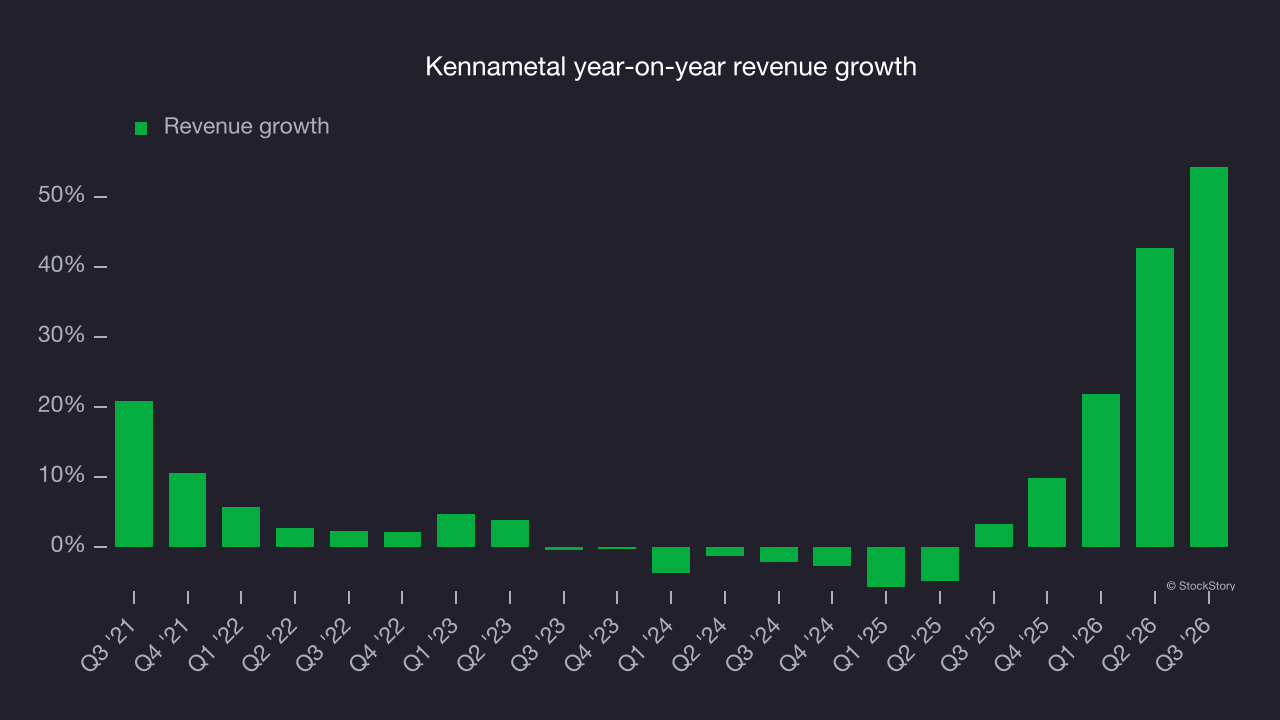
Organic revenue offers a closer look at the company’s revenue dynamics by stripping out one-time events like acquisitions and currency fluctuations that don’t accurately reflect its fundamentals. Over the last two years, Kennametal’s organic revenue averaged 14.3% year-on-year growth. This was in line with its two-year revenue growth, indicating that core operations, rather than acquisitions and divestitures, drove most of its results. 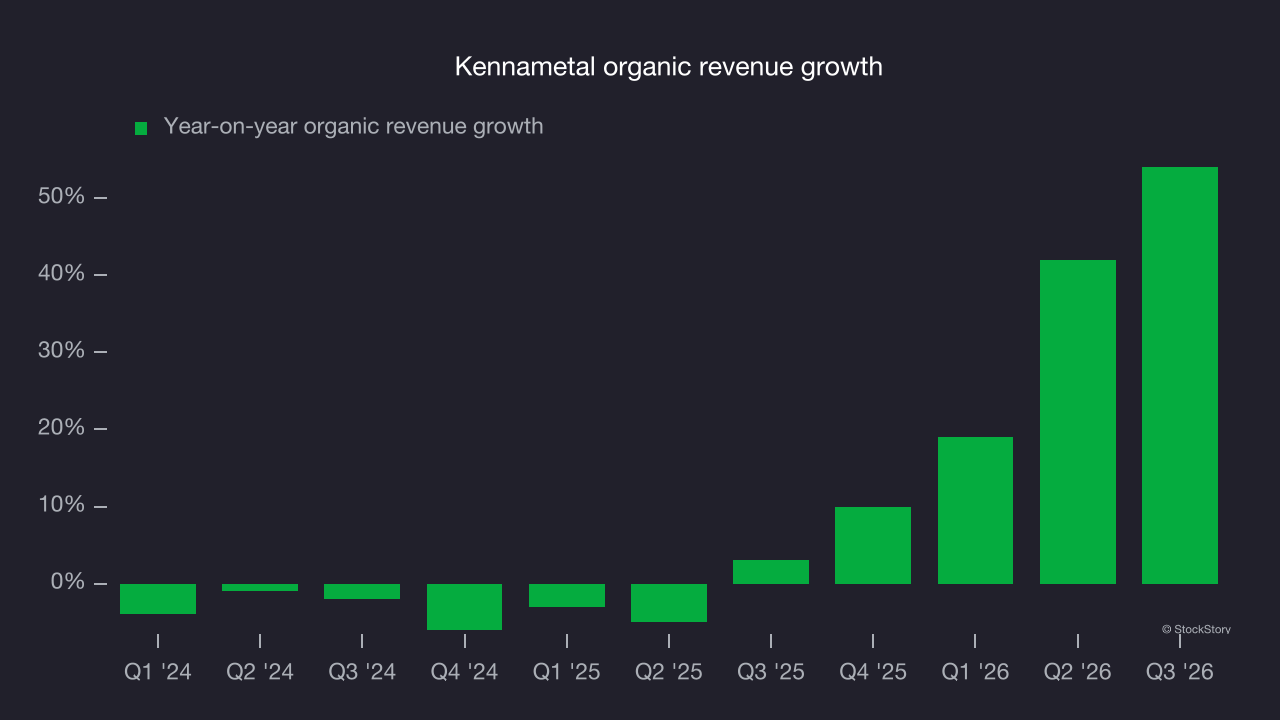
This quarter, Kennametal achieved strong year-on-year revenue growth of 54.3%, but its $768.2 million of revenue fell short of Wall Street’s consensus estimates. Company management is guiding for a 51.1% year-on-year increase in revenue next quarter.
Looking further ahead, sell-side analysts expect revenue to grow 30% over the next 12 months, according to S&P, an improvement versus the last two years. That strong growth outlook indicates its newer products and services will fuel better top-line performance.
Operating margin
Operating margin is one of the best measures of profitability because it shows how much a company earns after procuring and manufacturing its products, marketing and selling those products and, most importantly, keeping them relevant through research and development.
Kennametal has been an efficient company over the last five years. It was one of the more profitable businesses in the industrials sector, with an average operating margin of 14.2%. That outcome is unsurprising given its favorable gross margin baseline.
Analyzing the trend in its profitability, Kennametal’s operating margin rose by 20.5 percentage points over the last five years, as its revenue growth gave it operating leverage.
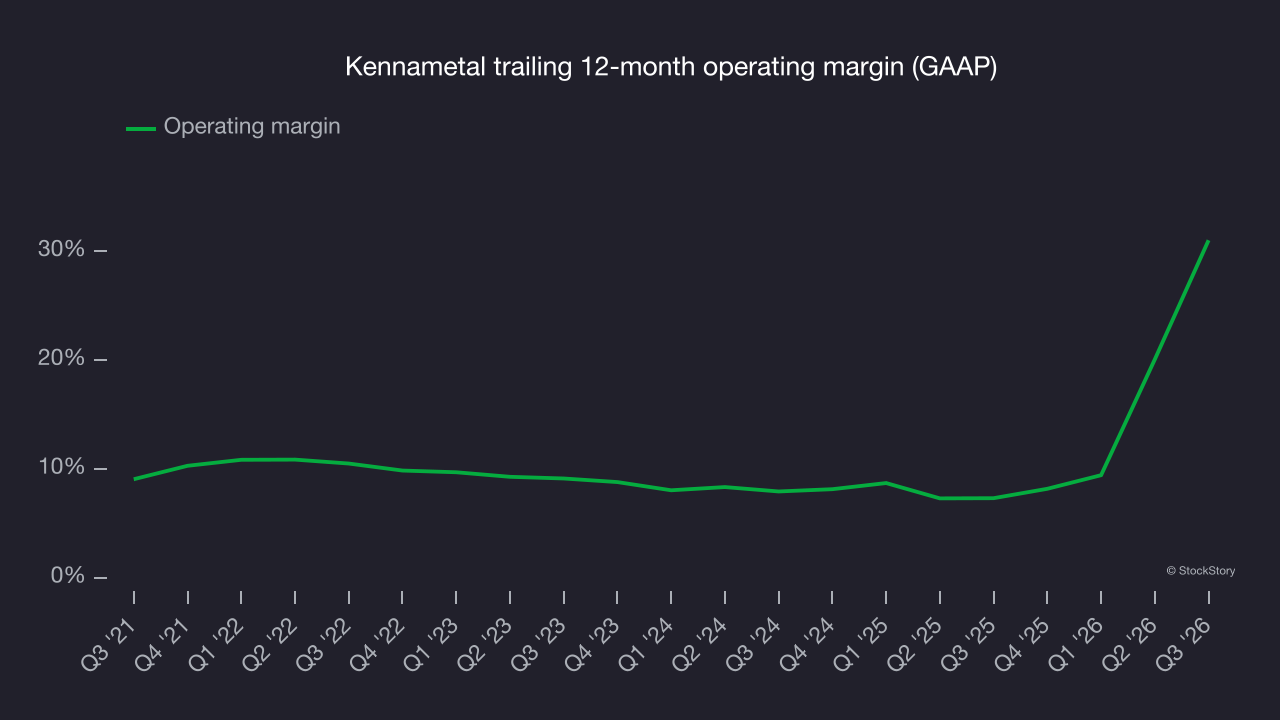
In Q3, Kennametal generated an operating margin of 49.4%, up 41.8 percentage points year on year. The increase was solid, and its operating margin rose more than its gross margin, indicating greater efficiency in expenses such as marketing, research and development and administrative overhead.
Earnings per share
We track the long-term change in earnings per share, or EPS, for the same reason as long-term revenue growth. Compared to revenue, however, EPS highlights whether a company’s growth is profitable.
Kennametal’s EPS grew at a 41.7% compounded annual growth rate over the last five years, higher than its 6.4% annualized revenue growth. This indicates the company became more profitable on a per-share basis as it expanded.
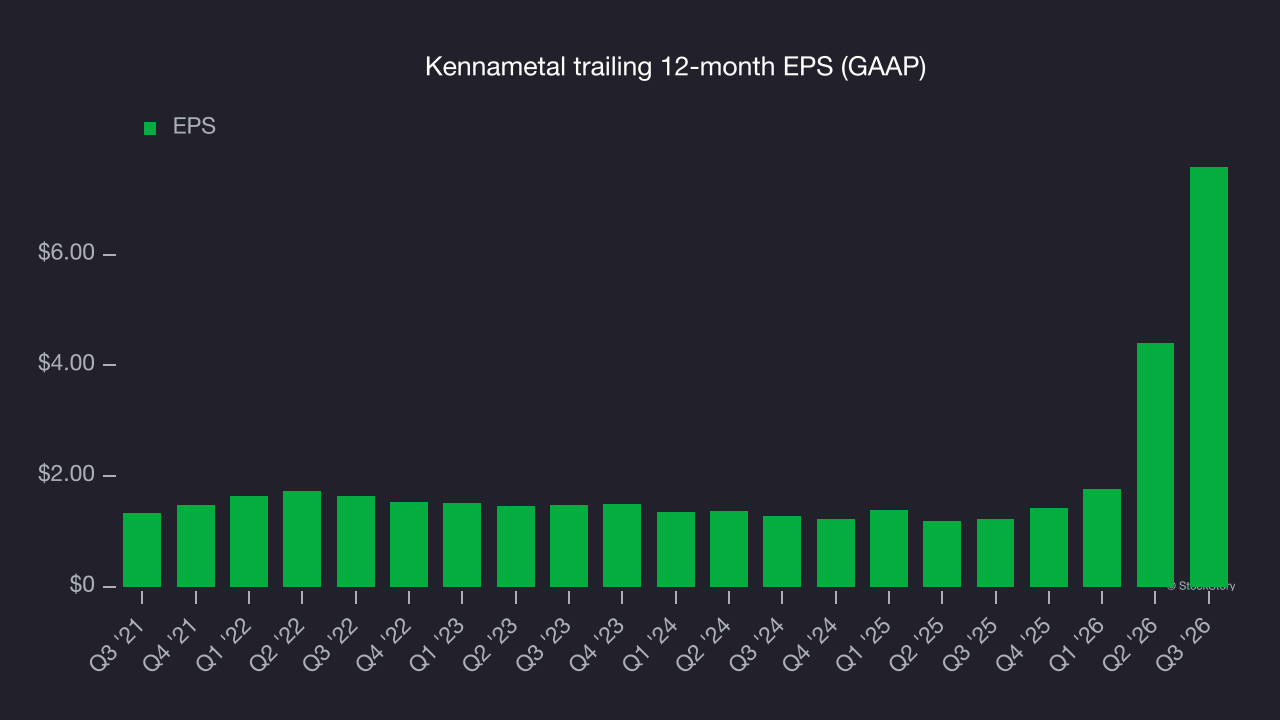
A closer look at Kennametal’s earnings quality helps explain the drivers of its performance. Kennametal’s operating margin expanded by 20.5 percentage points over the last five years. Its share count also shrank by 7.8%. These are positive signs for shareholders because improving profitability and share buybacks boost EPS growth relative to revenue growth. 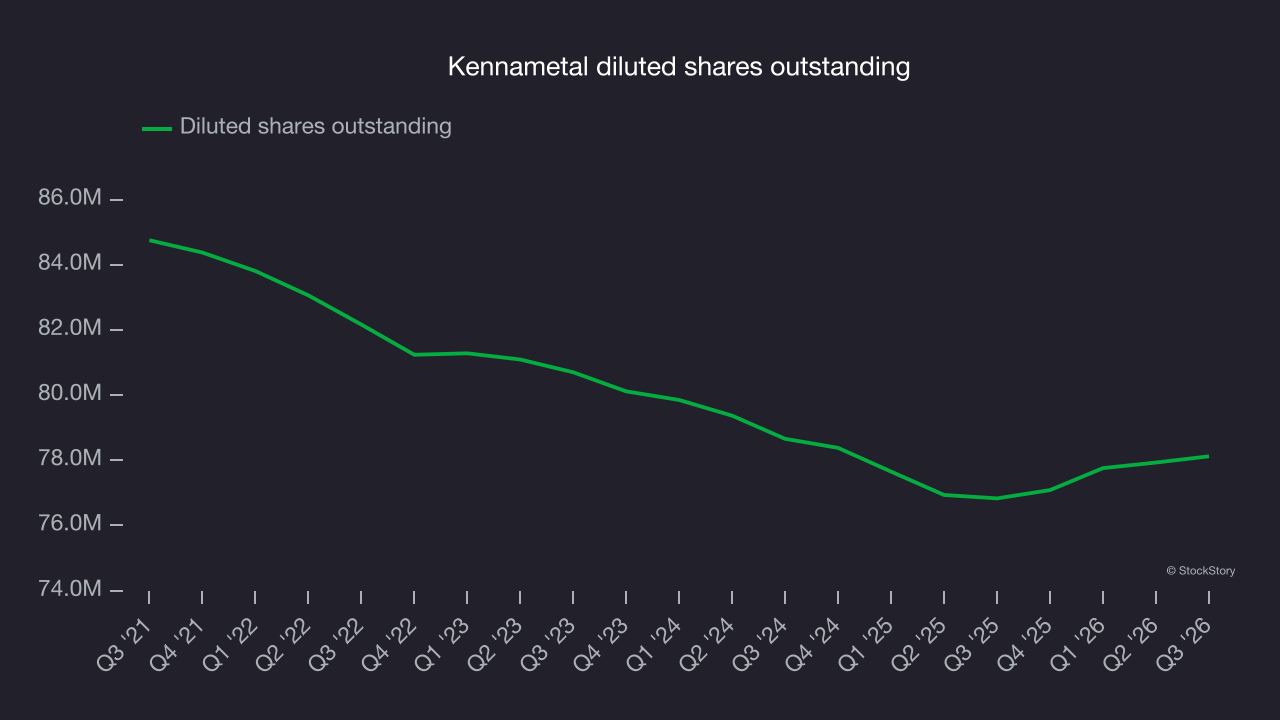
As with revenue, we analyze EPS over a shorter period to see if we are missing a change in the business.
For Kennametal, its two-year annual EPS growth of 144% was higher than its five-year trend. That acceleration is a positive sign, particularly given the already high base.
In Q3, Kennametal reported EPS of $3.48, up from $0.30 in the same quarter last year. This result comfortably topped analysts’ consensus estimates, a positive outcome for shareholders. Over the next 12 months, Wall Street expects Kennametal’s full-year EPS to shrink by 64.5% from $7.58 to $2.69, according to S&P.
Key takeaways from Kennametal’s Q3 results
Kennametal’s quarter was softer overall, with organic revenue falling short of Wall Street’s consensus estimates and next-quarter revenue guidance also missing expectations. The positives were an EPS beat against analysts’ consensus estimates and full-year revenue guidance in line with Wall Street’s consensus. Shares rose 4.8% to $31.99 immediately after the release.
Kennametal’s latest quarter is only one piece of the longer-term business quality picture. Quality, combined with valuation, can help determine whether the stock is a buy. For more on Kennametal, read the full research report here (it’s free).