Food distributor Sysco (NYSE: SYY) missed Wall Street’s revenue expectations in calendar Q3 2026 (fiscal Q1 2027) as revenue rose 2.8% year on year to $21.74 billion. Its non-GAAP profit of $1.19 per share was in line with analysts’ consensus estimates.
For more on Sysco, read our free full research report.
Sysco (SYY) Q3 CY2026 highlights:
- Revenue $21.74 billion vs S&P analysts’ consensus estimates of $22 billion (2.8% year-on-year growth, 1.2% miss)
- Adjusted EPS $1.19 vs S&P analysts’ consensus estimates of $1.19 (in line)
- Adjusted EBITDA $1.1 billion vs analysts’ consensus estimates of $1.15 billion (5.1% margin, 4.6% miss)
- Operating margin 3.3%, in line with the same quarter last year
- Free cash flow $181 million, up from -$74 million in the same quarter last year
- Market capitalization $40.21 billion
“We are pleased to report a strong start to fiscal 2027. Our Q1 adjusted EPS performance was in-line with our expectations, fueled by positive volume growth, expanding gross margins, and disciplined expense control. We delivered profitable growth across the US and International segments despite continued softness in restaurant foot traffic, higher than expected fuel costs, and lower than expected U.S. food cost inflation. Sysco remains firmly focused on three priorities for the year: a) delivering with excellence for our customers, as well as our core Sysco financial commitments, b) improving our operating margins through AI-powered business transformation, and c) preparing for the anticipated closure of the Jetro Restaurant Depot transaction. I want to thank our entire team for their customer focus, the improvement in our business that they are delivering, and express how excited everyone at Sysco is for the year ahead,” said Kevin Hourican, Sysco’s Chair of the Board and Chief Executive Officer.
Revenue growth
A company’s long-term revenue performance is one signal of its overall quality. Even a poor business can perform well for one or two quarters, but a high-quality one grows for years. Sysco’s revenue grew at a weak 8.8% compounded annual growth rate over the last five years, falling short of the consumer discretionary sector benchmark.
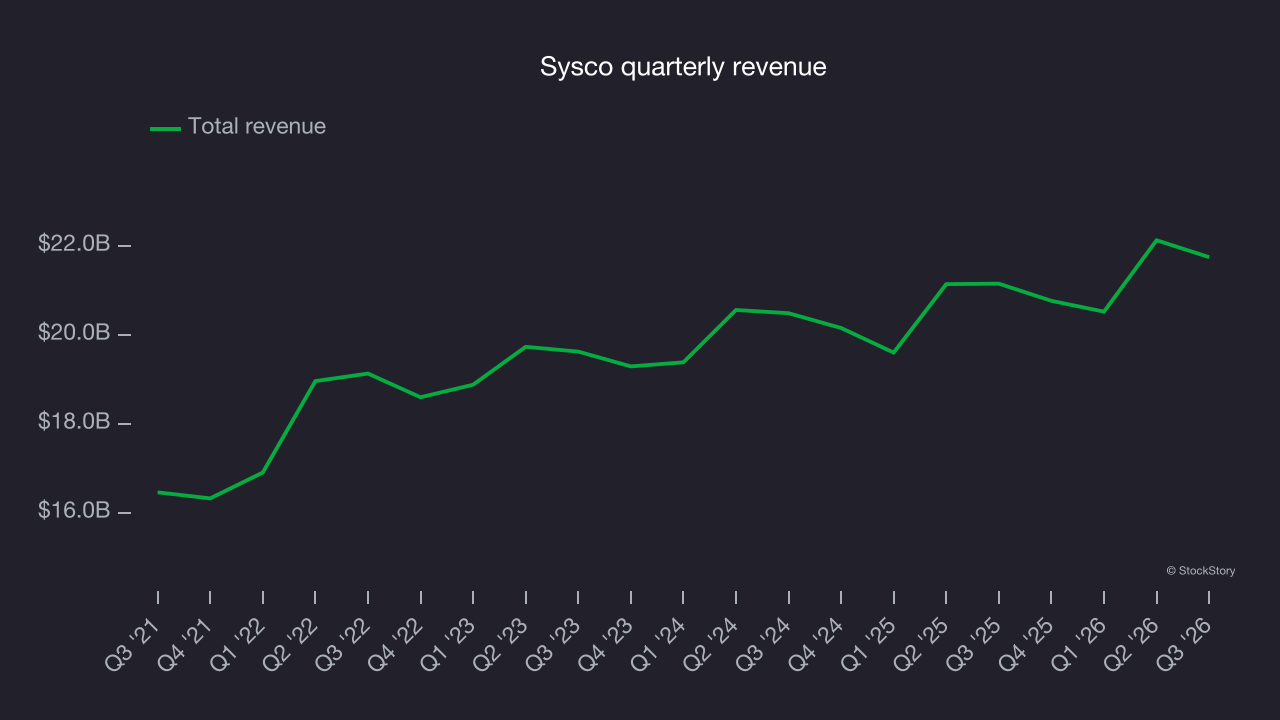
Long-term growth matters most, but within consumer discretionary, a longer historical view may miss a company benefiting from a successful new product or trend. Sysco’s recent performance shows its demand has slowed as its annualized revenue growth of 3.4% over the last two years was below its five-year trend. Decelerating revenue growth in the sector warrants caution, as it could signal changing consumer tastes aided by low switching costs. 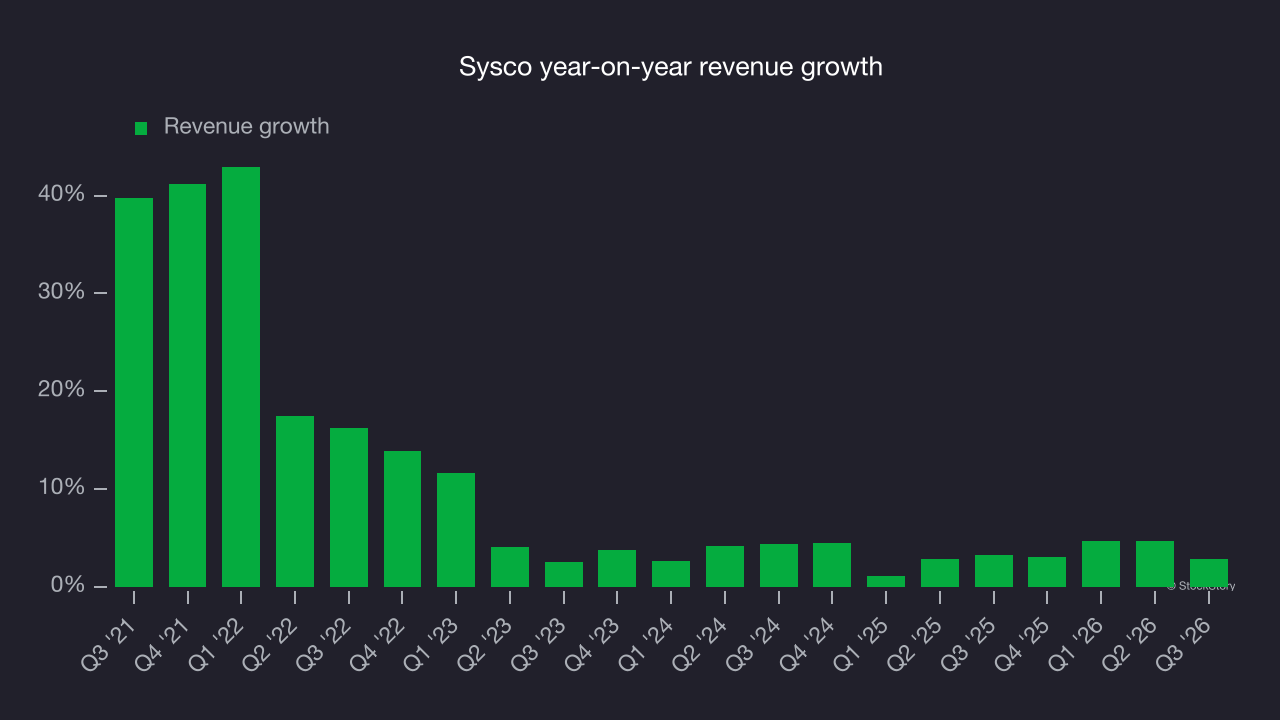
This quarter, Sysco’s revenue grew by 2.8% year on year to $21.74 billion, falling short of Wall Street’s consensus estimates.
Looking ahead, sell-side analysts expect revenue to grow 6.3% over the next 12 months, according to S&P. While this projection indicates its newer products and services will fuel better top-line performance, it is still below the sector average.
Operating margin
Sysco’s operating margin has been largely unchanged over the last 12 months, falling short of the margin increases generally expected from economies of scale and cost efficiency over time.
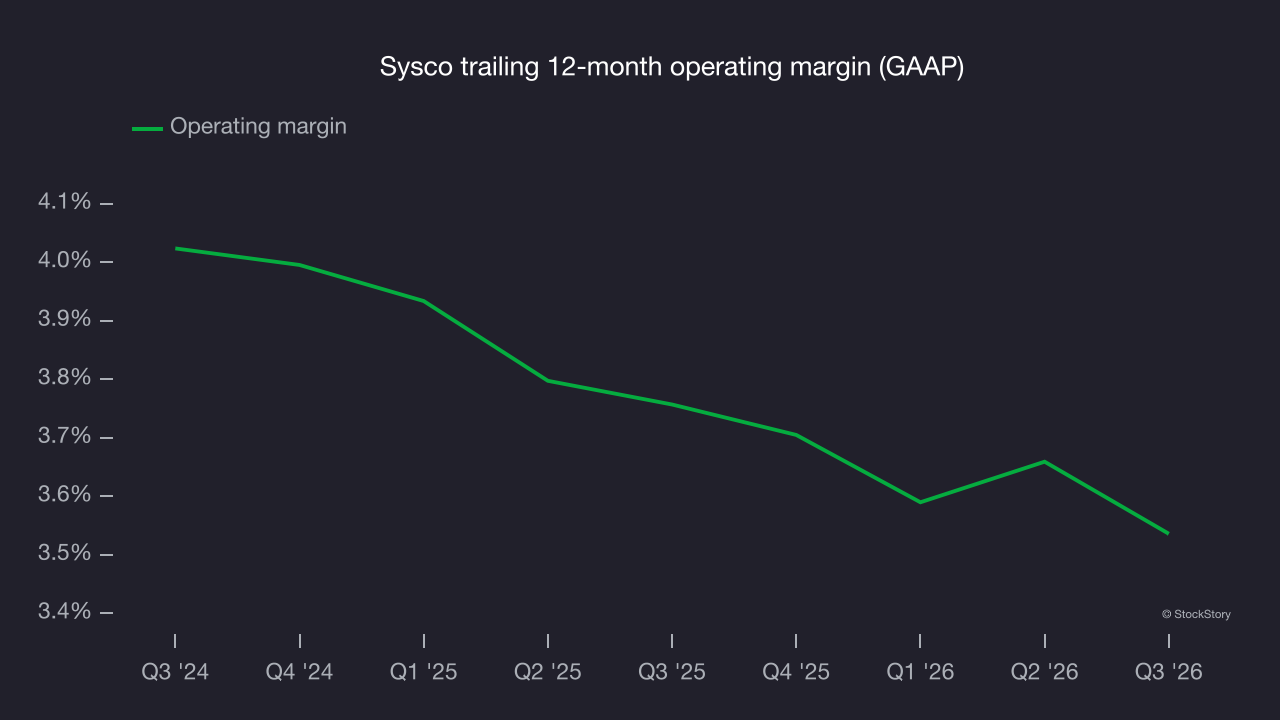
In Q3, Sysco generated an operating margin of 3.3%, in line with the same quarter last year. This indicates the company’s overall cost structure has been relatively stable.
Earnings per share
Revenue trends explain a company’s historical growth, but the long-term change in earnings per share, or EPS, points to the profitability of that growth. For example, a company could inflate its revenue through excessive spending on advertising and promotions.
Sysco’s EPS grew at a 19.2% compounded annual growth rate over the last five years. This performance was better than its revenue growth but doesn’t tell us much about its business quality because its operating margin improvement was smaller than that of its peers.
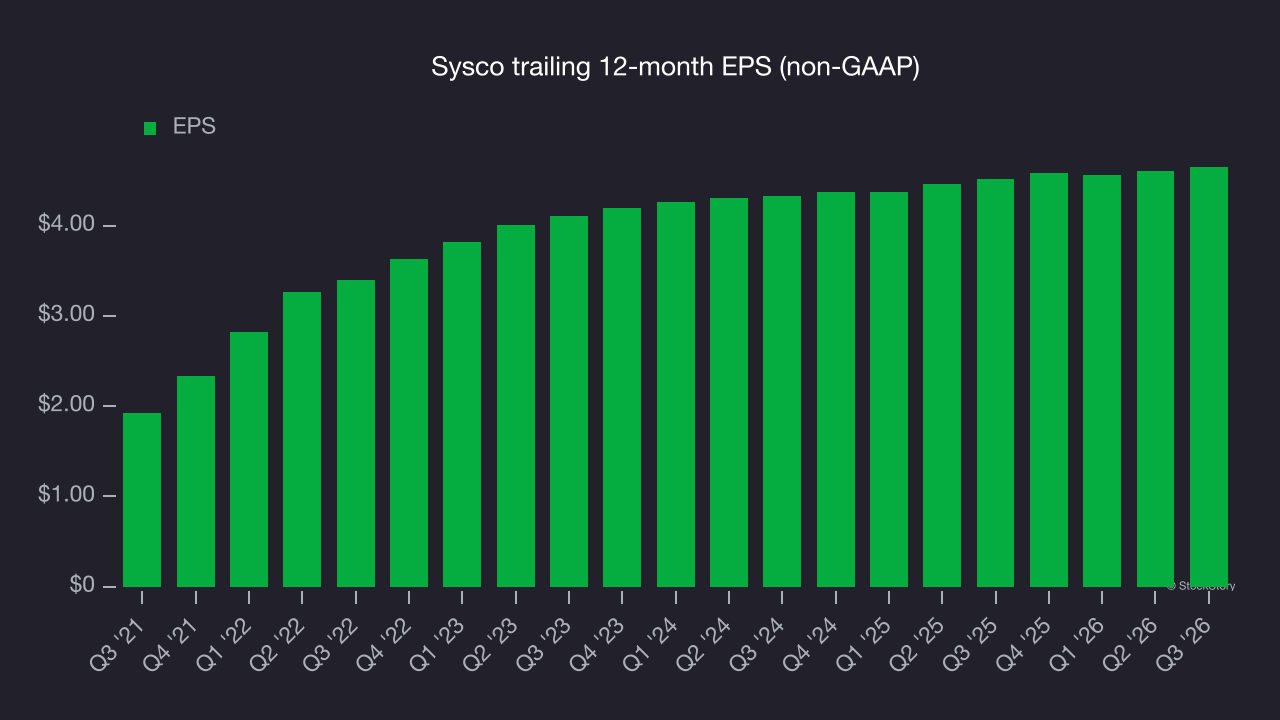
In Q3, Sysco reported adjusted EPS of $1.19, up from $1.15 in the same quarter last year. This result was close to analysts’ consensus estimates. Over the next 12 months, Wall Street expects Sysco’s full-year EPS to grow 10.5% from $4.65 to $5.14, according to S&P.
Key takeaways from Sysco’s Q3 results
Sysco’s quarter offered few positives: Revenue narrowly missed Wall Street’s consensus estimates, and EBITDA also fell short. Those shortfalls made for a weaker quarter overall. Shares tumbled 6.3% to $76.56 immediately after the report.
Sysco underperformed this quarter. When deciding whether the stock is a buy, the latest quarter matters, but not nearly as much as longer-term fundamentals and valuation. For more on Sysco, read our free full research report here.