
Home automation and security solutions provider Resideo Technologies (NYSE: REZI) announced better-than-expected revenue in Q3 2026, but revenue fell by 61% year on year to $727 million. On the other hand, next quarter’s revenue guidance of $720 million was less impressive, coming in 2.5% below analysts’ consensus estimates. Its non-GAAP profit of $0.52 per share was 28.9% above analysts’ consensus estimates.
For more on Resideo, read our full research report, available free.
Resideo (REZI) Q3 2026 highlights:
- Revenue $727 million vs S&P analysts’ consensus estimates of $712.9 million (61% year-on-year decline, 2% beat)
- Adjusted EPS $0.52 vs S&P analysts’ consensus estimates of $0.40 (28.9% beat)
- Adjusted EBITDA $154 million vs analysts’ consensus estimates of $148.4 million (21.2% margin, 3.8% beat)
- Revenue guidance $720 million at the midpoint for Q4 2026, below analysts’ consensus estimates of $738.6 million
- Adjusted EPS guidance $1.95 at the midpoint for the full year, missing analysts’ consensus estimates by 2.5%
- EBITDA guidance $619 million at the midpoint for the full year, below analysts’ consensus estimates of $677.2 million
- Operating margin 9.9%, up from 8.3% in the same quarter last year
- Free cash flow -$21 million
- Market capitalization $3.04 billion
"Resideo delivered top and bottom line third quarter results that were near the high end of our outlook ranges in our first quarter following the separation of ADI, underscoring our team's continued strong execution. We achieved 3% revenue growth year-over-year across all sales channels and 6% growth year-over-year excluding OEM Security, driven by customer demand for our differentiated, non-discretionary products. We also reduced our debt by $1.1 billion, using the $900 million dividend received from ADI and $200 million of cash on hand," said Tom Surran, Resideo's President and CEO.
Revenue growth
Reviewing a company’s long-term revenue performance reveals insights into its quality. Any business can have short-term success, but a top-tier one grows for years. Over the last five years, Resideo grew its revenue at a sluggish 2% compounded annual growth rate, falling short of our standards.
Long-term growth is the most important, but within industrials, a half-decade historical view may miss new industry trends or demand cycles. Resideo’s recent performance shows its demand has slowed as its revenue was flat over the last two years.
Operating margin
Over the last five years, Resideo’s operating margin fell by 3.6 percentage points. This deterioration shows its costs grew relative to revenue, putting pressure on profitability. Its trailing 12-month operating margin was 6.8%.
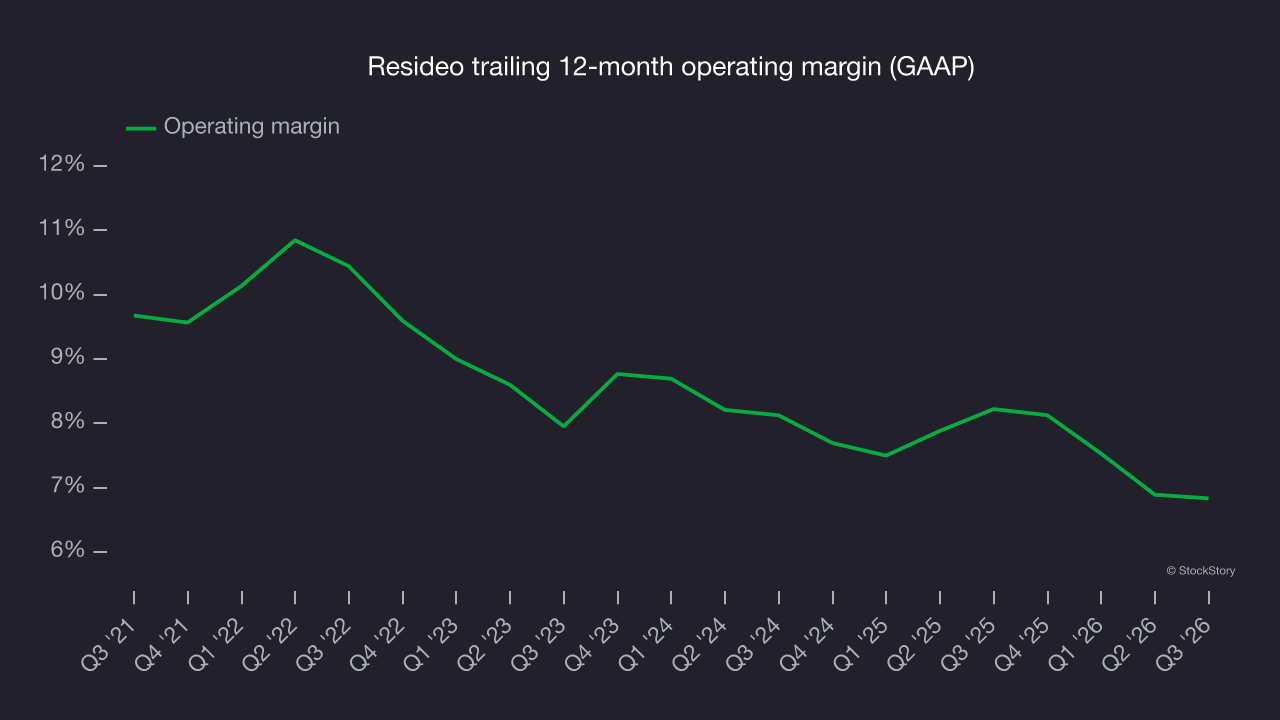
This quarter, Resideo generated an operating profit margin of 9.9%, up 1.6 percentage points year on year. Its gross margin expanded more than its operating margin, indicating that leverage on its cost of sales was the primary driver of the recent improvement in efficiency.
Earnings per share
We track the long-term change in earnings per share (EPS) for the same reason as long-term revenue growth. Compared to revenue, however, EPS highlights whether a company’s growth is profitable.
Resideo’s weak 2.5% annual EPS growth over the last five years aligns with its revenue performance. This tells us it maintained its per-share profitability as it expanded.
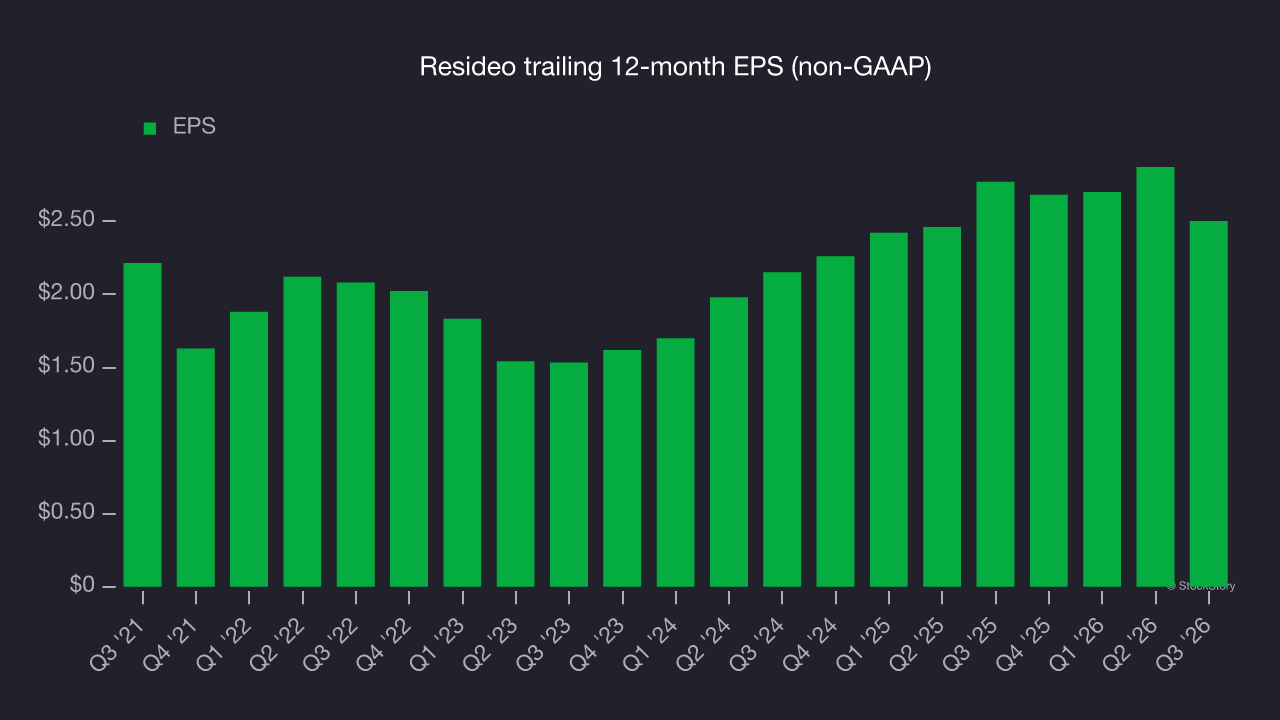
As with revenue, we analyze EPS over a shorter period to see if we are missing a change in the business.
Although underwhelming, Resideo’s two-year annual EPS growth of 7.8% topped its flat revenue.
We can take a deeper look into Resideo’s earnings to better understand the drivers of its performance. Resideo’s operating margin has expanded over the last two years. This was the most relevant factor (aside from the revenue impact) behind its higher earnings; interest expenses and taxes can also affect EPS but don’t tell us as much about a company’s fundamentals.
In Q3, Resideo reported adjusted EPS of $0.52, down from $0.89 in the same quarter last year. Despite falling year on year, this result came in well above analysts’ consensus estimates. Over the next 12 months, Wall Street expects Resideo’s full-year EPS to shrink by 22.2% from $2.50 to $1.95, according to S&P.
Key takeaways from Resideo’s Q3 results
Resideo’s Q3 revenue and EPS topped analysts’ consensus estimates, but its full-year outlook fell short on both revenue and EBITDA. Those guidance misses left room for a better quarter despite the earnings beats. Shares tumbled 6.8% to $18.38 immediately after the report.
Resideo’s earnings report left something to be desired. Let’s look ahead to assess whether the stock is worth buying after this quarter. That decision should take into account valuation and business quality as well as the latest earnings. For more on Resideo, read the full research report here (it’s free).