
Since April 2026, Everforth has been in a holding pattern, posting a small loss of 3.8% while floating around $35.88. The stock also fell short of the S&P 500’s 14.3% gain during that period.
Is now the time to buy Everforth, or should you be careful about including it in your portfolio? Get the full breakdown from our expert analysts, it’s free.
Why Do We Think Everforth Will Underperform?
We’re sitting this one out for now. Here are three reasons we avoid EFOR, plus one stock we’d rather own.
1. Long-Term Revenue Growth Disappoints
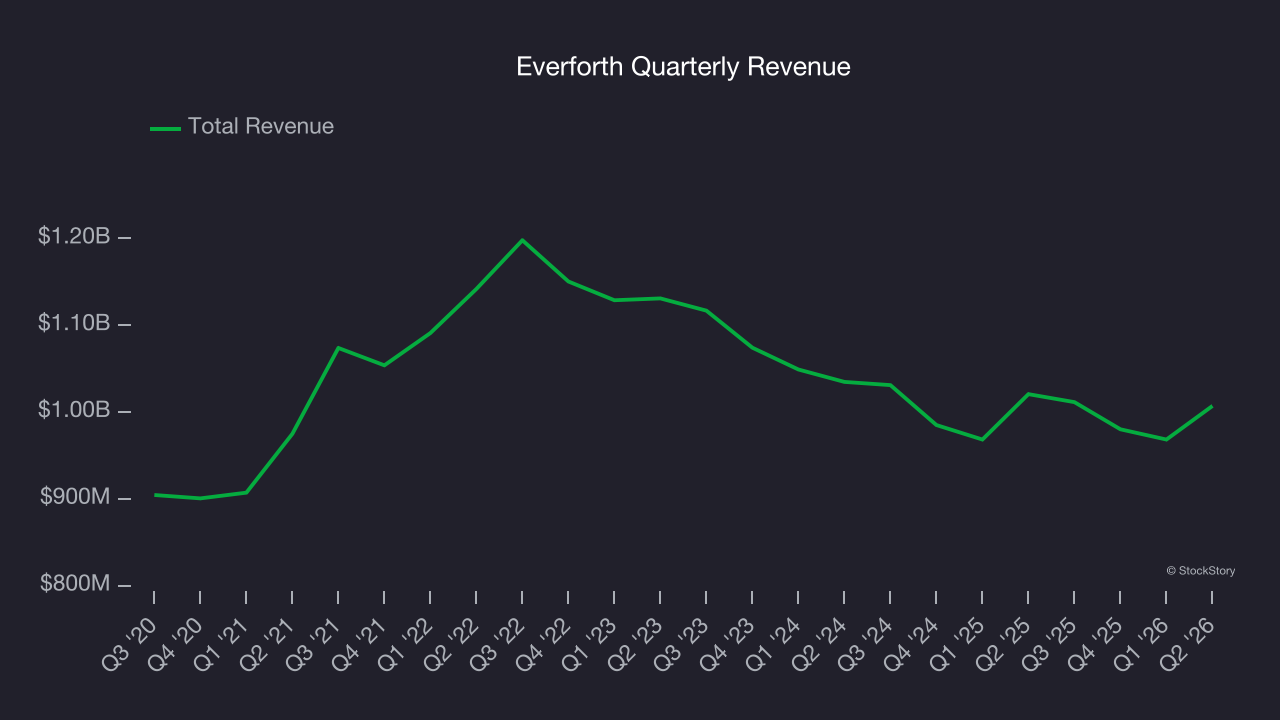
Reviewing a company’s long-term sales performance reveals insights into its quality. Any business can experience short-term success, but top-performing ones enjoy sustained growth for years. Regrettably, Everforth’s sales grew at a sluggish 1.5% compounded annual growth rate over the last five years. This fell short of our benchmarks.
2. Projected Revenue Growth Shows Limited Upside
Forecasted revenues by Wall Street analysts signal a company’s potential. Predictions may not always be accurate, but accelerating growth typically boosts valuation multiples and stock prices while slowing growth does the opposite.
Over the next 12 months, sell-side analysts expect Everforth’s revenue to stall. Although this projection suggests its newer products and services will catalyze better top-line performance, it is still below the sector average.
3. EPS Trending Down
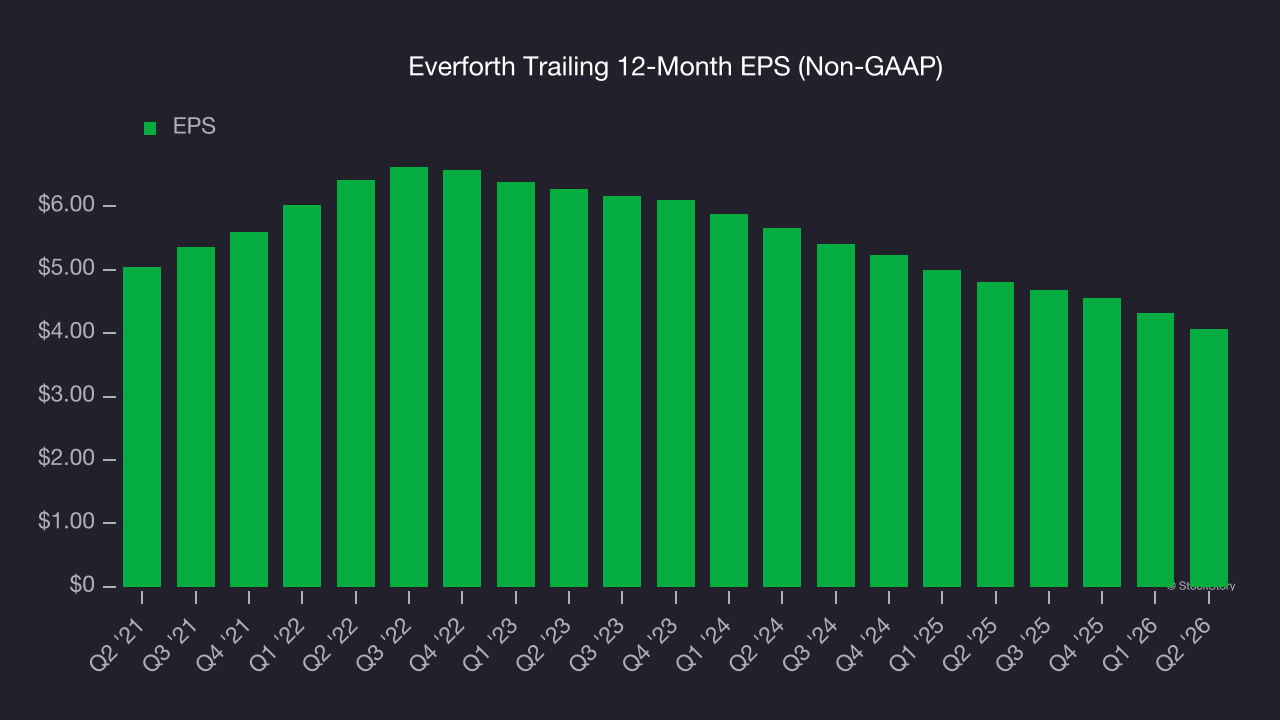
We track the long-term change in earnings per share (EPS) because it highlights whether a company’s growth is profitable.
Sadly for Everforth, its EPS declined by 4.3% annually over the last five years while its revenue grew by 1.5%. This tells us the company became less profitable on a per-share basis as it expanded.
Final Judgment
We cheer for all companies making their customers lives easier, but in the case of Everforth, we’ll be cheering from the sidelines. With its shares lagging the market recently, the stock trades at 8.9× forward P/E (or $35.88 per share). While this valuation is optically cheap, the potential downside is huge given its shaky fundamentals. There are better stocks to buy right now. We’d suggest looking at one of our all-time favorite software stocks.
Stocks We Like More Than Everforth
ONE MORE THING: Top 5 Growth Stocks. The biggest stock winners almost always had one thing in common before they ran. Revenue growing like crazy. Meta. CrowdStrike. Broadcom. Our AI flagged all three. They returned 315%, 314%, and 455%, respectively.
Find out which 5 stocks it’s flagging this month — FREE. Get Our Top 5 Growth Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Exlservice (+271% between June 2020 and June 2025). Find your next big winner with StockStory today.