Racing, gaming and entertainment company Churchill Downs (NASDAQ: CHDN) met Wall Street’s revenue expectations in Q3 2026, with revenue up 1.9% year on year to $696 million. Its non-GAAP profit of $1.23 per share was 11.9% above analysts’ consensus estimates.
For more on Churchill Downs, read our free full research report.
Churchill Downs (CHDN) Q3 2026 highlights:
- Revenue $696 million vs S&P analysts’ consensus estimates of $699.4 million (1.9% year-on-year growth, in line)
- Adjusted EPS $1.23 vs S&P analysts’ consensus estimates of $1.10 (11.9% beat)
- Adjusted EBITDA $264 million vs analysts’ consensus estimates of $260.3 million (37.9% margin, 1.4% beat)
- Operating margin 20.5%, up from 14.3% in the same quarter last year
- Free cash flow margin 12.8%, down from 18.7% in the same quarter last year
- Market capitalization $5.68 billion
Revenue growth
A company’s long-term revenue performance can indicate its overall quality. Any business can report a good quarter or two, but the best consistently grow over the long haul. Over the last five years, Churchill Downs grew its revenue at a 14.7% compounded annual growth rate. Though this growth is acceptable on an absolute basis, revenue growth alone is not enough to assess companies in the consumer discretionary sector, which can display significant earnings volatility. The bar for the sector is particularly high, reflecting the nonessential and hit-driven nature of the products and services offered. Additionally, the five-year CAGR starts around Covid, when revenue was depressed before rebounding.
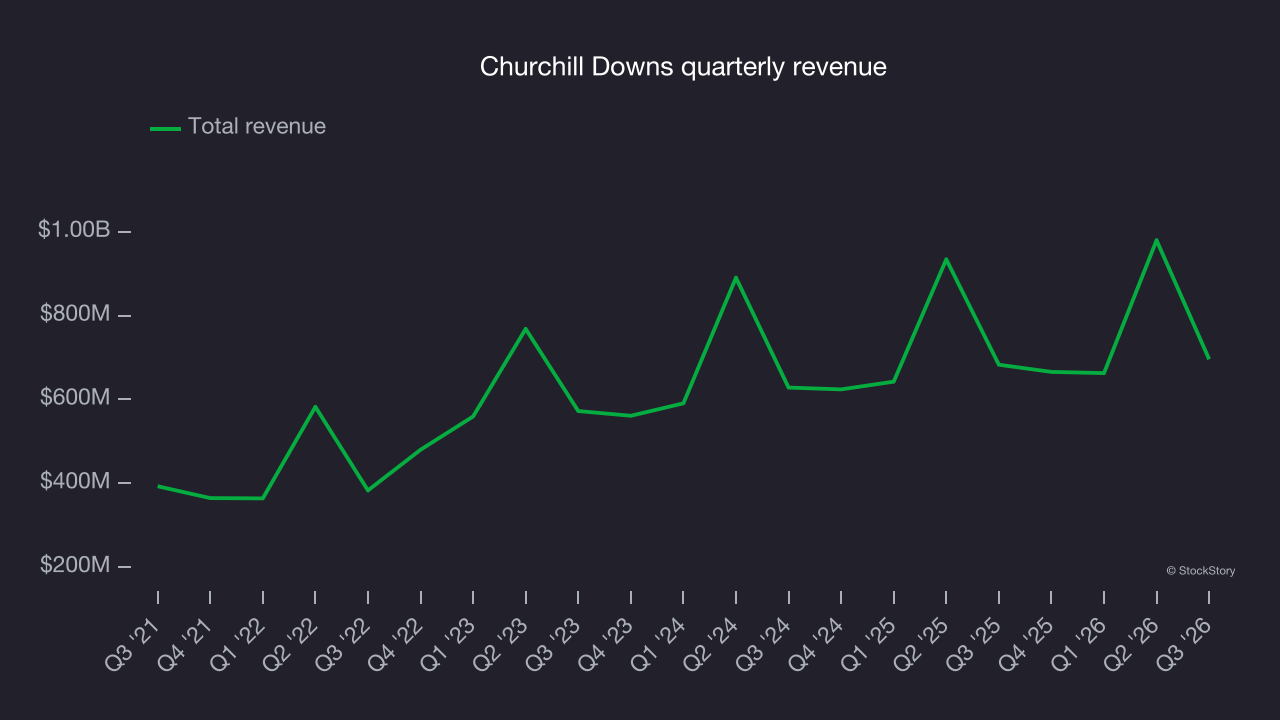
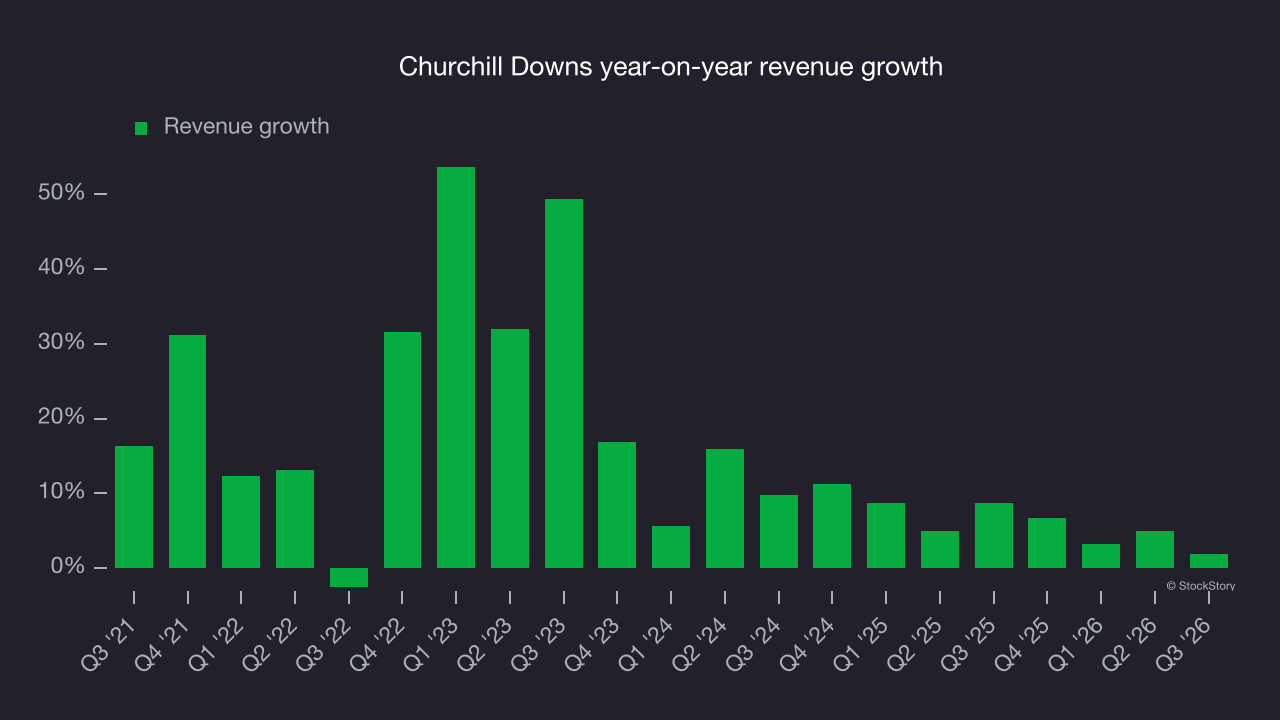
This quarter, Churchill Downs grew its revenue by 1.9% year on year, and its $696 million of revenue was in line with Wall Street’s consensus estimates.
Looking ahead, sell-side analysts expect revenue to grow 2.9% over the next 12 months, according to S&P, a deceleration versus the last two years. This underwhelming projection suggests its products and services will see some demand headwinds.
Operating margin
Operating margin is an important measure of profitability as it shows the portion of revenue left after accounting for all core expenses, everything from the cost of goods sold to advertising and wages. It’s also useful for comparing profitability across companies with different levels of debt and tax rates because it excludes interest and taxes.
Churchill Downs’s operating margin has been trending up over the last 12 months and averaged 24.7% over the last two years. The company’s higher efficiency is a positive sign, but its suboptimal cost structure means it still has poor profitability for a consumer discretionary business.
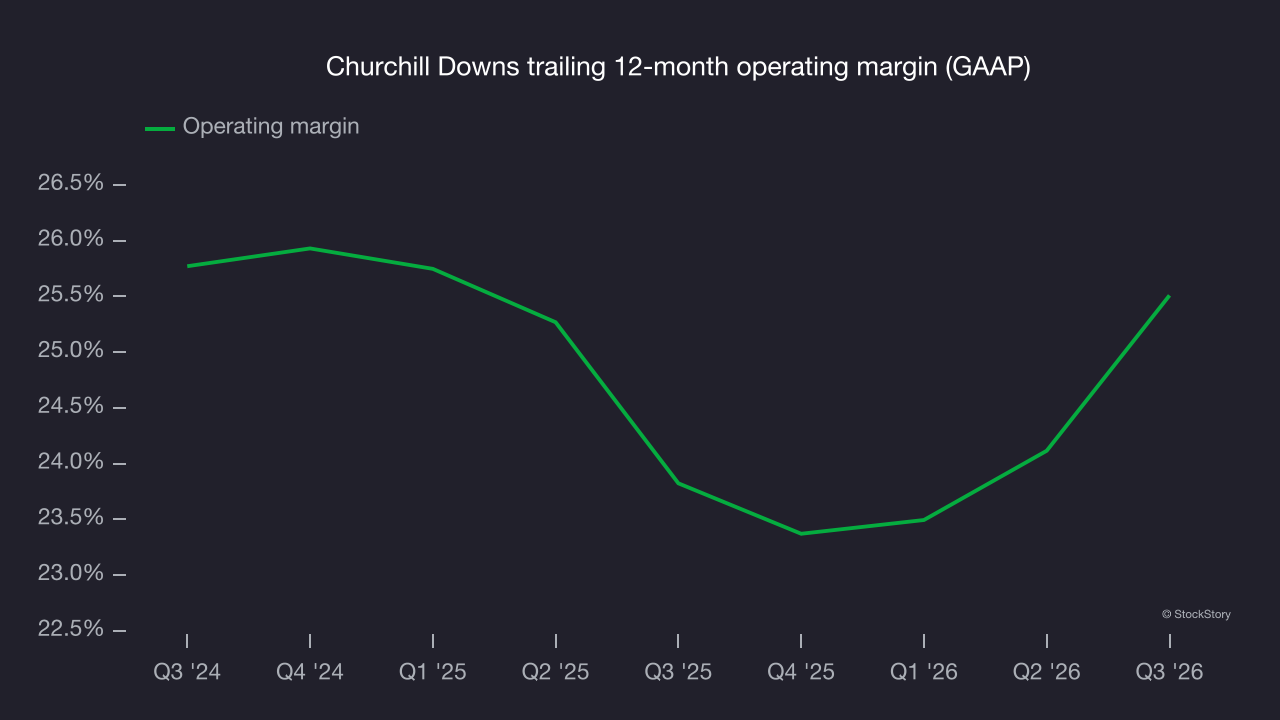
In Q3, Churchill Downs generated an operating margin of 20.5%, up 6.2 percentage points year on year. This increase was a positive development, showing improved efficiency.
Earnings per share
Revenue trends explain a company’s historical growth, but the long-term change in earnings per share (EPS) points to the profitability of that growth – for example, a company could inflate its revenue through excessive spending on advertising and promotions.
Churchill Downs’s EPS grew at a 19% compounded annual growth rate over the last five years. On the positive side, this outpaced its 14.7% annualized revenue growth, indicating the company became more profitable on a per-share basis as it expanded.
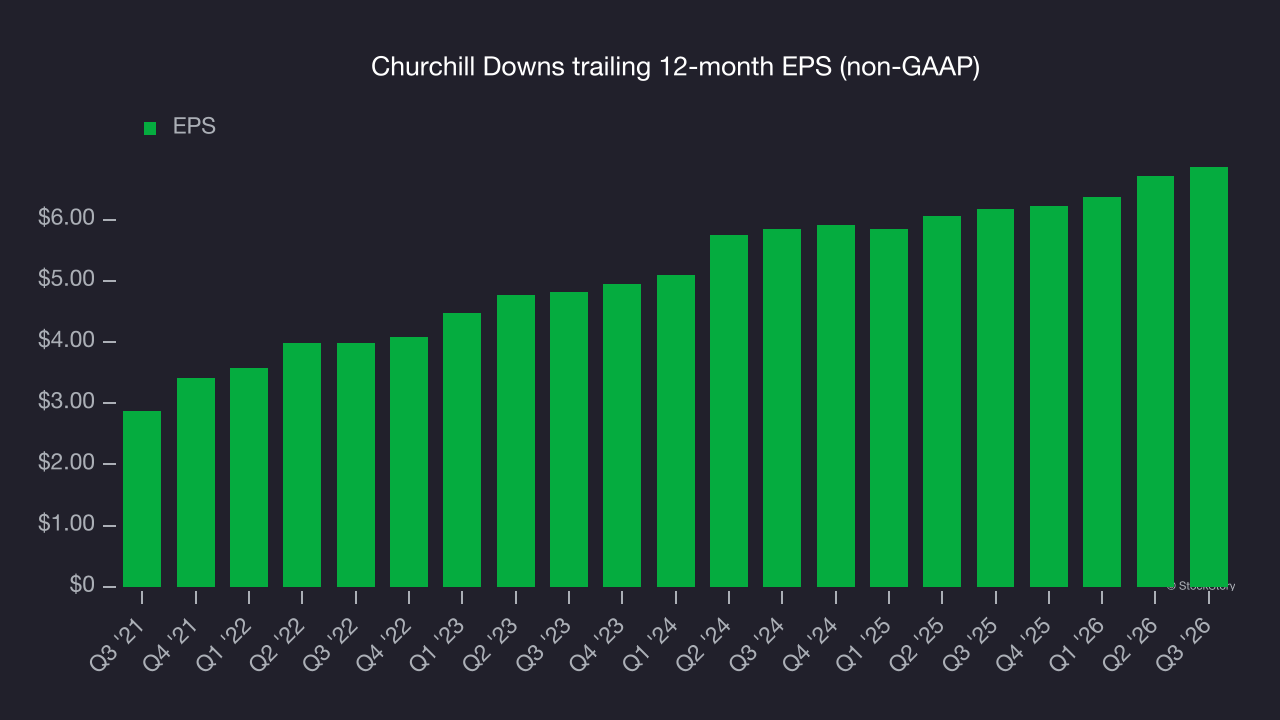
In Q3, Churchill Downs reported adjusted EPS of $1.23, up from $1.09 in the same quarter last year. This was a solid result, well above analysts’ consensus estimates. Over the next 12 months, Wall Street expects Churchill Downs’s full-year EPS to grow 4.2% from $6.86 to $7.15, according to S&P.
Key takeaways from Churchill Downs’s Q3 results
Churchill Downs’s EPS beat analysts’ consensus estimates, but revenue came in line with expectations, leaving the quarter with some key positives rather than a clear-cut beat. Investors were likely hoping for more: Shares edged lower 1.1% to $81.05 immediately after the results.
When evaluating the stock, consider the bigger picture of valuation, business quality and the latest earnings. For more on these factors, read the full research report here (it’s free).