Natural gas producer Antero Resources (NYSE: AR) met Wall Street’s revenue expectations in Q3 2026, with revenue up 37.3% year on year to $1.56 billion. Its GAAP profit of $1.19 per share was 18.3% above analysts’ consensus estimates.
For more on Antero Resources, read our free full research report.
Antero Resources (AR) Q3 2026 highlights:
- Revenue $1.56 billion vs S&P analysts’ consensus estimates of $1.57 billion (37.3% year-on-year growth, in line)
- EPS (GAAP) $1.19 vs analysts’ consensus estimates of $1.01 (18.3% beat)
- Operating margin 25.1%, up from 6.8% in the same quarter last year
- Free cash flow margin 13.7%, up from 5.8% in the same quarter last year
- Oil production rose 2.9% year on year
- Market capitalization $12.94 billion
Michael Kennedy, CEO and president of Antero Resources, commented, "It has been a remarkable year for Antero. Over the last twelve months we have grown our net production by nearly 1 Bcfe/d though accretive transactions and efficiency gains. We also reduced our cost structure by approximately $0.40 per Mcfe, driving higher margins for our business. We accomplished all of this while also reducing our share count by over 5 million shares and maintaining leverage at approximately 1.0x. We believe our business strategy of product diversity, reduced cost structure and prudent hedging will decrease earnings volatility and drive peer-leading Free Cash Flow per share growth."
Revenue growth
Cyclical industries such as energy can make mediocre companies look great for a time, but a long-term view reveals which businesses can actually withstand and adapt to changing conditions. Antero Resources’s revenue grew at a sluggish 6.8% compounded annual growth rate over the last five years, falling short of the benchmark for the energy upstream and integrated energy sector.
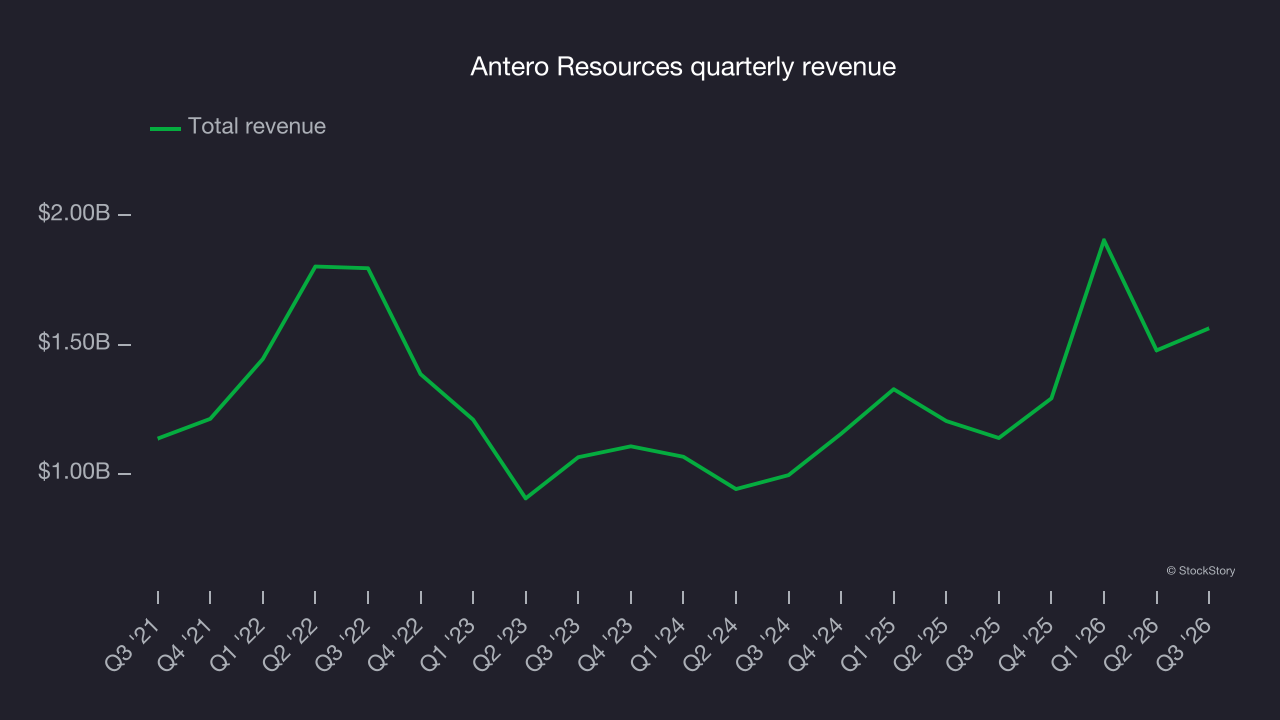
Even a long stretch in energy can be shaped by a single commodity cycle, so extending the view to ten years adds another perspective and reveals which companies are built to grow regardless of the pricing regime. Antero Resources’s annualized revenue growth of 9.2% over the last ten years is above its five-year trend.
While looking at revenue is important, it can also introduce noise around commodity prices and M&A. Analyzing production, on the other hand, highlights what is happening inside the asset base and whether the economic footprint of a company is expanding. Over the last two years, Antero Resources’s oil production averaged 12.6% year-on-year declines. On the other hand, its NGL production averaged 1.5% year-on-year growth. 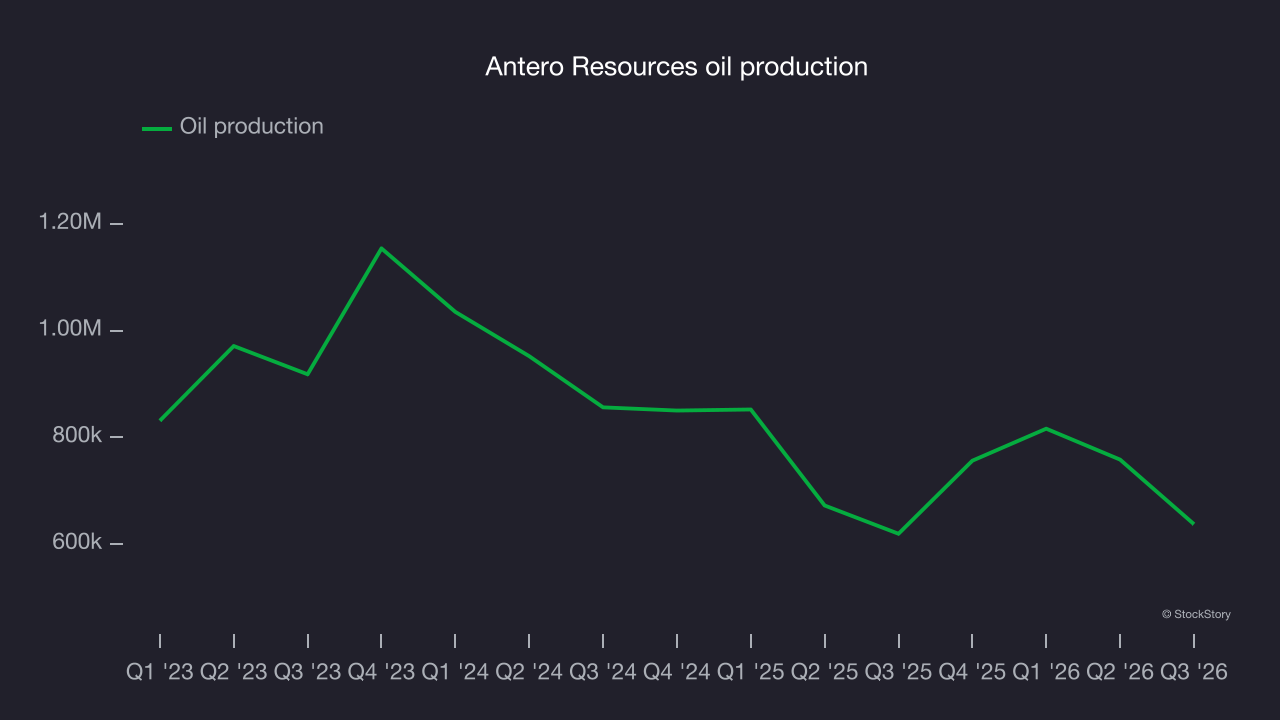
This quarter, Antero Resources’s year-on-year revenue growth of 37.3% was strong, and its $1.56 billion of revenue was in line with Wall Street’s consensus estimates. Antero Resources also reported modest year-on-year oil production growth of 2.9%.
Adjusted EBITDA margin
Antero Resources has done a decent job managing its cost base over the last five years. The company has produced an average EBITDA margin of 34.3%, higher than the broader energy upstream and integrated energy sector.
Looking at the trend in its profitability, Antero Resources’s EBITDA margin decreased by 10.4 percentage points over the last year. This raises questions about the company’s expense base because its revenue growth should have given it leverage on its fixed costs, resulting in better economies of scale and profitability.
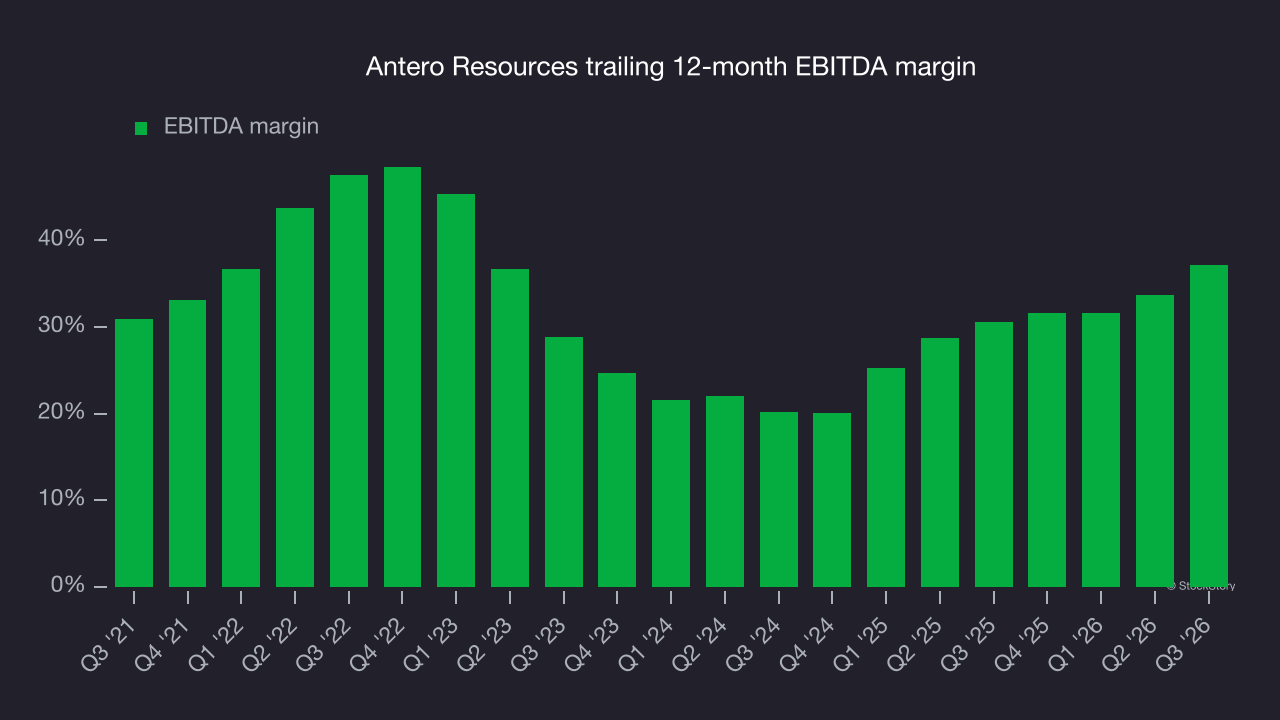
In Q3, Antero Resources generated an EBITDA margin of 41.4%, up 15.7 percentage points year on year. This increase was a positive development and shows it was more efficient. Its adjusted EBITDA fell short of Wall Street’s consensus estimates.
Free cash flow
Adjusted EBITDA shows how profitable a company’s existing wells are before financing and reinvestment decisions, but free cash flow shows how much value remains after paying the cost of replacing those wells. In upstream energy, production naturally declines over time, so companies must continuously reinvest just to stand still. A producer can report strong EBITDA margins yet generate little or no free cash flow if its wells decline quickly or if new drilling is expensive. Free cash flow therefore captures not only how efficiently a company produces hydrocarbons today, but also how costly it is to sustain that production into the future.
Antero Resources has shown strong cash profitability, driven by its attractive business model that enables it to reinvest or return capital to investors. The company’s free cash flow margin averaged 15.7% over the last five years, an impressive level for an upstream and integrated energy business.
The level of free cash flow is important, but its durability across cycles is just as critical. Consistent margins are far more valuable than volatile swings driven by commodity prices.
Antero Resources’s ratio of quarterly free cash flow volatility to Henry Hub gas-price volatility over the past five years was 2.7 (lower is better), indicating strong insulation from commodity swings. This stability supports superior capital access in downturns and positions Antero Resources to act as a consolidator when weaker peers are forced to retrench.
Why use free cash flow to assess stability relative to commodity prices? Why not compare revenue or EBITDA to Henry Hub natural gas prices in the case of Antero Resources? Because what ultimately matters is not how much revenue or profit a company earns when prices are high but how much cash it can generate when prices are low. Free cash flow is the superior metric because it includes everything from hedging effectiveness to growth and maintenance capex to management behavior during good times and bad.
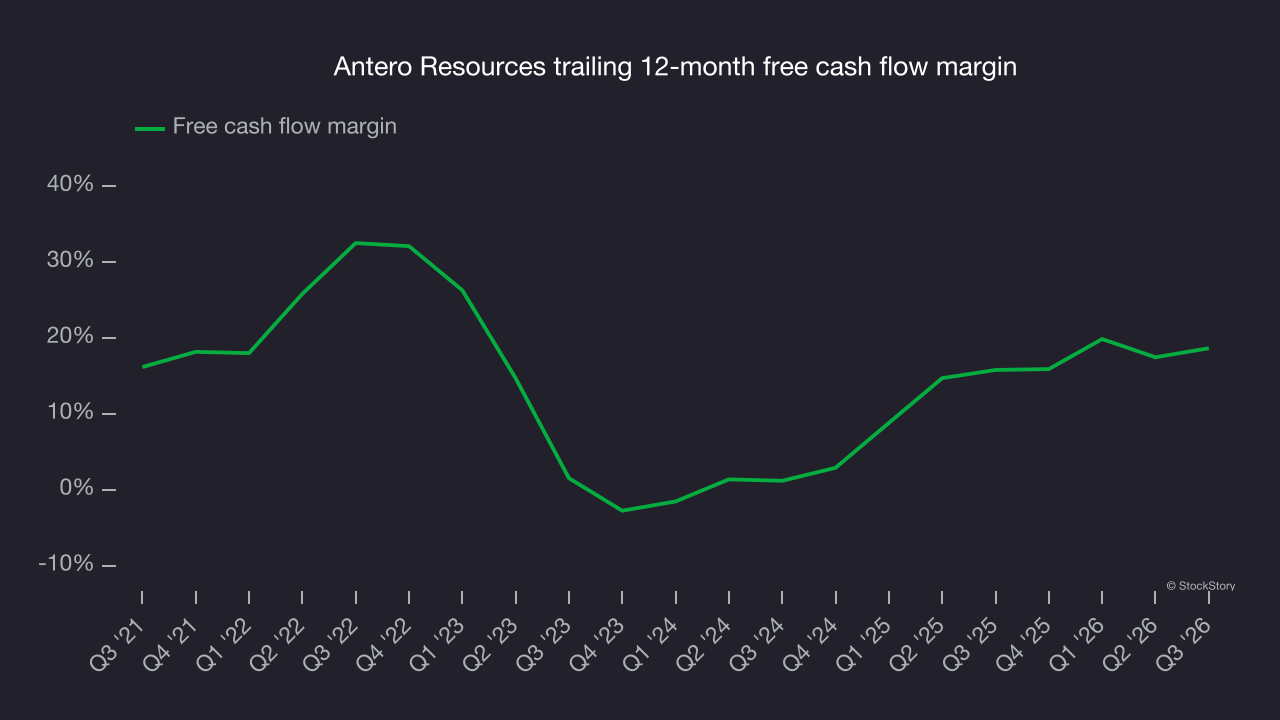
Antero Resources’s free cash flow totaled $214.8 million in Q3, equivalent to a 13.7% margin. This was a good result, with its margin 7.9 percentage points higher than in the same quarter last year, but the short-term result deserves less weight because investment needs can be seasonal, causing temporary swings. Long-term trends matter more than short-term fluctuations.
Key takeaways from Antero Resources’s Q3 results
Antero Resources delivered a decent quarter, with EPS above analysts’ consensus estimates and revenue in line. The earnings beat was a positive, but the stock remained flat at $41.90 immediately after the report.
The latest quarter matters, but longer-term business quality and valuation matter more when deciding whether to invest in this stock. Read the full research report here (it’s free).