

What a brutal six months it’s been for Onterris. The stock has dropped 31.5% and now trades at $14.31, rattling many shareholders. This was partly driven by its softer quarterly results and might have investors contemplating their next move.
Is now the time to buy Onterris, or should you be careful about including it in your portfolio? See what our analysts have to say in our full research report, it’s free.
Why is Onterris not exciting?
Despite the more favorable entry price, we don’t have much confidence in Onterris. Here are three reasons why there are better opportunities than ONT, plus one stock we’d rather own.
1. Projected revenue growth shows limited upside
Forecasted revenues by Wall Street analysts signal a company’s potential. Predictions may not always be accurate, but accelerating growth typically boosts valuation multiples and stock prices while slowing growth does the opposite.
Over the next 12 months, sell-side analysts expect Onterris’s revenue to stall, according to S&P, a deceleration versus its 10.8% annualized growth for the past five years. This projection is underwhelming and suggests its products and services will see some demand headwinds.
2. Operating losses sound the alarm
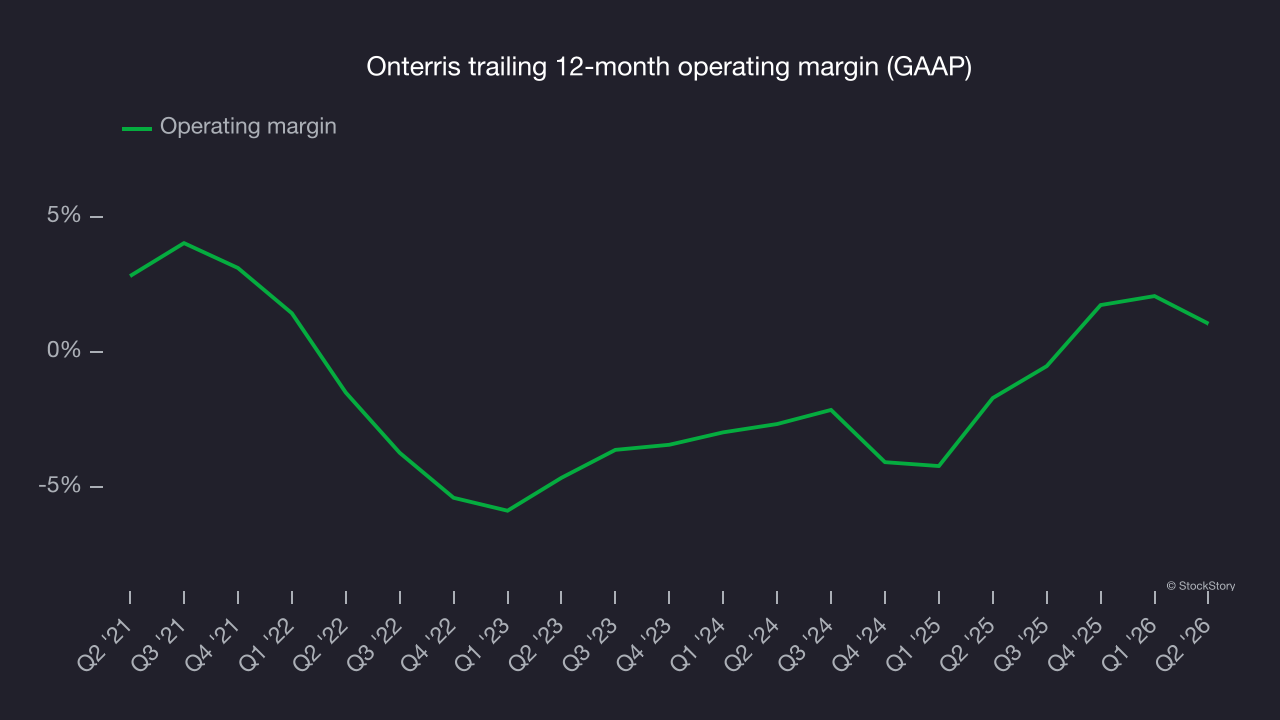
Operating margin is a key measure of profitability. Think of it as net income - the bottom line - excluding the impact of taxes and interest on debt, which are less connected to business fundamentals.
Although Onterris was profitable this quarter from an operational perspective, it’s generally struggled over a longer time period. Its expensive cost structure has contributed to an average operating margin of negative 1.7% over the last five years. Unprofitable industrials companies require extra attention because they could get caught swimming naked when the tide goes out. It’s hard to trust that the business can endure a full cycle.
3. Previous growth initiatives have lost money
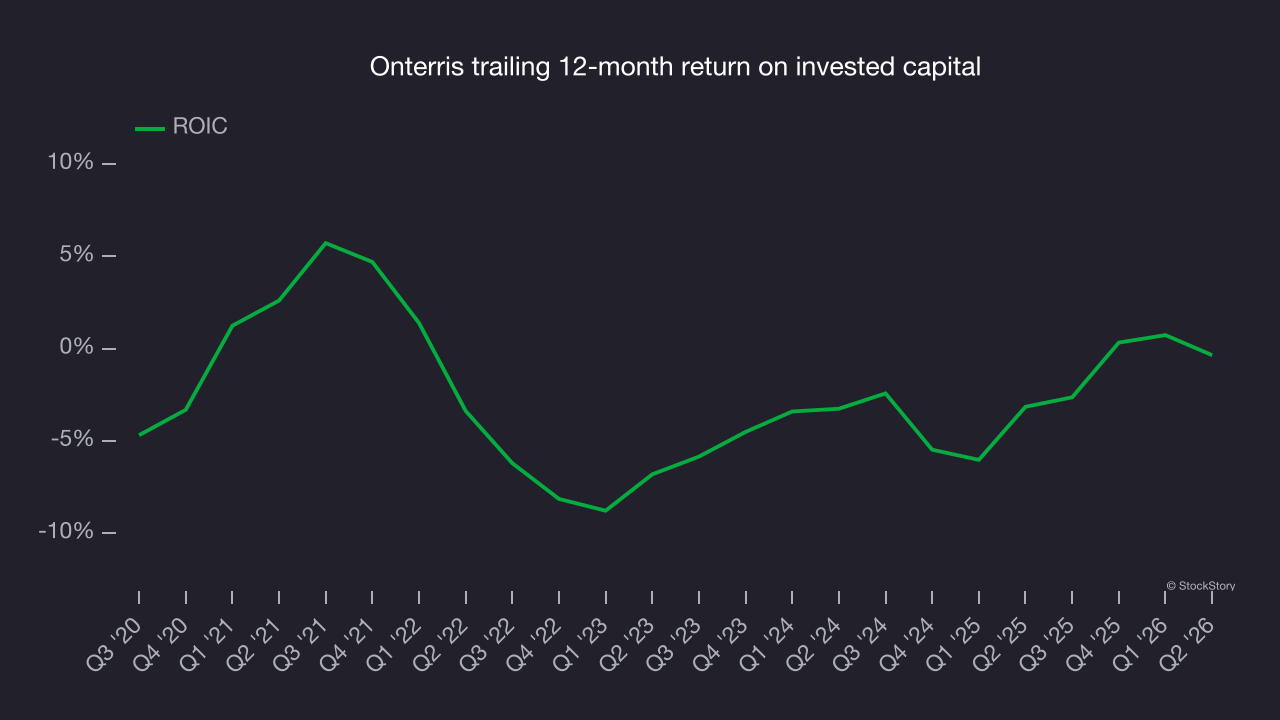
Growth gives us insight into a company’s long-term potential, but how capital-efficient was that growth? A company’s ROIC explains this by showing how much operating profit it makes compared to the money it has raised (debt and equity).
Onterris’s five-year average ROIC was negative 3.4%, meaning management lost money while trying to expand the business. Its returns were among the worst in the industrials sector.
Final judgment
Onterris isn’t a terrible business, but it doesn’t pass our bar. Following the recent decline, the stock trades at 10.4× forward P/E (or $14.31 per share). This valuation is reasonable, but the company’s shakier fundamentals present too much downside risk. We’re pretty confident there are superior stocks to buy right now. We’d suggest looking at one of Charlie Munger’s all-time favorite businesses.
Stocks we like more than Onterris
ALSO WORTH WATCHING: Top 5 Momentum Stocks. The best time to own a great stock is when the market is finally noticing it. These aren’t just high-quality businesses. Something is happening with them right now. Elite fundamentals meet near-term momentum — both boxes checked at the same time.
Find out which stocks our AI platform is flagging this week. See this week’s Strong Momentum stocks — FREE. Get Our Strong Momentum Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Kadant (+214% between June 2020 and June 2025). Find your next big winner with StockStory today.




