
Coconut water company The Vita Coco Company (NASDAQ: COCO) reported Q3 2026 results beating Wall Street’s revenue expectations, with sales up 33.7% year on year to $243.8 million. The company’s full-year revenue guidance of $815 million at the midpoint came in 1.5% above analysts’ estimates. Its GAAP profit of $0.58 per share was 27.3% above analysts’ consensus estimates.
Is now the time to buy Vita Coco? Find out by accessing our full research report, it’s free.
Vita Coco (COCO) Q3 2026 highlights:
- Revenue: $243.8 million vs analyst estimates of $229.8 million (33.7% year-on-year growth, 6.1% beat)
- EPS (GAAP): $0.58 vs analyst estimates of $0.46 (27.3% beat)
- Adjusted EBITDA: $53.16 million vs analyst estimates of $39.28 million (21.8% margin, 35.3% beat)
- The company lifted its revenue guidance for the full year to $815 million at the midpoint from $797.5 million, a 2.2% increase
- EBITDA guidance for the full year is $172.5 million at the midpoint, above analyst estimates of $163 million
- Operating Margin: 18.6%, up from 15.3% in the same quarter last year
- Free Cash Flow Margin: 22.6%, up from 19.6% in the same quarter last year
- Market Capitalization: $3.76 billion
Martin Roper, the Company’s Chief Executive Officer, said, “Our strong third quarter net sales growth was driven by robust branded retail growth in all our major markets, and by strong growth in private label shipments, reflecting healthy category growth and the addition of Copra's super premium products. Excluding the impact of Copra, the underlying 18% organic net sales growth of our business remained very strong, exceeding our expectations. Consumer demand is very healthy, and we are therefore raising our full year Net Sales and Adjusted EBITDA guidance.”
Company overview
Founded in 2004 followed by a 2021 IPO, The Vita Coco Company (NASDAQ: COCO) offers coconut water products that are a natural way to quench thirst.
Revenue growth
Examining a company’s long-term performance can provide clues about its quality. Any business can put up a good quarter or two, but the best consistently grow over the long haul.
With $767.5 million in revenue over the past 12 months, Vita Coco is a small consumer staples company, which sometimes brings disadvantages compared to larger competitors benefiting from economies of scale and negotiating leverage with retailers. On the bright side, it can grow faster because it has a longer list of untapped store chains to sell into.
As you can see below, Vita Coco grew its sales at an impressive 17% compounded annual growth rate over the last three years as consumers bought more of its products.
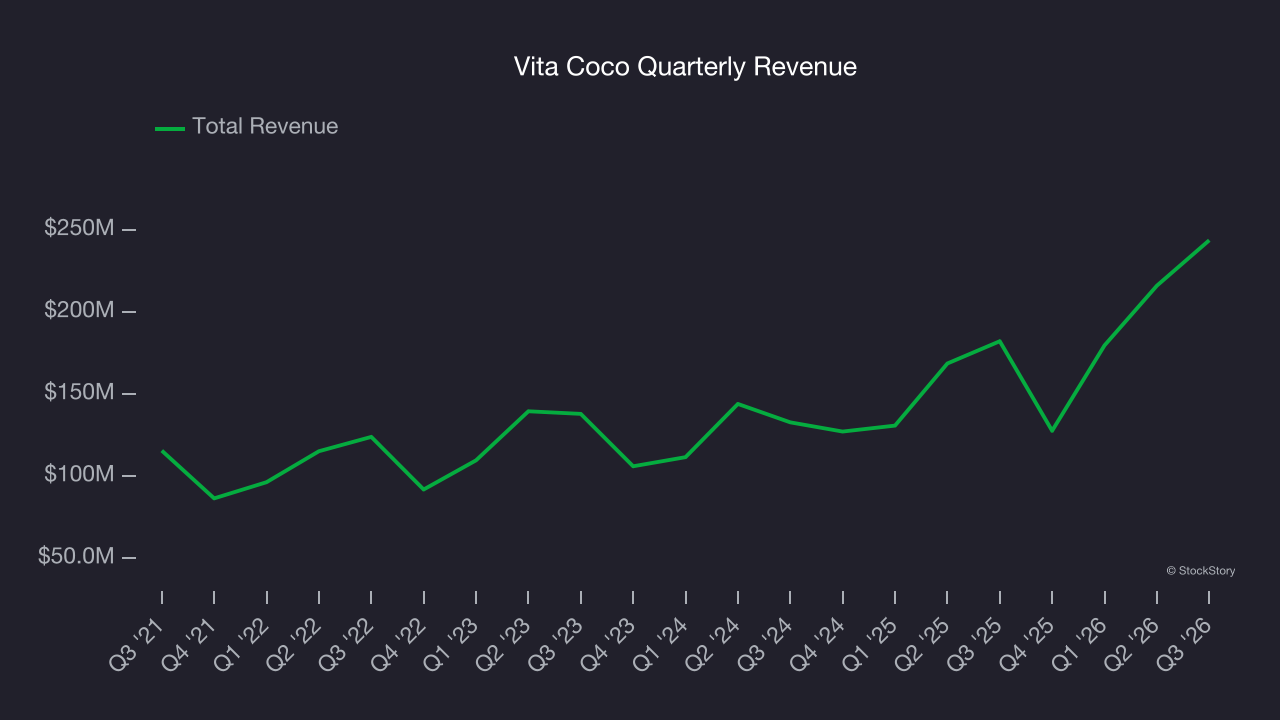
This quarter, Vita Coco reported wonderful year-on-year revenue growth of 33.7%, and its $243.8 million of revenue exceeded Wall Street’s estimates by 6.1%.
Looking ahead, sell-side analysts expect revenue to grow 24.1% over the next 12 months, an acceleration versus the last three years. This projection is eye-popping and suggests its newer products will fuel better top-line performance.
ALSO WORTH WATCHING: Nvidia’s Quiet Partner. Nvidia’s chips cost a hundred grand. The connectors that make them work cost even more. One company makes them all.
Every AI server needs specialized infrastructure the chip companies don’t make. High-speed cables. Power connectors. Thermal sensors. This 90-year-old company built a monopoly on it. The AI boom just started. This stock is still flying under the radar. Claim The Stock Ticker Here for FREE.
Cash is king
If you’ve followed StockStory for a while, you know we emphasize free cash flow. Why, you ask? We believe that in the end, cash is king, and you can’t use accounting profits to pay the bills.
Vita Coco has shown terrific cash profitability, driven by its lucrative business model that enables it to reinvest, return capital to investors, and stay ahead of the competition. The company’s free cash flow margin was among the best in the consumer staples sector, averaging 14.3% over the last two years.
Taking a step back, we can see that Vita Coco’s margin expanded by 10.1 percentage points over the last year. This is encouraging, and we can see it became a less capital-intensive business because its free cash flow profitability rose more than its operating profitability.
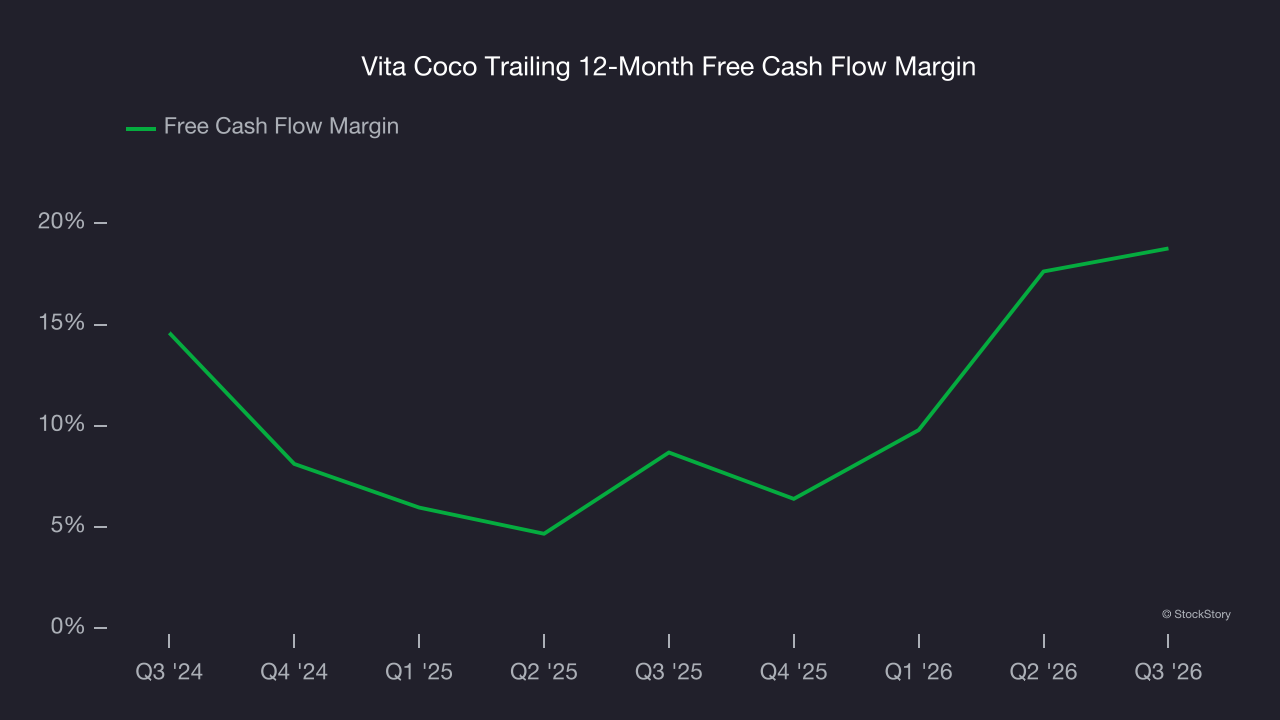
Vita Coco’s free cash flow clocked in at $55.22 million in Q3, equivalent to a 22.6% margin. This result was good as its margin was 3.1 percentage points higher than in the same quarter last year, building on its favorable historical trend.
Key takeaways from Vita Coco’s Q3 results
We were impressed by how significantly Vita Coco blew past analysts’ EBITDA expectations this quarter. We were also excited its revenue outperformed Wall Street’s estimates by a wide margin. Zooming out, we think this was a good print with some key areas of upside. Investors were likely hoping for more, and shares traded down 2% to $62.22 immediately following the results.
Should you buy the stock or not? What happened in the latest quarter matters, but not as much as longer-term business quality and valuation, when deciding whether to invest in this stock. We cover that in our actionable full research report which you can read here (it’s free).