
Pawn store operator FirstCash Holdings (NASDAQ: FCFS) announced better-than-expected revenue in Q3 2026, with sales up 17.7% year on year to $1.10 billion. Its non-GAAP profit of $2.68 per share was 1.8% above analysts’ consensus estimates.
Is now the time to buy FirstCash? Find out by accessing our full research report, it’s free.
FirstCash (FCFS) Q3 2026 highlights:
- Revenue: $1.10 billion vs analyst estimates of $1.07 billion (17.7% year-on-year growth, 2.4% beat)
- Pre-tax Profit: $138.7 million (12.6% margin)
- Adjusted EPS: $2.68 vs analyst estimates of $2.63 (1.8% beat)
- Market Capitalization: $9.40 billion
“FirstCash has set new records for revenue and earnings in each quarter this year. For the trailing twelve months, revenues are now $4.3 billion, net income totals $406 million and adjusted EBITDA totals $835 million. The impressive earnings growth continues to drive increased operating cash flows as well, providing ample capacity for shareholder returns through stock repurchases and cash dividends. More importantly, we remain committed to expanding our industry-leading global footprint through accretive pawnshop acquisitions and new store openings in each geographic segment,” concluded Mr. Wessel.
Company overview
Offering a financial lifeline to the unbanked and credit-constrained since 1988, FirstCash (NASDAQ: FCFS) operates pawn stores across the U.S. and Latin America while also providing retail point-of-sale payment solutions for credit-constrained consumers.
Revenue growth
A company’s long-term sales performance is one signal of its overall quality. Even a bad business can shine for one or two quarters, but a top-tier one grows for years. Luckily, FirstCash’s revenue grew at an exceptional 21.9% compounded annual growth rate over the last five years. Its growth beat the average financials company and shows its offerings resonate with customers, a helpful starting point for our analysis.
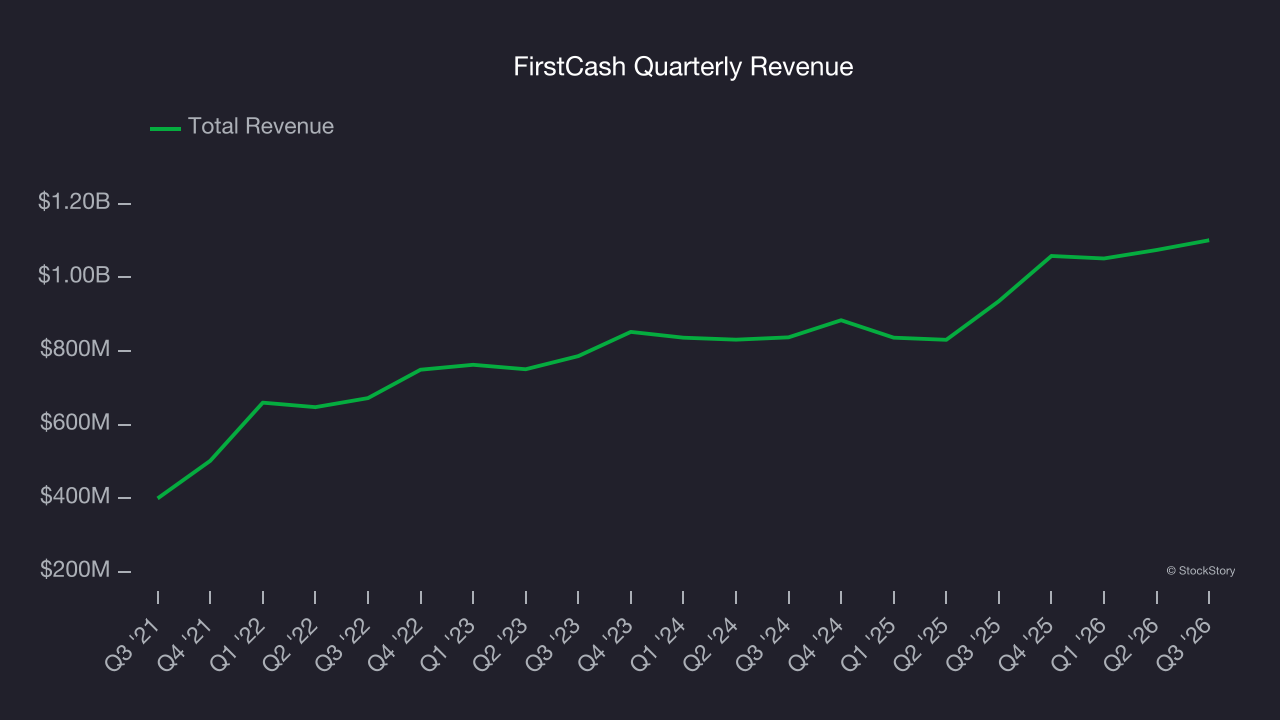
Long-term growth is the most important, but within financials, a half-decade historical view may miss recent interest rate changes and market returns. FirstCash’s annualized revenue growth of 13% over the last two years is below its five-year trend, but we still think the results suggest healthy demand. 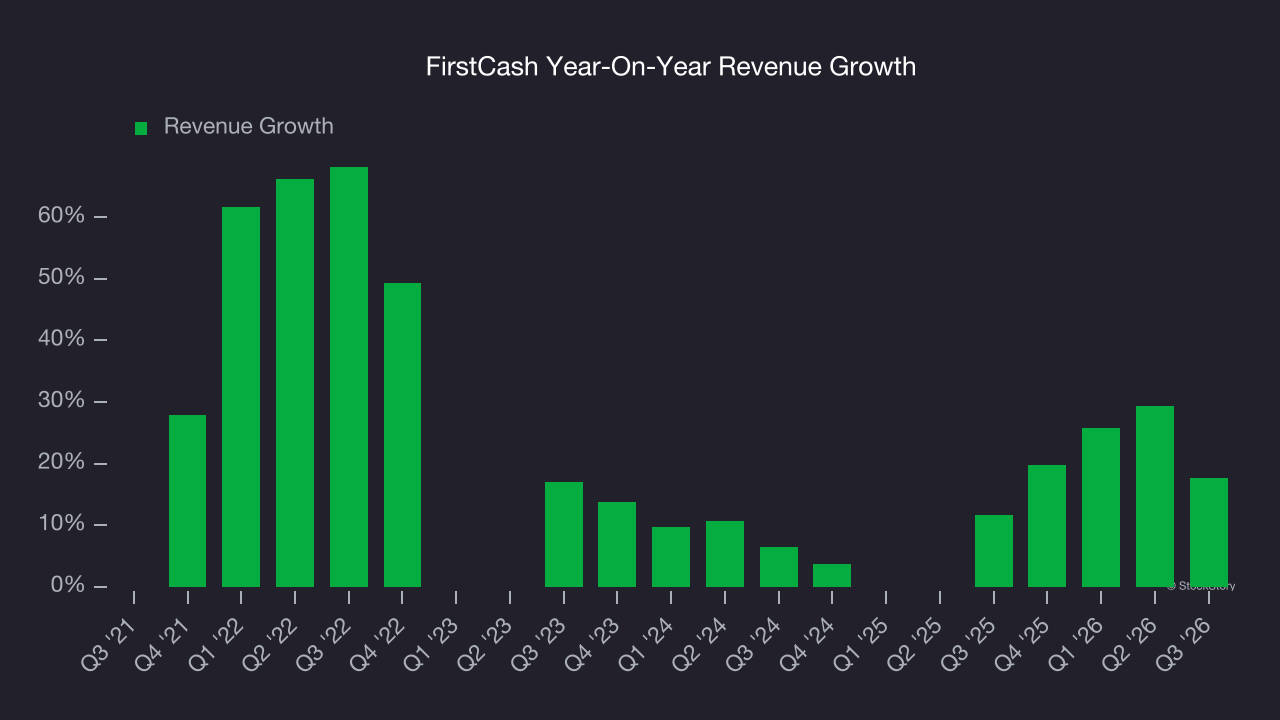 Note: Quarters not shown were determined to be outliers because they were impacted by outsized investment gains/losses that are not indicative of the recurring fundamentals of the business.
This quarter, FirstCash reported year-on-year revenue growth of 17.7%, and its $1.10 billion of revenue exceeded Wall Street’s estimates by 2.4%.
ONE MORE THING: The $21 AI Application Stock Wall Street Forgot. While Wall Street obsesses over who’s building AI, one company is already using it to print money. And nobody’s paying attention.
AI chip stocks trade at ridiculous valuations. This company processes a trillion consumer signals monthly using AI and trades at a third of the price. The gap won’t last. The institutions will figure it out. You need to see this first. Read the FREE Report Before They Notice.
Key takeaways from FirstCash’s Q3 results
It was encouraging to see FirstCash beat analysts’ revenue expectations this quarter. Overall, this print had some key positives. The stock remained flat at $216.75 immediately following the results.
So do we think FirstCash is an attractive buy at the current price? What happened in the latest quarter matters, but not as much as longer-term business quality and valuation, when deciding whether to invest in this stock. We cover that in our actionable full research report which you can read here (it’s free).