
Over the past six months, Bristow Group’s stock price fell to $38.65. Shareholders have lost 18.7% of their capital, which is disappointing considering the S&P 500 has climbed by 8.9%. This might have investors contemplating their next move.
Is now the time to buy Bristow Group, or should you be careful about including it in your portfolio? Check out our in-depth research report to see what our analysts have to say, it’s free.
Why Do We Think Bristow Group Will Underperform?
Even with the cheaper entry price, we’re sitting this one out for now. Here are three reasons why there are better opportunities than VTOL, plus one stock we’d rather own.
1. Long-Term Revenue Growth Disappoints
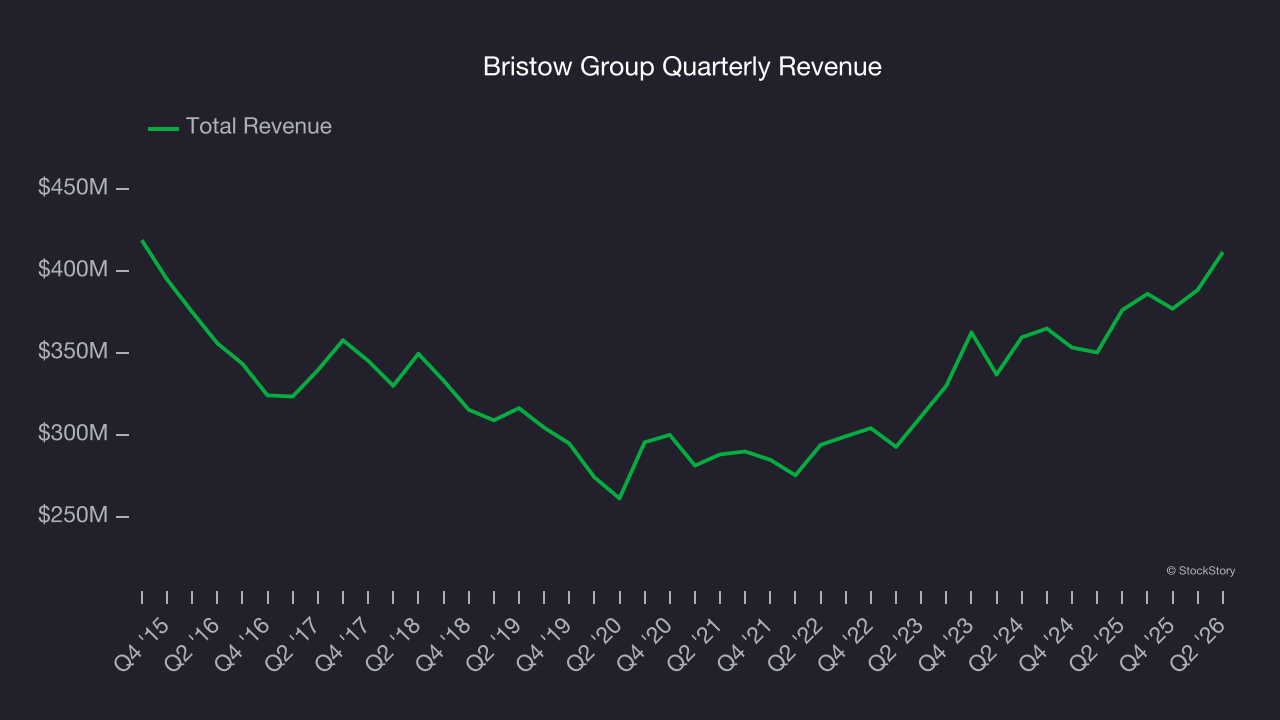
Cyclical sectors like Energy often flatter weaker operators during favorable price environments, but a longer-term lens separates those from businesses that can consistently perform across market cycles. Regrettably, Bristow Group’s sales grew at a sluggish 6.1% compounded annual growth rate over the last five years. This was below our standard for the energy upstream and integrated energy sector.
2. Fewer Distribution Channels Limit Its Ceiling
The size of the revenue base is a way to assess topline, and it tells an investor whether an Energy producer has crossed the line between being a more vulnerable commodity taker and a durable operating platform. Scaled businesses tend to produce and generate revenue from many wells, pads, takeaway routes, and geographies, not just a single field or drilling program.
Bristow Group’s $1.56 billion of revenue in the last year is pretty small for the industry, suggesting the company hasn’t hit a level of diversification where investors can sleep easy at night.
3. Breakeven Free Cash Flow Limits Reinvestment Potential
Free cash flow isn’t a prominently featured metric in company financials and earnings releases, but we think it’s telling because it accounts for all operating and capital expenses, making it tough to manipulate. Cash is king.
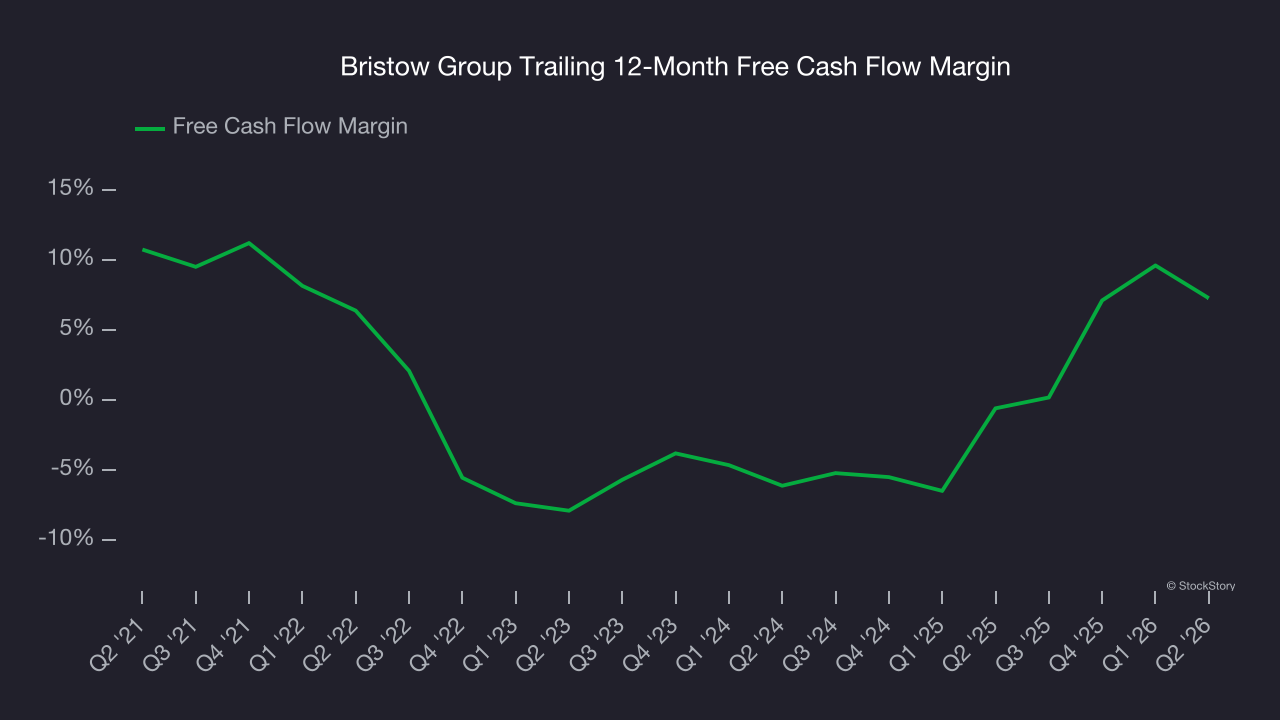
Bristow Group broke even from a free cash flow perspective over the last five years, giving the company limited opportunities to return capital to shareholders.
Final Judgment
We see the value of companies helping consumers, but in the case of Bristow Group, we’re out. Following the recent decline, the stock trades at 5.3× forward EV-to-EBITDA (or $38.65 per share). This valuation tells us it’s a bit of a market darling with a lot of good news priced in - we think there are better opportunities elsewhere. We’d suggest looking at one of Charlie Munger’s all-time favorite businesses.
Stocks We Would Buy Instead of Bristow Group
ONE MORE THING: Top 6 Stocks for This Week. This market is separating quality stocks from expensive ones fast. AI is taking down whole sectors with no warning. In a rotation this fast, you need more than a list of good companies.
Our AI system flagged Palantir before it ran 1,662% between October 2022 and February 2026. AppLovin before it ran 753% between February 2024 and February 2026. Nvidia before it ran 1,178% between January 2023 and February 2026. Each week it produces 6 new names that pass the same tests. Get Our Top 6 Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Tecnoglass (+1,552% between June 2020 and June 2025). Find your next big winner with StockStory today.