
The past six months have been a windfall for Amplitude’s shareholders. The company’s stock price has jumped 116%, hitting $15.28 per share. This was partly thanks to its solid quarterly results, and the performance may have investors wondering how to approach the situation.
Is now the time to buy Amplitude, or should you be careful about including it in your portfolio? Dive into our full research report to see our analyst team’s opinion, it’s free.
Why Is Amplitude Not Exciting?
Despite the momentum, we’re sitting this one out for now. Here are three reasons why there are better opportunities than AMPL, plus one stock we’d rather own.
1. Customer Churn Hurts Long-Term Outlook
One of the best parts about the software-as-a-service business model (and a reason why they trade at high valuation multiples) is that customers typically spend more on a company’s products and services over time.
Amplitude’s net revenue retention rate, a key performance metric measuring how much money existing customers from a year ago are spending today, was 105% in Q2. This means Amplitude would’ve grown its revenue by 5% even if it didn’t win any new customers over the last 12 months.
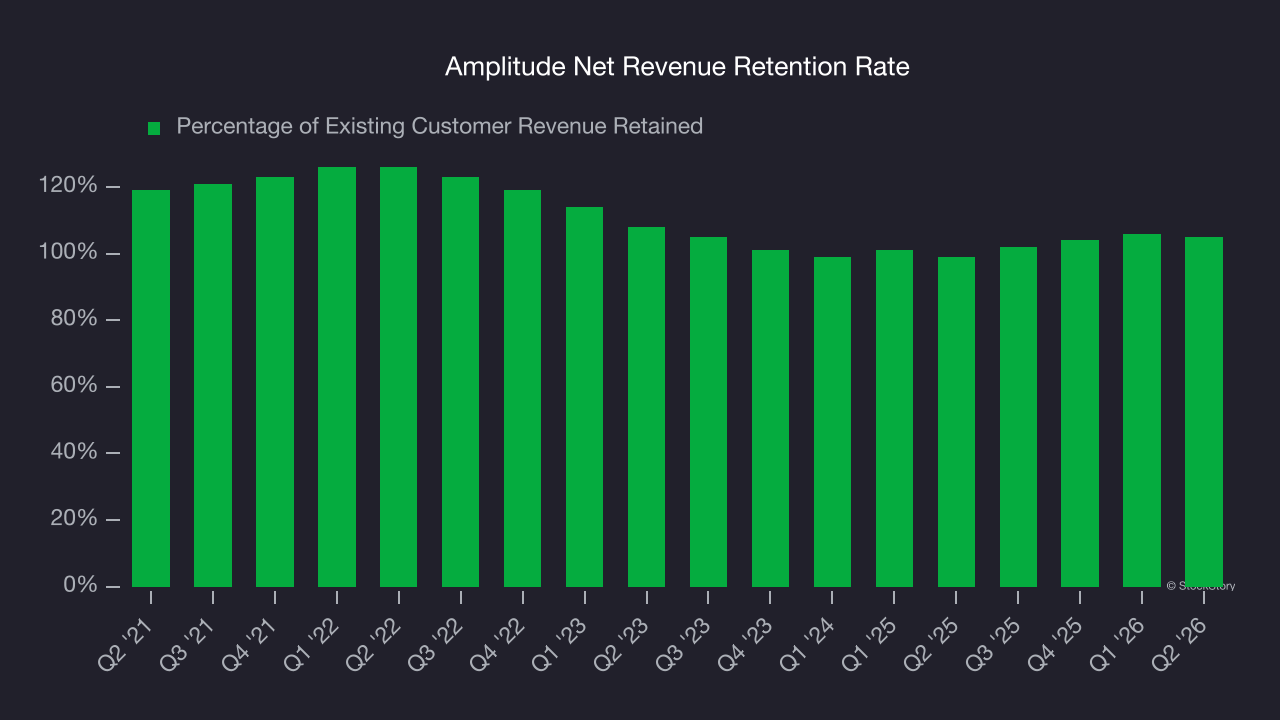
Significantly up from the last quarter, Amplitude has an adequate net retention rate, showing us that it generally keeps customers but lags behind the best SaaS businesses, which routinely post net retention rates of 120%+.
2. Operating Losses Sound the Alarm
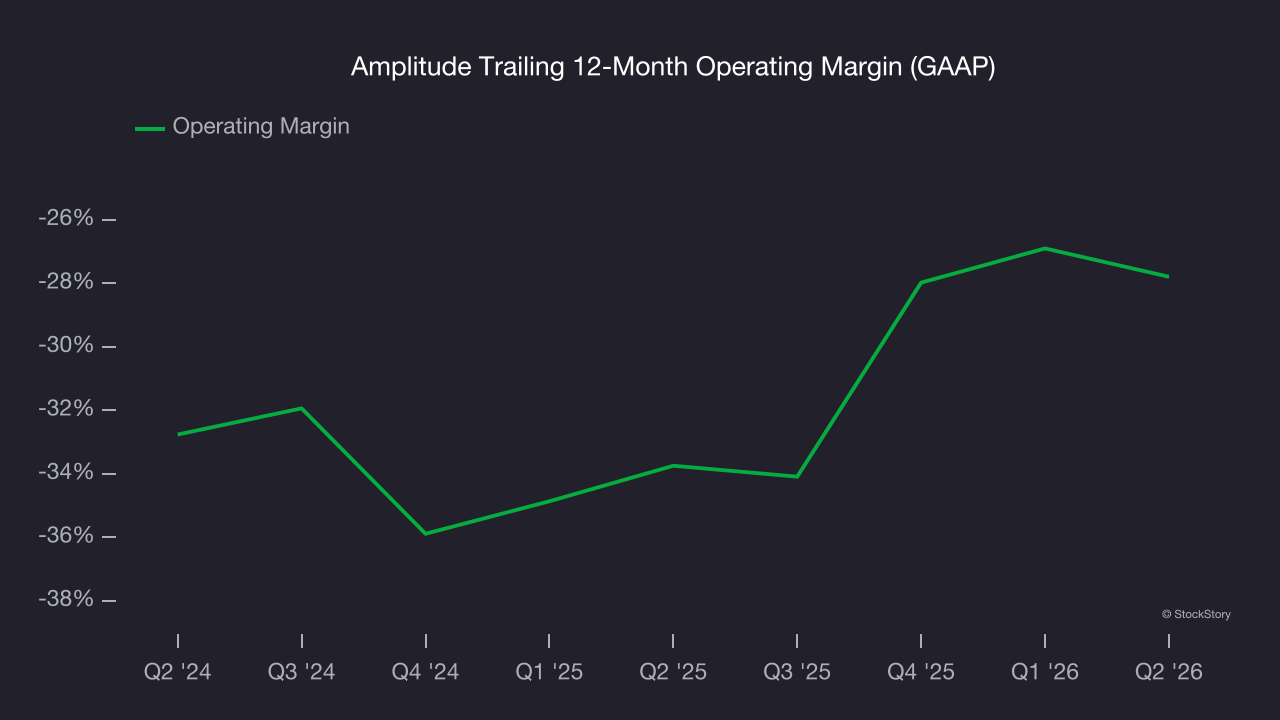
Many software businesses adjust their profits for stock-based compensation (SBC), but we prioritize GAAP operating margin because SBC is a real expense used to attract and retain engineering and sales talent. This metric shows how much revenue remains after accounting for all core expenses — everything from the cost of goods sold to sales and R&D.
Amplitude’s expensive cost structure has contributed to an average operating margin of negative 27.8% over the last year. Unprofitable, high-growth software companies require extra attention because they spend heaps of money to capture market share. As seen in its fast historical revenue growth, this strategy seems to have worked so far, but it’s unclear what would happen if Amplitude reeled back its investments. Wall Street seems to be optimistic about its growth, but we have some doubts.
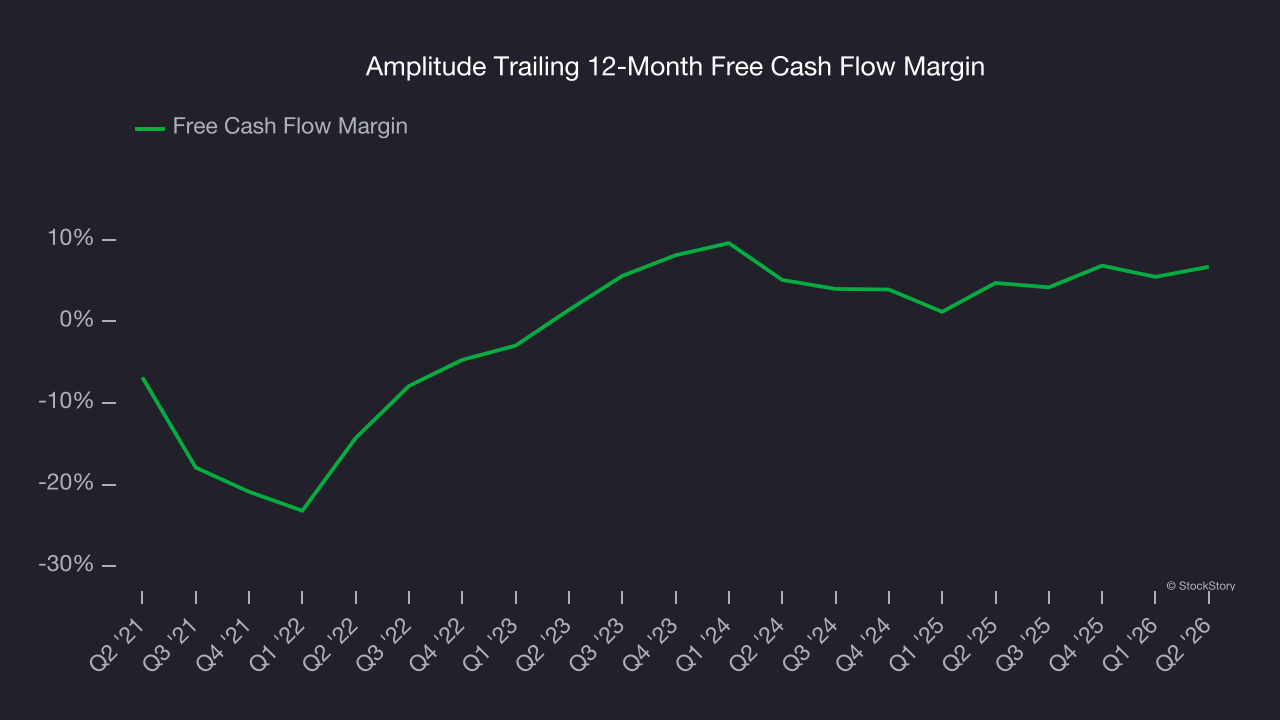
3. Mediocre Free Cash Flow Margin Limits Reinvestment Potential
If you’ve followed StockStory for a while, you know we emphasize free cash flow. Why, you ask? We believe that in the end, cash is king, and you can’t use accounting profits to pay the bills.
Amplitude has shown weak cash profitability relative to peers over the last year, giving the company fewer opportunities to return capital to shareholders. Its free cash flow margin averaged 6.7%, below what we’d expect for a software business.
Final Judgment
Amplitude isn’t a terrible business, but it isn’t one of our picks. After the recent rally, the stock trades at 4.6× forward price-to-sales (or $15.28 per share). While this valuation is reasonable, we don’t really see a big opportunity at the moment. We’re fairly confident there are better stocks to buy right now. We’d suggest looking at a dominant aerospace business that has perfected its M&A strategy.
High-Quality Stocks for All Market Conditions
ONE MORE THING: Top 5 Growth Stocks. The biggest stock winners almost always had one thing in common before they ran. Revenue growing like crazy. Meta. CrowdStrike. Broadcom. Our AI flagged all three. They returned 315%, 314%, and 455%, respectively.
Find out which 5 stocks it’s flagging this month — FREE. Get Our Top 5 Growth Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Comfort Systems (+1,154% between June 2020 and June 2025). Find your next big winner with StockStory today.