
Let’s dig into the relative performance of Vital Farms (NASDAQ: VITL) and its peers as we unravel the now-completed Q2 perishable food earnings season.
The perishable food industry is diverse, encompassing large-scale producers and distributors to specialty and artisanal brands. These companies sell produce, dairy products, meats, and baked goods and have become integral to serving modern American consumers who prioritize freshness, quality, and nutritional value. Investing in perishable food stocks presents both opportunities and challenges. While the perishable nature of products can introduce risks related to supply chain management and shelf life, it also creates a constant demand driven by the necessity for fresh food. Companies that can efficiently manage inventory, distribution, and quality control are well-positioned to thrive in this competitive market. Navigating the perishable food industry requires adherence to strict food safety standards, regulations, and labeling requirements.
The 10 perishable food stocks we track reported a mixed Q2. As a group, revenues beat analysts’ consensus estimates by 1.4% while next quarter’s revenue guidance was 4.7% below.
Amidst this news, share prices of the companies have had a rough stretch. On average, they are down 10.7% since the latest earnings results.
Vital Farms (NASDAQ: VITL)
With an emphasis on ethically produced products, Vital Farms (NASDAQ: VITL) specializes in pasture-raised eggs and butter.
Vital Farms reported revenues of $166 million, down 10.1% year on year. This print exceeded analysts’ expectations by 0.8%. Overall, it was a satisfactory quarter for the company with full-year EBITDA guidance exceeding analysts’ expectations but a significant miss of analysts’ EBITDA estimates.
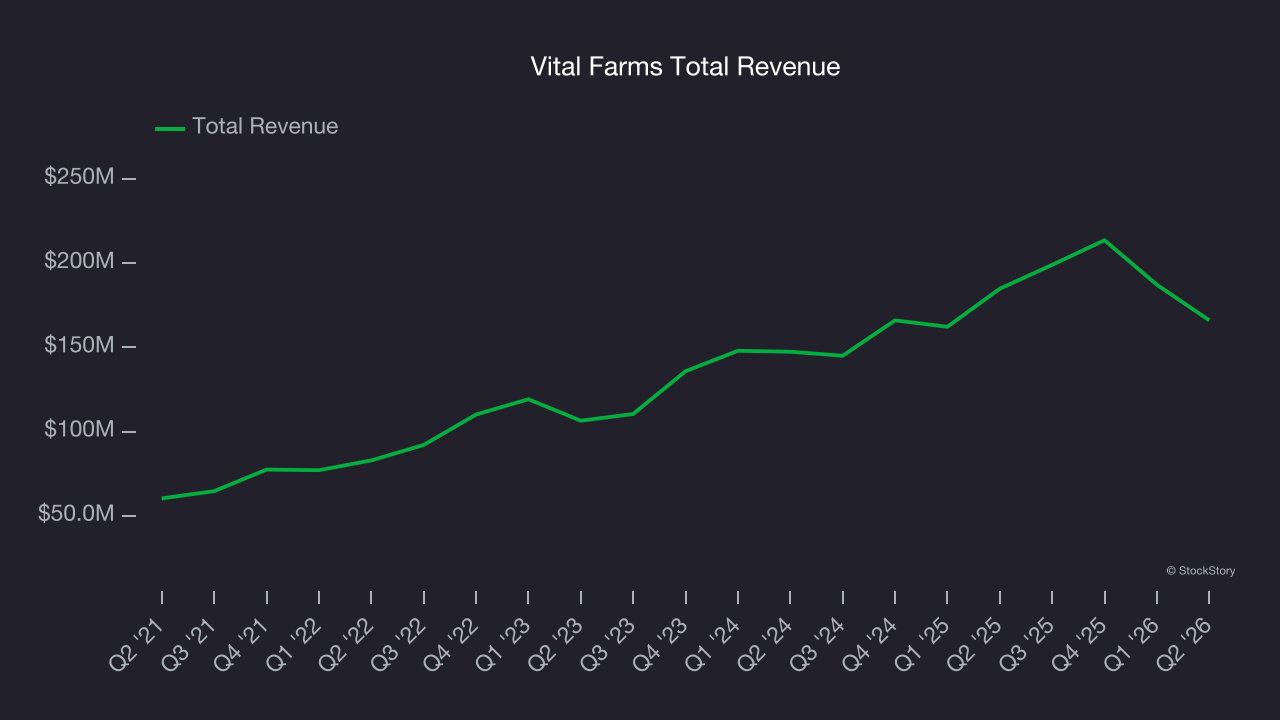
Vital Farms achieved the highest full-year guidance raise in the group. Even though it had a relatively good quarter, the market seems discontent with the results. The stock is down 29.7% since reporting and currently trades at $8.61.
Is now the time to buy Vital Farms? Access our full analysis of the earnings results here, it’s free.
Best Q2: Mission Produce (NASDAQ: AVO)
Founded in 1983 in California, Mission Produce (NASDAQ: AVO) grows, packages, and distributes avocados.
Mission Produce reported revenues of $450 million, up 25.8% year on year, outperforming analysts’ expectations by 22.4%. The business had a stunning quarter with a beat of analysts’ EPS estimates and an impressive beat of analysts’ EBITDA estimates.
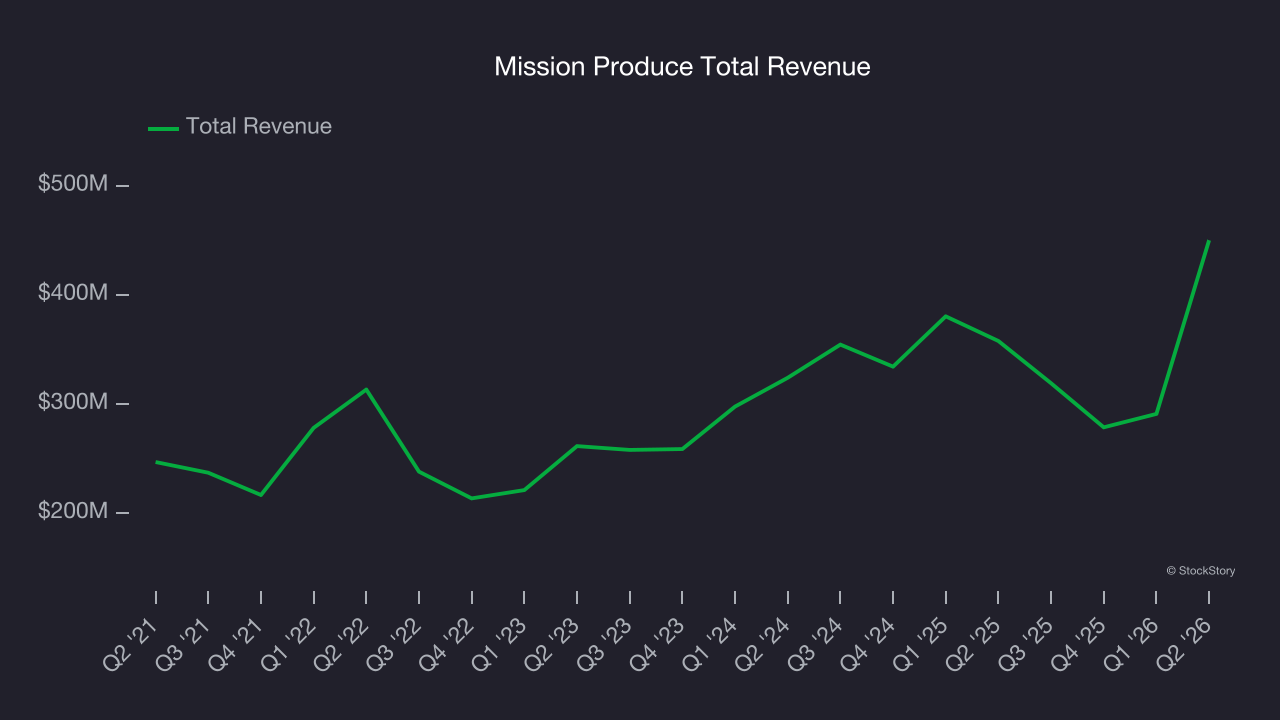
Mission Produce pulled off the biggest analyst estimate beat and fastest revenue growth of the whole group. Although it had a fine quarter compared to its peers, the market seems unhappy with the results as the stock is down 6.1% since reporting. It currently trades at $12.09.
Is now the time to buy Mission Produce? Access our full analysis of the earnings results here, it’s free.
Weakest Q2: Cal-Maine (NASDAQ: CALM)
Known for brands such as Egg-Land’s Best and Land O’ Lakes, Cal-Maine (NASDAQ: CALM) produces, packages, and distributes eggs.
Cal-Maine reported revenues of $539.6 million, down 41.5% year on year, falling short of analysts’ expectations by 3.9%. It was a disappointing quarter as it posted a significant miss of analysts’ gross margin estimates and a significant miss of analysts’ EPS estimates.
Cal-Maine delivered the slowest revenue growth among its peers. As expected, the stock is down 7.4% since the results and currently trades at $63.46.
Read our full analysis of Cal-Maine’s results here.
Beyond Meat (NASDAQ: BYND)
A pioneer at the forefront of the plant-based protein revolution, Beyond Meat (NASDAQ: BYND) is a food company specializing in alternatives to traditional meat products.
Beyond Meat reported revenues of $68.83 million, down 8.2% year on year. This result beat analysts’ expectations by 3.5%. However, it was a softer quarter as it recorded a significant miss of analysts’ EBITDA estimates and a significant miss of analysts’ EPS estimates.
The stock is down 61.1% since reporting and currently trades at $7.12.
Read our full, actionable report on Beyond Meat here, it’s free.
Del Monte Corporation (NYSE: DMC)
Translating to "of the mountain" in Spanish, Del Monte Corporation (NYSE: DMC) is a leader in providing high-quality, sustainably grown fresh fruits and vegetables.
Del Monte Corporation reported revenues of $1.22 billion, up 3.1% year on year. This print lagged analysts’ expectations by 6.6%. Aside from that, it was a strong quarter as it recorded an impressive beat of analysts’ gross margin estimates and a solid beat of analysts’ EBITDA estimates.
Del Monte Corporation had the weakest performance against analyst estimates in the group. The stock is up 4% since reporting and currently trades at $29.87.
Read our full, actionable report on Del Monte Corporation here, it’s free.
Market Update
Over the past year, investors have been forced to repeatedly answer the same question: what is the market’s biggest risk? The answer has changed several times, and each shift has reshaped market leadership.
Late in 2025 and early 2026, artificial intelligence became the market’s primary uncertainty. Investors questioned whether AI would erode software pricing power and weaken competitive moats as AI made it easier to replicate once-differentiated products.
By the spring, technology took a back seat to geopolitics. The U.S. conflict with Iran briefly became the market’s dominant narrative, raising concerns about oil prices, inflation, and global growth. But as energy markets remained orderly and fears of a prolonged supply disruption faded, investors quickly turned their focus back to fundamentals.
Want to invest in winners with rock-solid fundamentals? Check out our 9 Best Market-Beating Stocks and add them to your watchlist. These companies are poised for growth regardless of the political or macroeconomic climate.