First Citizens BancShares trades at $2,097 per share and has stayed right on track with the overall market, gaining 5.8% over the last six months. At the same time, the S&P 500 has returned 9.7%.
Is now the time to buy First Citizens BancShares, or should you be careful about including it in your portfolio? See what our analysts have to say in our full research report, it’s free.
Why Is First Citizens BancShares Not Exciting?
We don’t have much confidence in First Citizens BancShares. Here are three reasons why there are better opportunities than FCNCA, plus one stock we’d rather own.
1. Revenue Tumbling Downwards
Long-term growth is the most important, but within financials, a stretched historical view may miss recent interest rate changes and market returns. First Citizens BancShares’s recent performance marks a sharp pivot from its five-year trend as its revenue has shown annualized declines of 2.9% over the last two years. 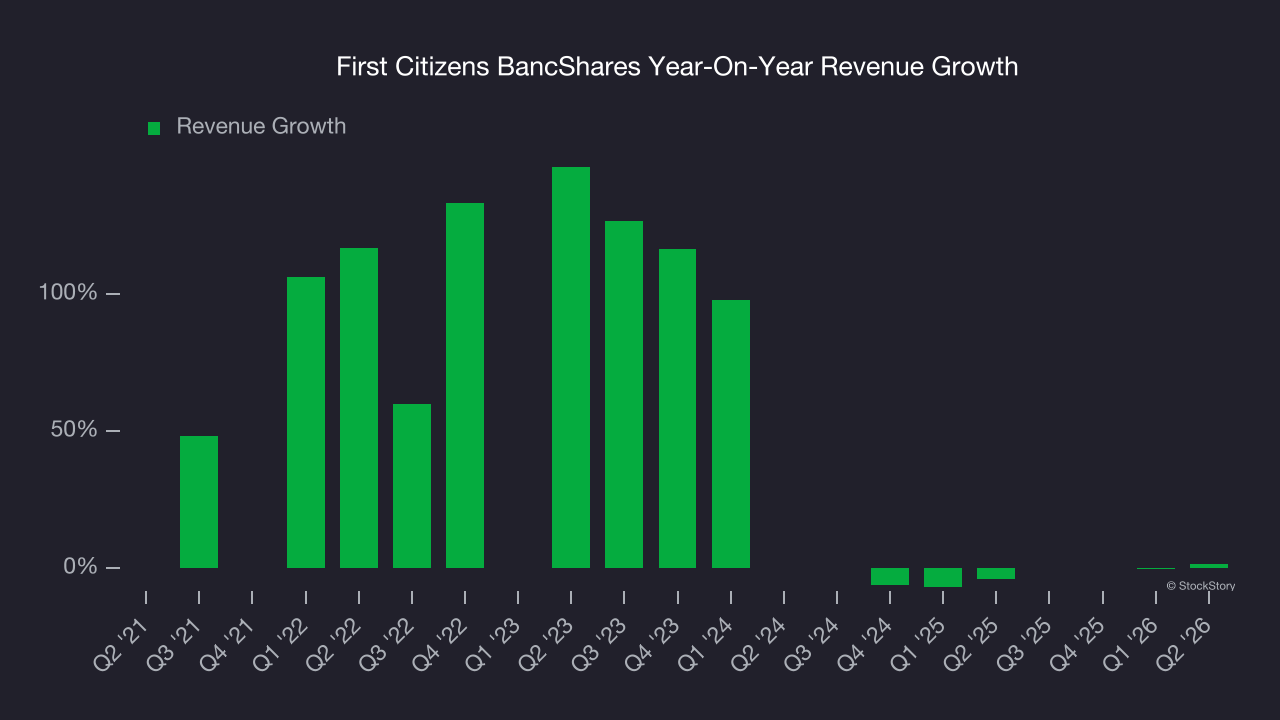 Note: Quarters not shown were determined to be outliers because they were impacted by outsized investment gains/losses that are not indicative of the recurring fundamentals of the business.
2. Net Interest Margin Dropping
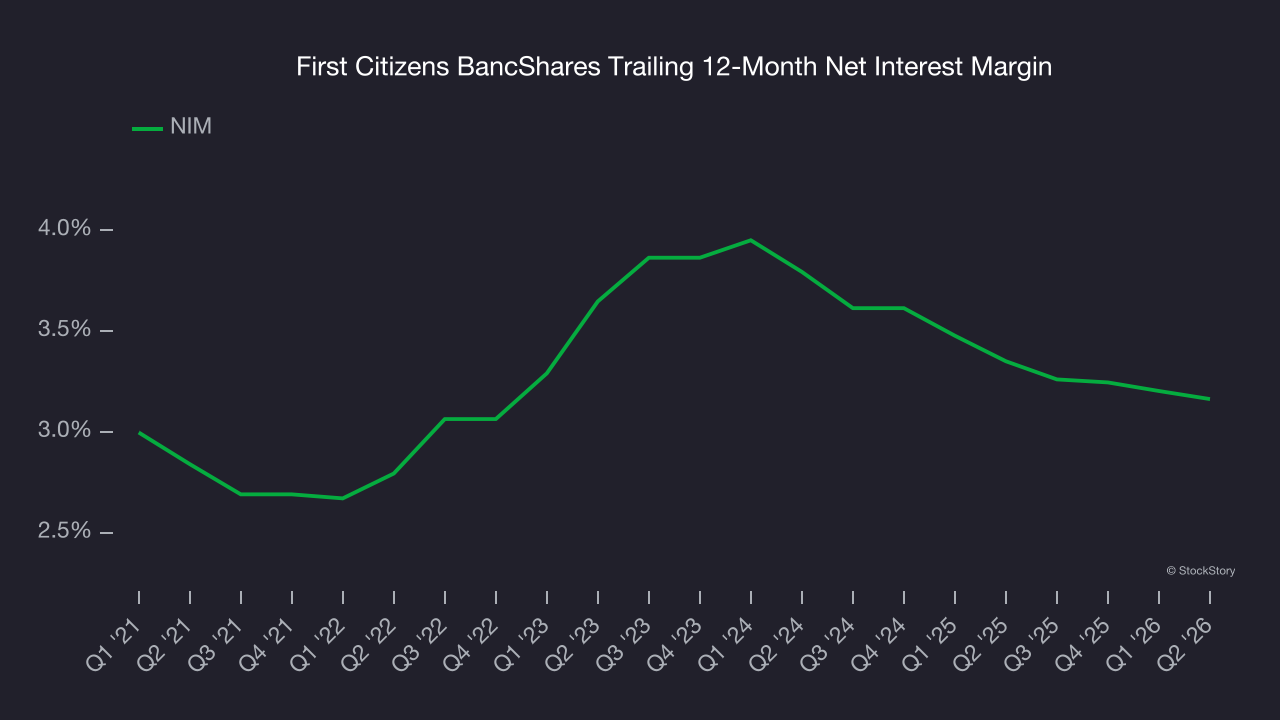
Net interest margin (NIM) serves as a critical gauge of a bank’s fundamental profitability by showing the spread between interest income and interest expenses. It’s essential for understanding whether a firm can sustainably generate returns from its lending operations.
Over the past two years, First Citizens BancShares’s net interest margin averaged 3.2%. Its margin also contracted by 63.1 basis points (100 basis points = 1 percentage point) over that period.
This decline was a headwind for its net interest income. While prevailing rates are a major determinant of net interest margin changes over time, the decline could mean that First Citizens BancShares either faced competition for loans and deposits or experienced a negative mix shift in its balance sheet composition.
3. EPS Took a Dip Over the Last Two Years
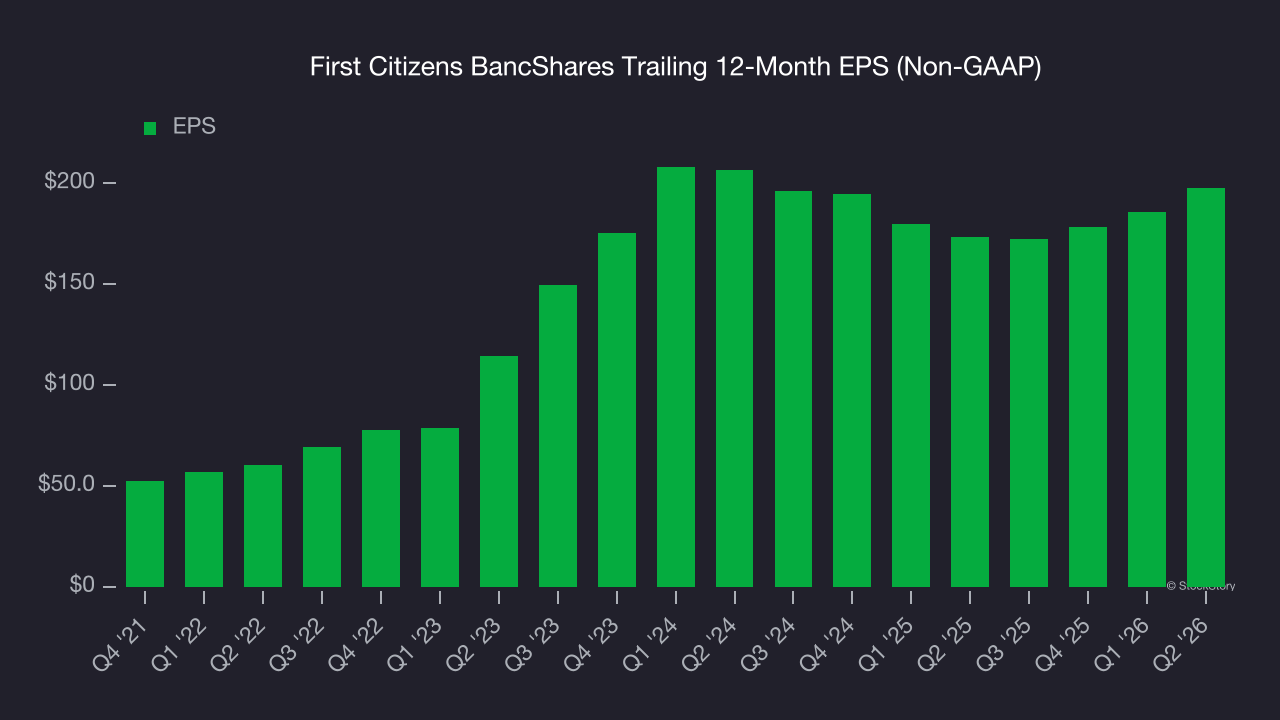
Although long-term earnings trends give us the big picture, we like to analyze EPS over a shorter period to see if we are missing a change in the business.
Sadly for First Citizens BancShares, its EPS and revenue declined by 2.1% and 2.9% annually over the last two years. We tend to steer our readers away from companies with falling revenue and EPS, where diminishing earnings could imply changing secular trends and preferences. If the tide turns unexpectedly, First Citizens BancShares’s low margin of safety could leave its stock price susceptible to large downswings.
Final Judgment
First Citizens BancShares isn’t a terrible business, but it doesn’t pass our quality test. That said, the stock currently trades at 1.1× forward P/B (or $2,097 per share). While this valuation is reasonable, we don’t really see a big opportunity at the moment. We’re fairly confident there are better investments elsewhere. We’d recommend looking at the most entrenched endpoint security platform on the market.
High-Quality Stocks for All Market Conditions
WHILE YOU’RE HERE: Top 9 Market-Beating Stocks. The best stocks don’t just beat the market once. They do it again. And again. Robust revenue growth, rising free cash flow, returns on capital that leave their competition in the dust. The market has already rewarded these businesses.
But our AI platform says the party isn’t over. Find out which 9 stocks made the cut this week — FREE. Get Our Top 9 Market-Beating Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Tecnoglass (+1,552% between June 2020 and June 2025). Find your next big winner with StockStory today.