
As the craze of earnings season draws to a close, here’s a look back at some of the most exciting (and some less so) results from Q2. Today, we are looking at specialty equipment distributors stocks, starting with Alta (NYSE: ALTG).
Historically, specialty equipment distributors have boasted deep selection and expertise in sometimes narrow areas like single-use packaging or unique lighting equipment. Additionally, the industry has evolved to include more automated industrial equipment and machinery over the last decade, driving efficiencies and enabling valuable data collection. Specialty equipment distributors whose offerings keep up with these trends can take share in a still-fragmented market, but like the broader industrials sector, this space is at the whim of economic cycles that impact the capital spending and manufacturing propelling industry volumes.
The 8 specialty equipment distributors stocks we track reported a very strong Q2. As a group, revenues beat analysts’ consensus estimates by 5.1%.
Amidst this news, share prices of the companies have had a rough stretch. On average, they are down 7.6% since the latest earnings results.
Alta (NYSE: ALTG)
Founded in 1984, Alta Equipment Group (NYSE: ALTG) is a provider of industrial and construction equipment and services across the Midwest and Northeast United States.
Alta reported revenues of $475.5 million, down 1.2% year on year. This print fell short of analysts’ expectations by 3.1%, but it was still a strong quarter for the company with a beat of analysts’ EPS and EBITDA estimates.
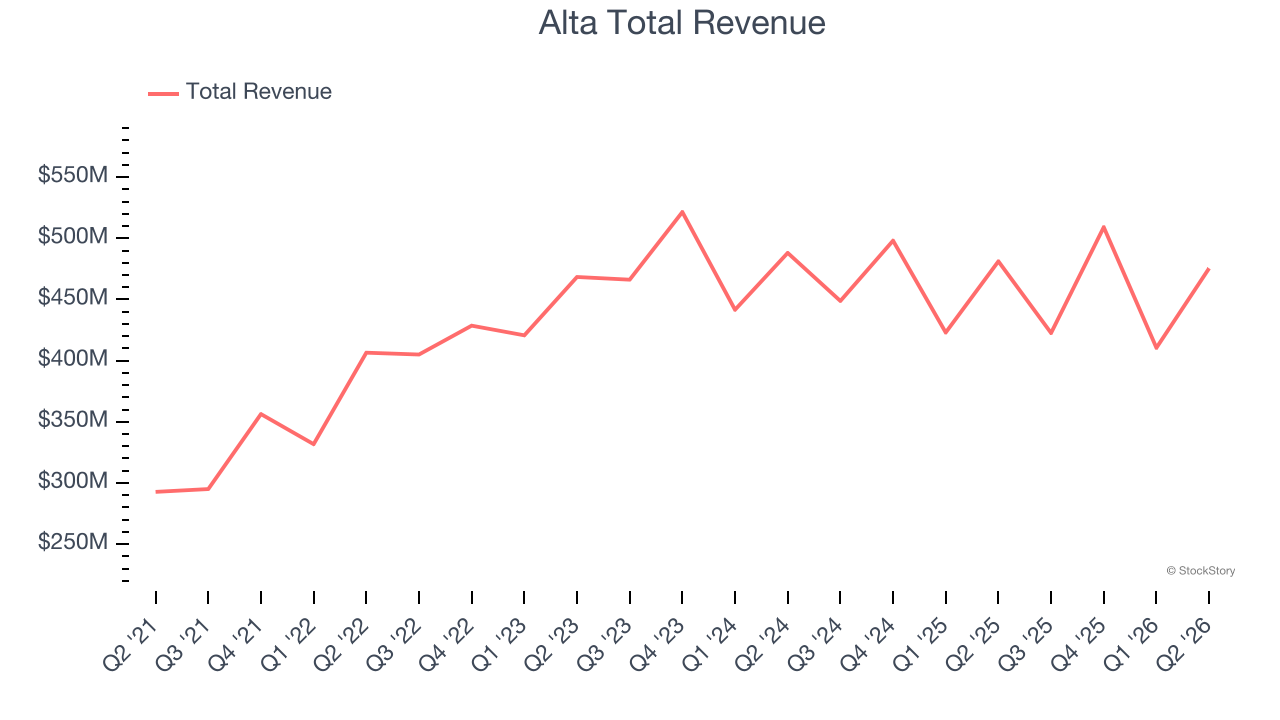
Alta delivered the weakest performance against analyst estimates and slowest revenue growth among its peers. Investor expectations, however, were likely higher than Wall Street’s published projections, leaving some wishing for even better results (analysts’ consensus estimates are those published by big banks and advisory firms, not the investors who make buy and sell decisions). The stock is down 17.3% since reporting and currently trades at $6.10.
Is now the time to buy Alta? Access our full analysis of the earnings results here, it’s free.
Best Q2: Richardson Electronics (NASDAQ: RELL)
Founded in 1947, Richardson Electronics (NASDAQ: RELL) is a distributor of power grid and microwave tubes as well as consumables related to those products.
Richardson Electronics reported revenues of $66.2 million, up 27.6% year on year, outperforming analysts’ expectations by 19.6%. The business had an incredible quarter with a beat of analysts’ EPS and EBITDA estimates.
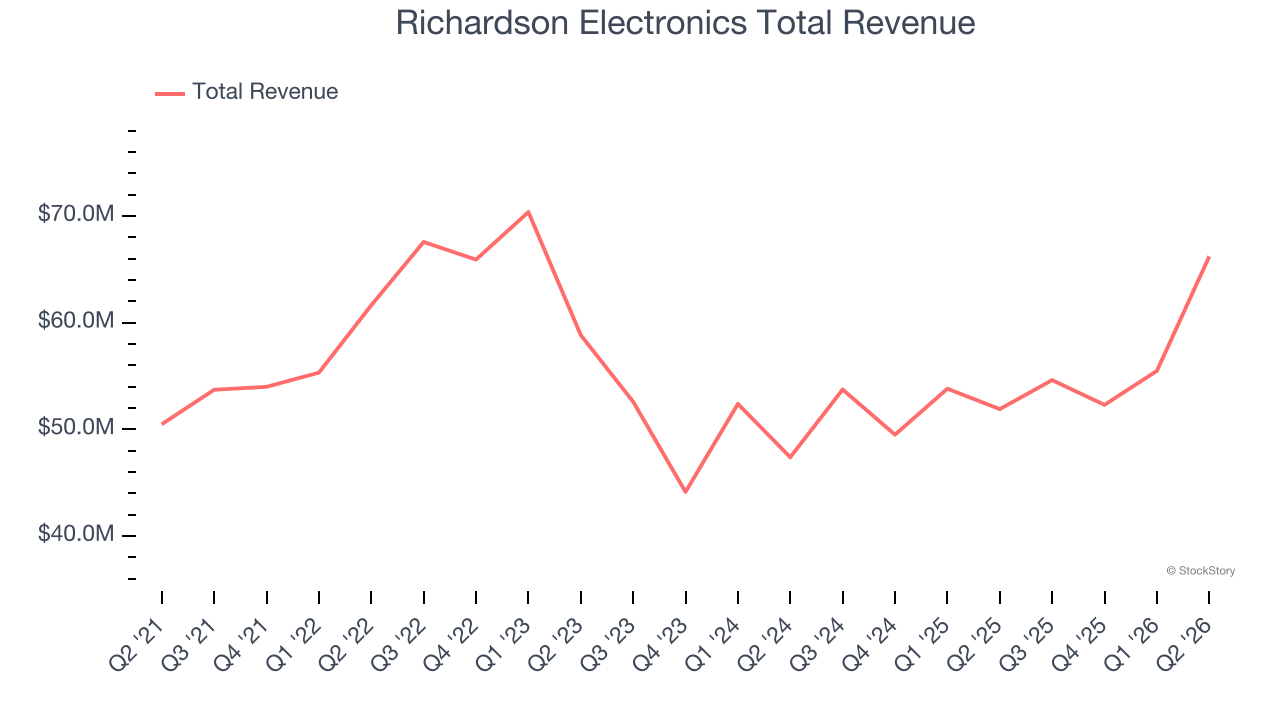
Richardson Electronics scored the biggest analyst estimate beat and fastest revenue growth of the whole group. Although it had a fine quarter compared to its peers, the market seems unhappy with the results as the stock is down 1.5% since reporting. It currently trades at $17.75.
Is now the time to buy Richardson Electronics? Access our full analysis of the earnings results here, it’s free.
Weakest Q2: SiteOne (NYSE: SITE)
Known for distributing John Deere tractors and LESCO turf care products, SiteOne Landscape Supply (NYSE: SITE) provides landscaping products and services to professionals, including irrigation, lighting, and nursery supplies.
SiteOne reported revenues of $1.53 billion, up 4.7% year on year, falling short of analysts’ expectations by 0.7%. It was a softer quarter as it posted a significant miss of analysts’ EPS and EBITDA estimates.
As expected, the stock is down 12.6% since the results and currently trades at $90.40.
Read our full analysis of SiteOne’s results here.
Custom Truck One Source (NYSE: CTOS)
Inspired by a family gas station, Custom Truck One Source (NYSE: CTOS) is a distributor of trucks and heavy equipment.
Custom Truck One Source reported revenues of $563.4 million, up 10.2% year on year. This number surpassed analysts’ expectations by 8.8%. It was an incredible quarter as it also recorded a beat of analysts’ EPS and EBITDA estimates.
Custom Truck One Source pulled off the highest full-year guidance raise in the group. The stock is down 14.3% since reporting and currently trades at $9.11.
Read our full, actionable report on Custom Truck One Source here, it’s free.
Hudson Technologies (NASDAQ: HDSN)
Founded in 1991, Hudson Technologies (NASDAQ: HDSN) specializes in refrigerant services and solutions, providing refrigerant sales, reclamation, and recycling.
Hudson Technologies reported revenues of $78.35 million, up 7.5% year on year. This print beat analysts’ expectations by 5.6%. Taking a step back, it was a mixed quarter as it recorded a significant miss of analysts’ EPS estimates.
The stock is down 15.1% since reporting and currently trades at $5.28.
Read our full, actionable report on Hudson Technologies here, it’s free.
Market Update
Over the past year, investors have been forced to repeatedly answer the same question: what is the market’s biggest risk? The answer has changed several times, and each shift has reshaped market leadership.
Late in 2025 and early 2026, artificial intelligence became the market’s primary uncertainty. Investors questioned whether AI would erode software pricing power and weaken competitive moats as AI made it easier to replicate once-differentiated products.
By the spring, technology took a back seat to geopolitics. The U.S. conflict with Iran briefly became the market’s dominant narrative, raising concerns about oil prices, inflation, and global growth. But as energy markets remained orderly and fears of a prolonged supply disruption faded, investors quickly turned their focus back to fundamentals.
Want to invest in winners with rock-solid fundamentals? Check out our Top 5 Quality Compounder Stocks and add them to your watchlist. These companies are poised for growth regardless of the political or macroeconomic climate.