
Food flavoring company McCormick (NYSE: MKC) announced better-than-expected revenue in Q3 2026, with sales up 17.4% year on year to $2.02 billion. Its non-GAAP profit of $0.86 per share was 13.8% above analysts’ consensus estimates.
Is now the time to buy McCormick? Find out by accessing our full research report, it’s free.
McCormick (MKC) Q3 2026 Highlights:
- Revenue: $2.02 billion vs analyst estimates of $1.97 billion (17.4% year-on-year growth, 2.6% beat)
- Adjusted EPS: $0.86 vs analyst estimates of $0.76 (13.8% beat)
- Management reiterated its full-year Adjusted EPS guidance of $3.09 at the midpoint
- Operating Margin: 10.7%, down from 16.7% in the same quarter last year
- Free Cash Flow Margin: 5.5%, down from 11.9% in the same quarter last year
- Sales Volumes were flat year on year (1.2% in the same quarter last year)
- Market Capitalization: $12.5 billion
Brendan M. Foley, Chairman, President, and CEO, stated, "Third quarter results demonstrate the resilience and differentiated performance of our flavor-focused business model in a dynamic operating environment. We delivered strong sales growth, including organic growth across our global flavor portfolio, while expanding our profit margins. Disciplined productivity initiatives helped offset rising input and freight costs, supporting margin expansion and enabling continued investment in our brands to drive long-term profitable growth. Overall, performance reflected solid base business contribution and accretion from the McCormick de Mexico acquisition, where we have substantially completed its integration."
Company Overview
The classic red Heinz ketchup bottle’s competitor, McCormick (NYSE: MKC) sells food-flavoring products like condiments, spices, and seasoning mixes.
Revenue Growth
Examining a company’s long-term performance can provide clues about its quality. Any business can experience short-term success, but top-performing ones enjoy sustained growth for years.
With $7.69 billion in revenue over the past 12 months, McCormick is one of the larger consumer staples companies and benefits from a well-known brand that influences purchasing decisions. However, its scale is a double-edged sword because there are only so many big store chains to sell into, making it harder to find incremental growth. To accelerate sales, McCormick likely needs to optimize its pricing or lean into new products and international expansion.
As you can see below, McCormick grew its sales at a tepid 5.2% compounded annual growth rate over the last three years, but to its credit, consumers bought more of its products.
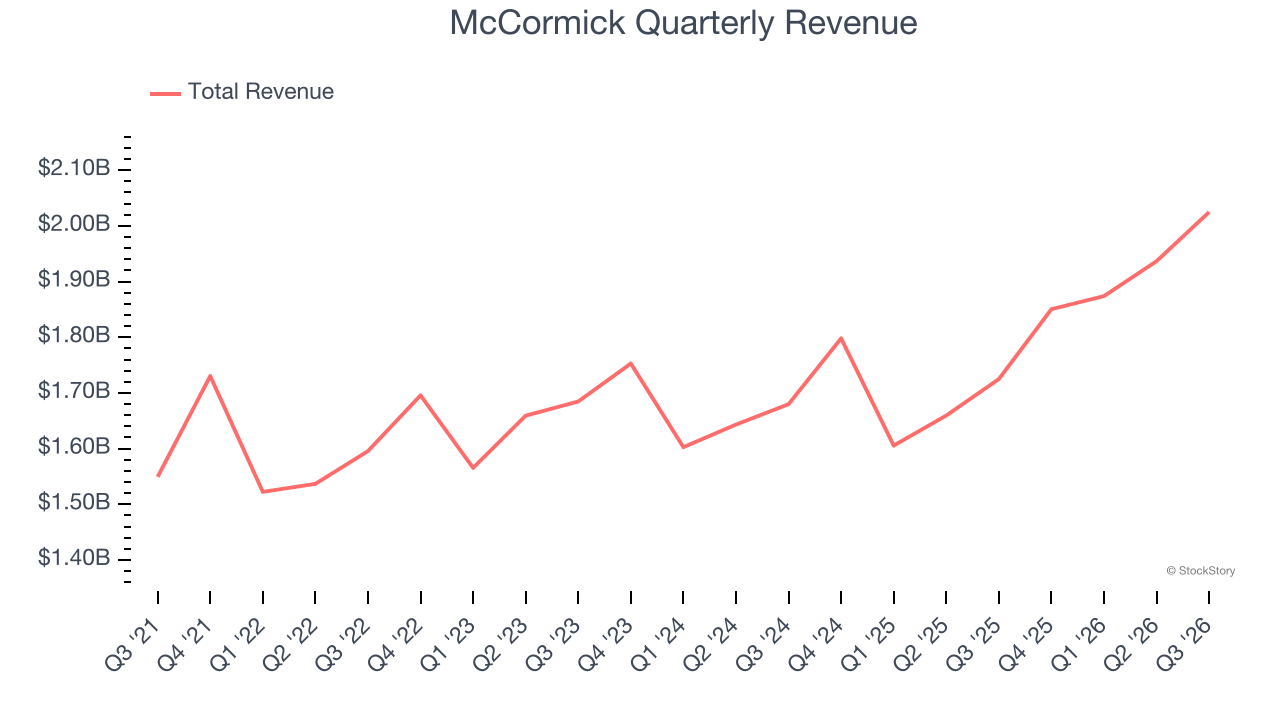
This quarter, McCormick reported year-on-year revenue growth of 17.4%, and its $2.02 billion of revenue exceeded Wall Street’s estimates by 2.6%.
Looking ahead, sell-side analysts expect revenue to grow 5.3% over the next 12 months, similar to its three-year rate. This projection is above the sector average and suggests its newer products will help sustain its historical top-line performance.
ALSO WORTH WATCHING: Nvidia’s Quiet Partner. Nvidia’s chips cost a hundred grand. The connectors that make them work cost even more. One company makes them all.
Every AI server needs specialized infrastructure the chip companies don’t make. High-speed cables. Power connectors. Thermal sensors. This 90-year-old company built a monopoly on it. The AI boom just started. This stock is still flying under the radar. Claim The Stock Ticker Here for FREE.
Volume Growth
Revenue growth can be broken down into changes in price and volume (the number of units sold). While both are important, volume is the lifeblood of a successful staples business as there’s a ceiling to what consumers will pay for everyday goods; they can always trade down to non-branded products if the branded versions are too expensive.
McCormick’s quarterly sales volumes have, on average, stayed about the same over the last two years. This stability is normal because the quantity demanded for consumer staples products typically doesn’t see much volatility. 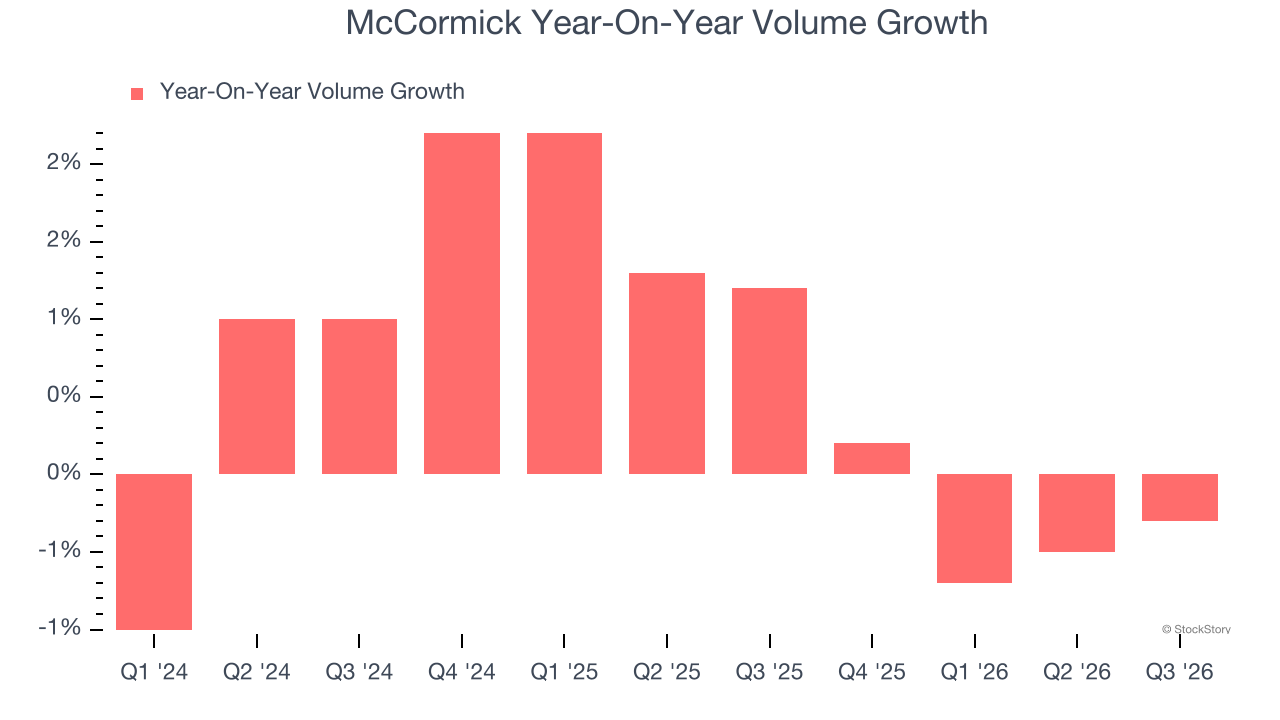
In McCormick’s Q3 2026, year on year sales volumes were flat. This result was more or less in line with its historical levels.
Key Takeaways from McCormick’s Q3 Results
It was encouraging to see McCormick beat analysts’ revenue expectations this quarter. We were also glad its EPS outperformed Wall Street’s estimates. Overall, this print had some key positives. The stock traded up 4% to $48.26 immediately following the results.
Indeed, McCormick had a rock-solid quarterly earnings result, but is this stock a good investment here? If you’re making that decision, you should consider the bigger picture of valuation, business qualities, as well as the latest earnings. We cover that in our actionable full research report which you can read here (it’s free).